

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Off‑Road Fuel Tank Market to Expand at 5.48% CAGR, Reaching USD 3,191.34 Million by 2032

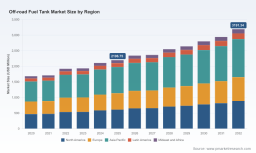
Off Road Fuel Tank Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As off-highway equipment manufacturers, component suppliers, and investors set strategy for 2026, the off road fuel tank market is entering a phase where tactical choices will determine multi-year outcomes. PW Consulting’s new market brief—built on a 2020–2025 historical baseline and a 2026–2032 forecast—shows a market expanding from a 2025 base of USD 2,196.75 Million and growing at a 5.48% CAGR through the forecast window. By 2032 the market is sized to cross the USD 3.1 billion threshold under our central scenario. These headline metrics are more than a vanity number: they quantify the commercial runway and the scale of investment required to win.
Off Road Fuel Tank Market
Executive snapshot — why this matters for 2026 decision cycles
-
Market momentum: Modest but stable CAGR and a clear upward path create a predictable backdrop for capex and capacity planning across materials, molding, and metal fabrication segments.
Off Road Fuel Tank Market -
Margin pressure vectors: Raw material volatility and tightening emissions rules are converging to reshape cost structures and product specification requirements.
Off Road Fuel Tank Market -
Competitive balance: Concentration metrics indicate a market where scale provides advantage but where niche specialists and aftermarket players can still capture meaningful share through technology and service differentiation.
Data-driven dynamics shaping supplier and OEM strategy
Three structural drivers will dominate boardroom conversations in 2026:
-
Input-cost inflation and pass-through complexity. Recent market signals show aluminum mill shapes up ~39% and steel mill products ~21% year-on-year in an interval through early 2026. Concurrently, HDPE pricing has traded at elevated levels (about USD 1,227/MT in Q2 2025). These movements materially affect metal- and plastic-based tank economics and force suppliers to refine cost-plus frameworks, hedging approaches, and long-term supplier contracts.
-
Regulatory tightening on emissions and heavy-duty greenhouse gases. Ongoing EPA and CARB enforcement on evaporative emissions for small off-road equipment, plus heavy-duty GHG standards that touch off-road operations, are accelerating adoption of multilayer plastic designs and low-permeation solutions. Compliance is not optional; it is a market entry and feature requirement in key buying centers.
-
Aftermarket and specialized-volume growth. Operators in mining, construction, agriculture, and long-range exploration are demanding higher-capacity, more rugged, or auxiliary fuel solutions—creating durable demand pockets that reward product innovation and fast service response.
Strategic implications for 2026 planning
-
Portfolio and materials posture. Procurement and R&D teams must view metal and polymer routes as complementary strategies, not binaries. Elevated metal prices argue for engineering investments in polymer alternatives where regulatory compliance and performance allow; conversely, where structural robustness or extreme-capacity needs persist, metal fabrication investments remain essential. The right mix will be defined at the product-family level.
-
Supply-chain risk management. The degree of raw-material price movement observed argues for layered mitigation: multi-source qualification, indexed supplier contracts, and selective vertical integration. Firms should run scenario-based pass-through models tied to both aluminum/steel and HDPE indices to quantify margin exposure under up and down cycles.
-
Regulatory-driven product roadmaps. Teams must accelerate low-permeation multi-layer designs and create compliance-forward product families. Early certification and homologation are competitive advantages—especially for OEMs supplying into CARB and EPA-sensitive markets.
-
Aftermarket as a margin lever. Auxiliary and replacement tanks represent a resilient, often higher-margin channel. Investments in fast-turn manufacturing, modular mounting systems, and field-service solutions can defend OEM relationships and open direct-to-operator revenue streams.
-
M&A and partnership playbook. With the market showing a moderate level of concentration (top‑3 firms capture roughly a third of volume, top‑5 approaches half), strategic M&A—targeting technology-enabled blow molders, high-capacity fabricators, or aftermarket specialists—remains a pragmatic route to accelerate scale and capability.
Competitive landscape — profiles and practical takeaways
The market is populated by diversified metal fabricators, high-volume thermoplastic blow molders, aftermarket specialists, and bespoke racing/utility cell makers. Our review of leading players yields five observable strategic archetypes and recommended 2026 actions:
-
Large custom metal fabricators (e.g., IFH Group, Standard Technologies). Strengths: scale in heavy-gauge steel and aluminum, deep OEM relationships, and capacity for custom reservoirs. Action: capture premium margin by offering integrated fuel system modules and long-term supply agreements indexed for material-cost movement.
-
High-volume polymer specialists (e.g., Agri-Industrial Plastics, Elkamet). Strengths: multi-layer HDPE expertise, regulatory-compliant low-permeation designs, and cost-efficient volume production. Action: invest in new resin blends and co-extrusion capabilities to extend performance envelopes while locking raw material exposure via strategic resin supply agreements.
-
Aftermarket and auxiliary system providers (e.g., Transfer Flow, TITAN Fuel Tanks). Strengths: brand recognition among end-users, rapid time-to-market for niche needs, and aftermarket distribution networks. Action: scale digital channels and service offerings (installation, warranty extensions) to convert one-time buyers into recurring customers.
-
Heavy-capacity integrators (e.g., Niece Equipment). Strengths: capability to deliver very large-volume tanks and mobile refueling systems for mining and heavy construction. Action: target long-cycle service contracts and remote fueling solutions as operators consolidate fleet management.
-
Specialty and motorsport suppliers (e.g., Harmon Racing Cells, Extreme Tanks). Strengths: high-performance safety cells, rapid customization, and niche engineering skill. Action: leverage motorsport pedigree to spin performance-derived features into mainstream off-road safety and durability claims.
What PW Consulting’s full report delivers (practical, operational intelligence)
Our brief is a “decision support system” designed for commercial, procurement, and M&A teams. It contains:
-
A transparent market-sizing framework and demand-modeling workbook that ties fleet populations, utilization assumptions, and replacement cycles to revenue forecasts—enabling users to run bespoke scenarios for 2026 planning.
-
A modular cost-benchmarking package that isolates raw material, labor, and overhead drivers and maps them to typical bill-of-materials across metal and polymer architectures—built for sourcing negotiations and margin-protection strategies.
-
Regulatory-impact assessments with compliance roadmaps, required test protocols, and an implementation timeline to guide product homologation in regulated markets.
-
Supplier and capability heat maps, including qualifiers for low-perm plastic systems, heavy-duty fabricated reservoirs, aftermarket fitment networks, and rapid-response electromechanical subassemblies.
-
Commercial playbooks: go-to-market templates for premium OEM programs, distributor partnerships, and direct-service aftermarket channels—complete with sample contractual language and KPIs.
-
M&A target screening criteria and valuation sensitivities tied to concentration dynamics, margin leverage, and technology gaps—helpful for private equity and strategic buyers alike.
How leading teams should use these insights in 2026
-
Finance teams: adopt stress-tested scenarios that link input-cost volatility to EBITDA sensitivity; use these to set covenant buffers and capex phasing.
-
Procurement teams: convert cost models into multi-year supplier agreements with indexed clauses and volume flex provisions to protect margins.
-
Product and engineering: prioritize low-permeation, multi-layer plastic solutions for regulated footprints while executing lightweighting and corrosion-resistance projects for metal tanks.
-
M&A and corporate development: focus on bolt-on targets that fill capability gaps (e.g., aftermarket networks, blow-molding scale, or high-capacity fabrication).
-
Commercial teams: test premium aftermarket subscription and service bundles in high-utilization verticals such as mining and construction to monetize uptime and refueling services.
Closing — a trailer, not a reveal
PW Consulting’s market brief marries macro sizing—anchored to a 2025 base of USD 2,196.75 Million and a 5.48% CAGR outlook—with hands-on tools for 2026 operationalization. In keeping with a “trailer” approach, this note highlights the strategic contours and actionable levers without publishing the granular regional and application splits that are often the decisive inputs in contract negotiations and M&A valuation. For teams that need the full set of segment-level breakouts, supplier scorecards, and downloadable scenario models to execute 2026 plans, the complete report and accompanying analyst support are available via our research portal.
Contact PW Consulting to access the full report, download the forecasting workbook, or arrange a custom workshop to translate the findings into a 90-day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Off Road Fuel Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com