

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gestational Trophoblastic Disease Market to Expand at a 5.81% CAGR Through 2032, Sparking Growth Opportunities in Chemotherapy and Diagnostics

PW Consulting: Strategic Brief — Gestational Trophoblastic Disease Market Outlook 2026 and Beyond
Executive snapshot
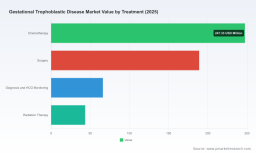
PW Consulting today publishes a strategic preview of our comprehensive market study on Gestational Trophoblastic Disease (GTD), designed specifically to inform executive decision-making in 2026. The GTD market has demonstrated steady expansion over the 2020–2025 base period, growing from a mid‑hundreds million USD base to an estimated USD 546.0 Million in 2025. Under our baseline forecast (2026–2032) the market is projected to grow at a compound annual growth rate (CAGR) of 5.81%, reaching an estimated USD 810.3 Million by 2032. This trajectory is being shaped by clinical advances, evolving guideline recommendations, growing off‑label and trial use of immunotherapies, and persistent demand for established chemotherapeutics and diagnostic monitoring services.
Gestational Trophoblastic Disease Market
Why this report matters for 2026 strategy
- Actionable forecasting: Our model combines epidemiology, treatment pathway adoption scenarios, and pricing/reimbursement assumptions to translate clinical developments into revenue implications across the forecast horizon.
- Decision-grade intelligence: The report bridges clinical nuance (e.g., low‑risk vs high‑risk GTN pathways) with commercial realities—supply chains for injectable chemotherapy, generics pressure, and payers’ growing scrutiny of immuno‑oncology for rare indications.
- Playbook orientation: Rather than theoretical commentary, the work provides go/no‑go decision frameworks, commercial launch sequencing guidance, and partnership archetypes relevant to pharma, diagnostics firms, and private equity investors active in onco‑rare disease portfolios.
Market dynamics shaping near‑term choices
Several interlocking dynamics create both risk and opportunity for stakeholders in 2026:
Gestational Trophoblastic Disease Market
- Therapeutic continuity vs disruption: Standard single‑agent regimens (methotrexate +/- folinic acid or actinomycin D) continue to deliver >95% success in low‑risk GTN, while multi‑agent EMA/CO regimens yield long‑term survival in the mid‑80s to mid‑90s percent range for high‑risk cases. These high baseline cure rates mean innovations must demonstrate either clear safety/tolerability advantages, avoidance of escalation to multi‑agent chemotherapy, or superior outcomes in refractory disease to gain traction.
- Immunotherapy enters clinical practice: Recent trials and guideline shifts are accelerating interest in checkpoint inhibitors. Notably, ESMO‑presented data from the TROPHAMET program showed a meaningful improvement in complete response metrics when avelumab was combined with an 8‑day methotrexate schedule versus methotrexate alone in low‑risk GTN—an outcome now reflected in 2025 international consensus guidance as a potential option to reduce escalation to multi‑agent regimens in select settings.
- Off‑label and guideline‑driven use in resistant disease: Checkpoint inhibitors (e.g., pembrolizumab) are being recommended by some national payers for multi‑drug resistant high‑risk GTN after multiple chemotherapy lines, while broader regulatory approvals for GTD remain limited. This creates a complex mix of trial, compassionate use, and payer‑specific access pathways through 2026.
- Adjunct and repurposing research: Early‑stage modalities—focused ultrasound in localized research programs and preclinical explorations of statin repurposing for choriocarcinoma—signal a widening innovation set, though commercial availability and scale remain several years out.
Competitive landscape — capability map, not a leaderboard
The GTD market exhibits moderate concentration: the top three companies capture a meaningful share of market activity, while the top five firms account for a majority of commercial presence and supply chain influence. This structure supports differentiated competitive moves across innovators and generics manufacturers.
Gestational Trophoblastic Disease Market
- Established oncology leaders (Pfizer, Novartis, Bristol‑Myers Squibb): These firms supply key chemotherapeutic agents that underpin standard-of-care single‑agent and multi‑agent regimens. For incumbents, the strategic choices in 2026 center on lifecycle management (supply continuity, formulation improvements), value‑based contracting in advanced markets, and selective clinical investments that protect or expand regimen relevance in the face of immunotherapy options.
- Generics and injectables specialists (Hikma, Teva, Fresenius Kabi): Price competition and manufacturing scale are core advantages. Near‑term strategic levers include sterile injectable capacity investments, geographic expansion into under‑served referral centres, and service bundles (diagnostic integration, patient support) to defend margins.
- Immuno‑oncology entrants and alliances (Merck & Co., Merck KGaA/Pfizer alliance for avelumab): Checkpoint inhibitors are increasingly relevant for chemo‑resistant cases and as potential first‑line augmentations. Companies controlling these agents face choices around label expansion strategies, payer evidence generation, and partnering with centers of excellence for real‑world outcome studies.
Recent developments that change tactical priorities
- March 2026 — TROPHAMET data announced at ESMO: Avelumab combined with an 8‑day methotrexate schedule demonstrated a material improvement in hCG normalization rates versus methotrexate alone in low‑risk GTN. This evidence is accelerating payer conversations and could alter first‑line algorithms in jurisdictions that rapidly adopt guideline updates.
- 2025 international consensus guidelines: Collaborative guidance from major GTD and gynecologic oncology societies explicitly recognize avelumab as an option in selected low‑risk cases—creating an access inflection point for companies with immunotherapy portfolios and for suppliers of methotrexate who participate in combination regimens.
- Payer and regulatory nuance: Pembrolizumab is being recommended in some national pathways for patients who have failed multiple chemotherapy lines, but full regulatory approvals for checkpoint inhibitors in GTD remain limited—presenting a patchwork access environment.
- Innovation watch: Focused ultrasound and statin repurposing remain investigational; these areas merit monitoring for future partnership or licensing opportunities rather than immediate commercial bets.
What’s in the full PW Consulting report (practical components)
- Rigorous market-sizing and forecast model (2020–2032) with scenario toggles for guideline adoption, immunotherapy penetration, and pricing pressure.
- Detailed treatment‑pathway maps and patient flow models that translate clinical decision points into unit volumes and service demands.
- Payer and reimbursement playbooks, including HTA requirements, coverage pathways for off‑label immunotherapies, and contracting templates for high‑cost agents used in rare cancers.
- Competitive dossiers and capability matrices for the leading manufacturers and service providers (manufacturing footprints, sterile injectable capacity, portfolio overlap, clinical investment roadmaps).
- Clinical pipeline assessment and probability‑weighted launch impact analysis for key immunotherapies, novel therapeutics, and diagnostic/monitoring technologies.
- Commercial strategy blueprints: go‑to‑market sequencing, tendering tactics in emerging markets, and patient support program designs to maximize adherence to HCG monitoring protocols.
- M&A and partnership screening tools: acquisition candidate scoring, integration risk checklists, and divestiture playbooks tailored for rare‑oncology assets.
- Real‑world evidence and post‑launch outcomes trackers templates to support payer negotiations and guideline adoption.
Actionable recommendations for 2026 corporate planning
- For innovators with immunotherapy assets: accelerate targeted RWE (real‑world evidence) programs in referral centers and prepare flexible pricing strategies tied to outcome milestones—this reduces payer resistance where label expansion is limited.
- For generics and injectables manufacturers: prioritize sterile injectable capacity upgrades and geographic distribution partnerships to capture demand volatility from occasional guideline‑driven therapy shifts.
- For companies owning methotrexate/dactinomycin portfolios: defend regimen relevance by investing in co‑development studies with immunotherapy partners and by offering integrated diagnostic/monitoring services that simplify clinician adoption.
- For investors and private equity: screen targets for manufacturing resilience, regulatory risk exposure (off‑label reliance), and differentiated service offerings (diagnostic+therapy bundles) that increase stickiness.
- Across the board: embed payer engagement at the earliest trial design stage for any program targeting GTD, given the high cure rates with standard regimens and the premium payers place on demonstrable reductions in escalation to multi‑agent chemotherapy.
How PW Consulting supports your next moves
Our GTD report is structured to move teams from insight to implementation. We provide modular deliverables (board briefs, acquisition screens, country access dossiers, and launch readiness checklists) and a responsive advisory option to help operationalise recommendations in the 12–18 month window following publication. For teams evaluating portfolio allocation, the report’s scenario models allow rapid sensitivity testing of market outcomes under alternate guideline adoption, therapeutic success, and pricing environments.
Next steps
This briefing is intentionally selective: it surfaces the critical levers and recent inflection points shaping GTD strategy while withholding granular segment tables and market split figures to preserve the investigative value of the full report. Executive teams seeking the complete dataset, region‑level forecasts, segment breakdowns, and competitor revenue estimates are invited to access the full PW Consulting GTD Market Report via our publication page. Engage PW Consulting for a tailored executive workshop that translates our findings into a bespoke 90‑day action plan aligned to your business objectives.
For detailed analysis of this topic, please visit the official page: Gestational Trophoblastic Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com