

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Data Center Consulting Services Market Poised for Strong Expansion at 13.45% CAGR

Data Center Consulting Services Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
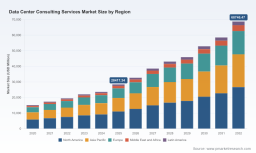
As enterprises accelerate AI deployments, hybrid cloud transformations and sustainability commitments, the global market for data center consulting services has reached an inflection point. Our PW Consulting Market Report — anchored on a robust historical series (2020–2025) and a forward-looking forecast (2026–2032) — shows the market expanding at a compound annual growth rate (CAGR) of 13.45%. After a steady climb from 2020, the market size reached roughly USD 28.4 billion in 2025 and is projected to more than double over the forecast horizon, reflecting the capital intensity and strategic complexity of modern data center programs. For executives making capital allocation, site selection and operating-model decisions in 2026, the timing and granularity of insight could materially affect both cost and operational risk.
Data Center Consulting Services Market
Why 2026 Is a Strategic Turning Point
- Convergence of capacity and capability demand: Cloud and AI workloads are driving demand for new capacity and for higher‑density, purpose‑built facilities. Market participants from engineering firms to IT consultancies and real‑estate specialists are broadening capabilities to capture this demand.
- Regulatory and compliance acceleration: New emissions and privacy rules are shifting design specs and operating requirements. Examples include state-level emissions standards for emergency generators and national rules that tighten controls around bulk personal data — both of which can alter siting, equipment selection and operating procedures.
- Workforce and delivery model stress points: Large-scale upskilling and apprenticeship programs are emerging to address shortages in mission‑critical trades. Simultaneously, prime contractors and consultancies are investing in digital project-delivery and AI-enabled capital-program tools to compress schedules and mitigate labour risk.
- Sustainability and biodiversity as investment filters: Investors and hyperscalers are increasingly pricing in ESG outcomes; partnerships that embed biodiversity and regenerative design into campuses are shifting the value equation for greenfield and brownfield projects.
Report at a Glance — Practical, Actionable Content
The PW Consulting report is structured to be operationally useful for C-suite and program teams tasked with building, upgrading or managing data center portfolios. It blends macro forecasting with tactical tools that can be applied immediately within procurement cycles and capital planning windows:
Data Center Consulting Services Market
- Scenario-based market-sizing and demand curves (2026–2032), including sensitivity to key drivers such as AI density, cloud migration rates and regional power constraints.
- Capital- and life‑cycle cost models that translate design decisions (e.g., efficiency, redundancy, generator choices) into multi‑year TCO outcomes under different fuel and emissions regimes.
- Site-selection and resilience frameworks that weight energy, connectivity, regulatory, and community acceptance variables for both hyperscale and enterprise footprints.
- Vendor selection scorecards and RFP templates tailored for design & engineering, strategy & planning, migration, and operations & maintenance engagements.
- Operational playbooks for O&M teams, including KPI libraries, workforce training roadmaps, and digital twin checklists to accelerate commissioning and reduce mean time to repair.
- Regulatory impact toolkits and privacy/compliance matrices that align technical controls with new legal obligations and state-level standards effective in 2026.
- ESG & sustainability playbooks — from embodied carbon accounting to biodiversity integration and energy procurement design patterns — that support investment-grade sustainability narratives.
Note: the report includes detailed segmentations and company-level profiles underpinning these tools. To preserve the strategic value of those granular datasets and vendor rankings, that proprietary segmentation is available in the full report.
Data Center Consulting Services Market
Competitive Landscape: Reading the Players
The data center consulting ecosystem is a heterogeneous mix of engineering firms, global management consultancies, IT services specialists and real estate advisors. Market concentration metrics indicate the space remains fragmented — with the top few firms holding modest collective share — which creates room for both scale players and specialist boutiques to win business based on project type and client preferences.
- AECOM & Jacobs: Engineering and project-delivery specialists that excel in full lifecycle delivery for mission-critical facilities. Their strengths lie in site engineering, commissioning discipline and large-scale program management across complex regulatory geographies.
- Arup & Ramboll: Technical and sustainability-led firms with deep design capabilities. They are often the go-to partners when architectural integration, thermal management and low-carbon design are priority decision criteria.
- Accenture & IBM Consulting: IT and systems integrators that bridge infrastructure modernization, cloud migration and AI enablement. Accenture’s recent capital delivery capability enhancements and IBM’s hybrid cloud messaging position both as strategic advisors for transformation-led projects.
- Deloitte, PwC & EY: Advisory firms that combine risk, compliance and transaction advisory with the ability to orchestrate complex, multi-stakeholder transformations; they are often engaged at portfolio strategy and M&A stages.
- JLL: Real estate and investment advisory specialists playing a pivotal role in site economics, capacity pipeline assessment and investor due diligence; their market outlooks are watched closely by capital allocators.
- HCL Technologies, Kyndryl & TCS: Tech-centric service firms that focus on infrastructure management and managed services, increasingly positioning themselves around lifecycle O&M and migration services for enterprise clients.
- McKinsey & Company: Strategy and high-level transformation advisory, often engaged for portfolio rationalization, large-scale operating model redesign and AI-driven infrastructure strategies.
Recent market moves underscore how firms are reshaping capabilities: a notable acquisition to strengthen capital project delivery; partnerships that embed biodiversity into campus planning; and public outlooks projecting significant new capacity pipelines — all of which change where and how consultancies compete and collaborate.
How Senior Leaders Should Use This Report in 2026
- CFOs: Use the TCO models and scenario analyses to validate multi‑year capex envelopes, stress-test financing structures, and quantify the value of performance guarantees and O&M outsourcing.
- CTOs & Infrastructure Heads: Leverage migration scorecards and vendor shortlists to accelerate cloud-on-prem decisions and to lock down interoperability and AI-readiness requirements before procurement.
- Real Estate & Portfolio Leads: Apply the site-selection framework and regional scenario planning to prioritize greenfield vs. colocation strategies and to model grid risk and land-use constraints.
- Compliance & Legal Teams: Use the regulatory impact toolkit to map new state and federal rules to contractual obligations, control matrices and consent mechanisms for sensitive datasets.
- HR & Ops Leaders: Adopt the workforce roadmap to align hiring and apprenticeship investments with the project pipeline and digital delivery ambitions.
Signals to Watch in H2 2026 and Beyond
- Announcements of major capacity pipelines and campus launches — these validate demand assumptions and shift supplier capacity.
- Regulatory updates around emissions, emergency power standards and data handling — nuanced compliance costs can change site economics overnight.
- Scaling of workforce training initiatives and apprenticeship rollouts — efficacy here will influence schedule risk and labor cost trajectories.
- Partnerships marrying biodiversity and campus design — these will test market willingness to pay for differentiated ESG outcomes.
- M&A and capability bundling among consultancies — watch for acquisitions that close gaps in capital delivery, digital project tools or sustainability verification.
Conclusion — The Strategic Value of Timely Insight
For 2026, the combination of brisk market growth, regulatory tightening and technology-driven demand means companies can no longer treat data center consulting as a commodity purchase. The PW Consulting report is designed to convert market intelligence into executable plans — supplying senior teams with the templates, scenario models and decision frameworks needed to optimize cost, de‑risk delivery and embed sustainability outcomes. We present a comprehensive, operationally oriented view of the market while preserving the proprietary granularity that clients use to make procurement and investment decisions. For executives serious about securing competitive advantage in the next wave of data center investment, the full report contains the datasets, proprietary scoring matrices and vendor benchmarking that convert high‑level insight into board‑ready recommendations.
Access to the full dataset, segmentation tables, and the vendor comparator suite is available through the PW Consulting report page — where you can download executive summaries, order the full study, and schedule an advisory briefing to align the findings to your 2026 investment roadmap.
For detailed analysis of this topic, please visit the official page: Data Center Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com