

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts Surge: Worldwide Tactical Gloves Market to Reach USD 2,025 Million by 2032
By pmarketresearch, 2026-07-13
Worldwide Tactical Gloves Market: Strategic Outlook for 2026 — Why This Report Matters to Executive Decision-Makers
Executive summary
PW Consulting’s latest Worldwide Tactical Gloves Market report frames the 2026 strategic horizon for manufacturers, procurement leaders, and investors operating at the intersection of defense, public safety, and high-performance outdoor sectors. The market has moved from a solid base in the early 2020s into a period of measured expansion: total industry revenue reached USD 1,478.10 Million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of 4.6% across the 2026–2032 forecast window, culminating in a modeled market size of USD 2,025.0 Million by 2032.
Worldwide Tactical Gloves Market
This release is a preview of the report’s strategic value: it demonstrates the analytical depth executives need to make 2026 decisions while intentionally withholding full segment-level tables and sensitive unit-level datasets to encourage engagement with the full report and downloadable modeling tools on our site.
Worldwide Tactical Gloves Market
Why the 2026 planning cycle is different
-
Digitally enabled operations: Operators increasingly expect tactile interfaces to coexist with protective features. Touchscreen compatibility is now a baseline expectation in many tactical models, creating new product design trade-offs between protection, fit, and digital usability.
Worldwide Tactical Gloves Market -
Hybridization of feature sets: At industry trade shows in early 2026, manufacturers showcased hybrid designs that combine military-grade protections with civilian comfort and modularity — a trend that changes manufacturing planning, BOM complexity, and SKU rationalization strategies.
-
Standards and procurement constraints: Compliance demands (TAA, EN388:2016, EN ISO 21420, MIL‑SPEC, and ANSI/ISEA 105 where applicable) are shaping procurement pipelines and supplier qualification processes — making certification roadmaps a practical strategic lever in 2026.
-
Volatility and demand pockets: The historical series shows non-linear behavior with episodic rebounds and dips. Management teams must therefore move beyond single-scenario forecasting and adopt multi-scenario demand planning that preserves optionality.
Market dynamics and strategic implications
-
Growth trajectory and opportunities — The market’s mid-single-digit CAGR masks important micro-opportunities. While aggregate demand is expanding steadily, growth will be concentrated in products that solve operator pain points: impact mitigation without dexterity loss, temperature adaptability, and seamless device integration. Prioritizing R&D resources toward these capabilities will yield disproportionate returns.
-
Consolidation vs. differentiation — Industry concentration metrics indicate a moderately consolidated market: the top three and five firms capture a meaningful but not dominant share of revenue, leaving space for premium niche entrants and consolidation plays. For strategic buyers, tuck-in acquisitions that provide unique materials science, certification pathways, or distribution access can accelerate scale in targeted segments.
-
Supply chain and material strategies — Common raw inputs (synthetic leather, sheepskin palms, nylon ribspan, molded knuckle reinforcements) are subject to commodity cycles and capacity constraints. Firms should model raw-material pass‑throughs and consider dual-sourcing, vertical integration for critical components, or long-term supply agreements for differentiated materials.
-
Regulatory compliance as competitive moat — Achieving and publicizing compliance to standards such as EN388:2016 and EN ISO 21420 — alongside TAA or MIL‑SPEC where relevant — is increasingly a procurement requirement rather than a marketing afterthought. Investment in testing capacity and certification timelines should be treated as strategic project portfolios with clear ROI gates.
Competitive landscape — what to watch in 2026
Our competitive analysis blends product-level specifications, trade show intelligence, and corporate positioning to create actionable takes that leaders can use immediately.
-
Established performance brands — Companies like Mechanix Wear, 5.11 Tactical, Wiley X, Blackhawk, Oakley, and others remain portfolio anchors. They compete on proven design heritage, distribution reach, and certification completeness. Recent product refreshes and trade show demonstrations underscore a push toward modularity and multi-environment adaptability.
-
Niche technical specialists — Firms such as Magpul, Ironclad, and Outdoor Research compete on narrow performance vectors (e.g., shooting ergonomics, dexterity, sensor compatibility). These players are valuable acquisition targets for larger OEMs seeking rapid capability infusions without in‑house R&D lead time.
-
Regional and industrial players — Companies including MCR Safety and Helikon‑Tex illustrate regional footholds and industrial cross-over strategies. Their strength is local procurement alignment and specialized relationships with public agencies.
-
Market signals from 2026 events — Trade shows and product launches in January 2026 revealed two important currents: a rush to certify modernized designs to international standards, and a wave of hybrid product introductions that balance protection with device usability. These developments are accelerating SKU churn and shortening product life cycles in certain mid-market tiers.
What the PW Consulting report delivers (practical, executable content)
Beyond narrative and forecasts, the report is explicitly designed to be operational for 2026 strategy cycles. Key deliverables include:
-
Proprietary market-sizing model: Financially auditable top-down and bottom-up scenarios with configurable assumptions for procurement cadence, replacement cycles, and regional demand drivers (full modeling workbook included in the full purchase).
-
Go‑to‑market playbooks: Segmented channel strategies for defense procurement, law enforcement contracts, and commercial outdoor retailers — including tender timelines, certification checklists, and bid-win playbooks.
-
Supplier scorecards and supplier-risk dashboards: Operational metrics and a templated RFP structure for vetting material suppliers, testing houses, and contract manufacturers.
-
Product roadmaps and feature-pricing matrices: Decision-support frameworks that quantify the trade-off between protection features, dexterity, and price tolerance for core customer archetypes.
-
M&A screening filters: A prioritization matrix that maps potential targets by capability gap, cost synergies, and certification assets — enabling rapid diligence sprint planning.
Recommendation playbook for 2026
-
Prioritize certification-led product release timelines: Align R&D sprints with testing and certification milestones to reduce go‑to‑market lag and secure procurement qualification ahead of public tenders.
-
Adopt modularity to reduce SKU proliferation: Design common palm and closure platforms that accept swappable protective modules (e.g., knuckle guards, insulation liners) to compress inventory while addressing multiple customer needs.
-
Hedge material exposure: Negotiate long-term contracts or strategic partnerships with suppliers of critical materials (synthetic and natural palm reinforcements) and build a cost-pass-through playbook for large institutional customers.
-
Invest in digital enablement of the product: Small material and seam innovations that preserve touchscreen responsiveness deliver outsized perceived value in procurement evaluations.
-
Evaluate bolt-on acquisitions that add certification or niche ergonomics: Fast-track capability gaps rather than attempting to build every specialized competency organically.
Methodology and data integrity
The report’s base is a 2025 benchmark year with a historical window covering 2020–2025 and a forward forecast through 2032. Our approach triangulates primary interviews, product specification audits, certification registries, trade-show intelligence, manufacturer financial disclosures, and PW Consulting’s proprietary demand model. The forecast reflects an aggregate CAGR of 4.6% over the forecast period and accommodates scenario variants for procurement cycles, technology substitution, and regulatory shifts.
Limitations and the “trailer” approach
In keeping with our “trailer” principle — showcasing analytical depth while preserving the value of the full report — this release highlights high‑level market sizing, strategic takeaways, and competitive dynamics without publishing the full segment-by-region shares, application-level breakout tables, or line-item revenue tables. Those detailed segmentations, the downloadable Excel model, supplier scorecards, and company-level financial overlays are available exclusively in the full report packet and on our web portal.
Next steps for executives
-
Procurement and product chiefs: Use the report’s playbooks and scorecards to accelerate supplier qualification and to validate capital allocation on certification and R&D priorities.
-
M&A and corporate development teams: Leverage the report’s M&A filters to construct a prioritized target list for 90‑day diligence sprints.
-
Investors and private equity: Engage with PW Consulting for a data room review and scenario walk-through to test valuation assumptions against our demand model and concentration metrics.
Accessing the full intelligence
To obtain the complete Worldwide Tactical Gloves Market report, including full segment-level tables, company financial snapshots, and the downloadable forecast model, visit the PW Consulting report page. The full packet contains the operational tools necessary to convert insights into 2026 action plans — from procurement calendars to acquisition targets and product roadmaps.
PW Consulting stands ready to run tailored workshop sessions for executive teams who wish to translate this market intelligence into prioritized three-, six-, and twelve‑month execution plans.
For detailed analysis of this topic, please visit the official page: Worldwide Tactical Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Passion Fruit Seed Oils Market Poised to Grow at 8.12% CAGR Through 2032
By pmarketresearch, 2026-07-13
Worldwide Passion Fruit Seed Oils Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study, "Worldwide Passion Fruit Seed Oils Market", synthesizes primary research, proprietary modelling, and supplier intelligence to deliver an executive-grade playbook for companies evaluating participation or expansion in the passion fruit seed oil value chain in 2026. This briefing highlights the report’s strategic value, core market trajectory, practical modules, competitive dynamics, and the high‑priority actions trustees of corporate strategy, procurement, R&D and M&A should consider this year.
Worldwide Passion Fruit Seed Oils Market
Market snapshot — a concise picture for strategy
On the macro level, the global passion fruit seed oils market has demonstrated steady growth from 2020 through the base year 2025. Measured in USD Million, the market expanded from a modest baseline in 2020 to a substantially larger footprint by 2025. Under our forecast horizon (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 8.12%, reaching a materially larger size by 2032. This trajectory reflects rising demand across personal care, niche gourmet, and specialty industrial uses, supported by improved extraction technology, circular‑economy raw material flows, and growing consumer interest in natural, high‑value lipids.
Worldwide Passion Fruit Seed Oils Market
Two structural features are particularly relevant to 2026 strategic choices:
Worldwide Passion Fruit Seed Oils Market
- The market remains fragmented from a supplier concentration standpoint (our CR3 and CR5 metrics indicate limited top‑tier dominance), creating opportunities for differentiated entrants and premiumization plays.
- Upstream supply availability is tightly coupled to fruit processing by‑product streams and extraction economics; therefore, procurement strategy and processing technology selection materially affect unit economics and gross margins.
Why this report matters for 2026 corporate decisions
Companies making capex, sourcing, product portfolio or M&A decisions in 2026 need more than direction‑level forecasts — they need operationally actionable intelligence that connects market opportunity to execution risk. The report is built around that bridge:
- It quantifies market scale and growth drivers forward to 2032 while isolating the sensitivities that matter for two‑year and five‑year planning horizons.
- It decomposes value capture points across the chain — from seed sourcing through extraction, formulation and branded distribution — allowing executives to model margin improvement from vertical integration, tolling partnerships, or premium product positioning.
- It combines supplier profiling with an acquisition readiness framework: which players are likely acquisition targets, which are better suited as long‑term supply partners, and which require integration investment to meet cosmetic and pharmaceutical GMP standards.
What the report contains — practical modules you will use
The study was designed as a hands‑on toolkit for strategy teams. Key operational modules include:
- Market sizing and segmentation methodology with transparent assumptions and sensitivity runs you can adapt to your price or yield scenarios.
- Supply chain mapping, including hub‑and‑spoke sourcing options, processing bottlenecks, and logistics cost drivers for tropical origin flows.
- Extraction technology comparison (cold press, expeller, low‑temperature continuous phase techniques, solvent alternatives), with yield, quality, CAPEX/OPEX and environmental footprint tradeoffs quantified.
- Regulatory and quality checklist (REACH, ISO/ISO 16128 natural origin indexing, residual solvent expectations) that aligns procurement specs to downstream application standards.
- Competitive benchmarking and go‑to‑market playbooks for B2B bulk suppliers, ingredient houses, and finished goods brands — including channel tactics and pricing ladders for premium vs. commodity positioning.
- M&A and partnership scorecards that translate strategic fit into integration tasks and valuation sensitivities (synergies, capex to upgrade refining or certification status, customer churn risks).
Competitive landscape — who matters and why
The supplier ecosystem combines ingredient specialists, regional processors, and wholesale distributors. Our profile set focuses on firms with demonstrable supply footprints, product differentiation, and route‑to‑market in cosmetics, personal care and niche culinary segments. Highlights:
- Nature In Bottle — positions itself as an organic, cruelty‑free supplier emphasizing cold‑pressed quality and high antioxidant content. Their playbook illustrates the premium, certification‑led model where traceability and consumer‑facing credentials justify a higher price point.
- Henry Lamotte Oils GmbH — a European ingredient merchant with technical focus on fatty acid profiles and formulation applications. Their strength lies in technical application support for sunscreen, anti‑aging and emollient systems — useful for firms aiming to bridge ingredient supply and formulation services.
- Quicornac (Passola) — an industrial supplier with a long history of valorizing processing by‑products and offering variants for pharmaceutical, paint and gourmet uses. Their model is a reminder that industrial scale and multi‑vertical demand reduce revenue volatility for seed‑based oils.
- Beraca (part of Clariant/Lucas Meyer Cosmetics) — integrates raw material sourcing with a zero‑waste sustainability narrative and refined product variants tailored to cosmetic formulators seeking mattifying, low‑shine emollients. Their recent product datasheet update underscores ongoing investment in sustainability narratives that translate into formulation differentiation.
- Jedwards International and From Nature With Love (Praan Naturals) — bulk and wholesale suppliers that emphasize virgin/organic credentials and cold‑press or expeller techniques. These vendors represent flexible short‑lead supply options for brands scaling seasonal launches or cultivar‑specific promotions.
Recent supplier activity further sharpens the competitive picture. In December 2025, a leading bulk supplier refreshed its product listings to highlight antioxidant and essential fatty acid claims — a signal that suppliers are optimizing commercial messaging to end‑market formulators. In February 2026, an established Brazilian integrator updated its refined oil datasheet to emphasize seed valorization and supply chain zero‑waste commitments — a clear move toward sustainability‑driven product differentiation that impacts procurement criteria for global brands.
Supply, extraction and raw‑material dynamics to monitor in 2026
Three upstream realities will determine near‑term cost and availability:
- Seed availability is tightly coupled to juice and pulp processing volumes. Passion fruit seed oil remains largely a by‑product valorization play; strategies that secure processing partnerships or captive seed collection tend to unlock advantaged feedstock pricing.
- Extraction method is a quality and margin lever. Recent studies indicate that low‑temperature continuous phase methods can yield oils with higher unsaturated fatty acid levels (reported at roughly mid‑80s percent unsaturated in the literature), which correlates with premium positioning in cosmetics. However, these methods require different CAPEX and OPEX profiles than traditional solvent extraction.
- Raw fruit pricing and spot volatility matter for short‑term procurement. For example, passion fruit traded at approximately USD 3,367 per metric ton in the United States in Q1 2025 — a datapoint to include in scenario models when stress‑testing margin resilience under price shocks.
Regulatory, sustainability and quality levers
Regulatory alignment and certified natural credentials are non‑negotiable for many buyers. Passion fruit seed oil suppliers are increasingly ensuring compliance with REACH and meeting ISO 16128 natural origin indexing criteria within certified organic supply lines. For manufacturers targeting cosmetic, pharmaceutical or ingestible applications, residual solvent absence, traceability and batch‑level documentation are critical gating items. Sustainability claims — particularly zero‑waste valorization of processing seeds — are proving to be effective market differentiators when validated by traceable chain‑of‑custody and third‑party certifications.
Strategic playbook — recommended priorities for 2026
Based on the market trajectory and supplier landscape, PW Consulting recommends that companies prioritize three actions this year:
- Secure feedstock optionality via dual‑sourcing and processing tie‑ups. Given the by‑product nature of the seed supply, securing offtake or tolling relationships with juice processors materially reduces supply risk and cost volatility.
- Invest selectively in extraction technology or partnership arrangements that lift oil quality. For firms targeting premium cosmetic channels, the incremental margin from higher unsaturated fatty acid content and improved antioxidant retention can justify CAPEX or premium payable to toll processors.
- Formalize sustainability and regulatory credentials as commercial assets. Zero‑waste narratives and third‑party certifications are not just compliance items — they directly affect formulation adoption by blue‑chip brands and influence pricing power in B2B sales.
How strategic teams should use this report in 2026
Strategic planning teams will find the report useful for scenario planning, vendor selection, and M&A underwriting. Tactically:
- Procurement should use the supply chain module to build stochastic price and availability models for negotiations and safety‑stock calculations.
- R&D and product teams should reference the extraction technology and fatty acid analysis sections when designing formulations where tactile feel, spreadability and oxidative stability are differentiators.
- Corporate development teams should leverage the competitive and valuation matrices to prioritize targets or JV structures, aligning synergies to integration costs and certification timelines.
Concluding perspective — where to focus in 2026
Passion fruit seed oils sit at the intersection of ingredient premiumization, sustainability valorization and specialty lipid demand. The market’s projected CAGR through the forecast period signals a compelling growth runway, but the opportunity is unevenly distributed: value accrues to actors that can combine secured feedstock, superior extraction/value‑add and validated sustainability/regulatory credentials.
PW Consulting’s full report translates these strategic imperatives into executable plans, valuation models, supplier shortlists and tactical checklists. For executives and teams preparing budgets, negotiating supply agreements, or evaluating M&A in 2026, the report functions as both a map and an operations manual — revealing when to move, with whom, and on what terms.
Access the full intelligence
This press briefing is a strategic teaser designed to outline the report’s value and directional findings while preserving the granular segment and pricing detail included in the full study. For the complete dataset, supplier scorecards, downloadable templates and scenario modelling tools that support immediate decision execution, please consult PW Consulting’s full "Worldwide Passion Fruit Seed Oils Market" report and accompanying client dashboards.
For detailed analysis of this topic, please visit the official page: Worldwide Passion Fruit Seed Oils Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Culinary Tourism Market Set to Surge at 16.52% CAGR, Redefining Global Travel Experiences
By pmarketresearch, 2026-07-13
Worldwide Culinary Tourism Market — Strategic Outlook for 2026
PW Consulting — Executive Brief
The global culinary tourism market is in the middle of a decisive growth phase. Our latest market model shows the sector expanding from a 2025 base year value of USD 1,375,500 (Million) and, under current structural trends, compounding at an estimated 16.52% CAGR through the forecast window. By 2032 the market is projected to exceed USD 4,011,103 (Million). For executives planning 2026 initiatives, these headline dynamics are not an abstract trendline: they define the commercial envelope within which product design, channel investments, partnership strategies and M&A decisions must be made.
Worldwide Culinary Tourism Market
Why 2026 Is a Strategic Inflection Point
Three converging forces make 2026 a year for decisive action. First, consumer demand for food-led experiences has shifted from niche to mainstream: independent studies indicate a majority of travelers (well over half) participate in food experiences when traveling. Second, preferences show food and beverage considerations are now a primary factor for destination choice for an overwhelming share of travelers. Third, the market’s growth trajectory and the persistent fragmentation of providers create windows for scale plays, platform aggregation and premium-brand differentiation.
Worldwide Culinary Tourism Market
At the same time, structural frictions remain: cost sensitivity reduces participation for a sizeable minority of prospective culinary travellers, and seasonality continues to depress utilisation for a third of activity types. These frictions create both threats (demand volatility, constrained willingness-to-pay) and opportunities (repackaging, domestic market penetration, and dynamic pricing).
Worldwide Culinary Tourism Market
What our report delivers — practical, investable outputs
- Actionable 2026 Go‑to‑Market playbooks for operators, DMOs and investors that translate macro demand into three profitability pathways: scale aggregation, premium bespoke experiences, and high-frequency domestic products.
- Channel optimisation frameworks that prioritize spend across online travel agencies, direct channels and traditional intermediaries based on conversion economics and lifetime value modelling.
- Product innovation blueprints including plant‑forward and inclusive menu design, hybrid in-person/digital masterclasses, and festival-to-retailer extensions that increase per-guest revenue and reduce seasonality exposure.
- Partnership and public‑sector engagement templates — for tourism boards and private operators — mapping successful collaboration models from market pilots and recent destination initiatives.
- A risk matrix and mitigation playbook addressing seasonality, cost barriers, regulatory constraints, and authenticity/ESG credibility risks, with quantifiable KPIs to monitor execution.
- Transaction support tools for acquirers and investors: valuation priors, consolidation scenarios and integration checklists tailored to a highly fragmented competitive field.
Competitive Landscape — patterns and strategic implications
The competitive map is a mosaic of specialist independents, boutique experiential operators, and global tour brands that embed culinary programming into larger itineraries. Notable players illustrate four repeatable models:
- Local-expert, scale-first operators (e.g., Secret Food Tours): broad city coverage via standardized small‑group walking experiences that scale through local freelance guides and a repeatable product chassis.
- Boutique immersive specialists (e.g., Culinary Backstreets, The International Kitchen, International Culinary Tours): multi-day, high-touch itineraries that trade on authenticity and deep local networks.
- Incumbent global tour brands (e.g., Collette, Trafalgar): integrate culinary experiences into mass-market packages, leveraging distribution breadth and cross-selling to established customer bases.
- Luxury bespoke designers (e.g., Jacada Travel): high-margin, highly personalised culinary and wine programs targeted at affluent travellers seeking exclusivity.
These archetypes coexist because the market is highly fragmented. Our concentration analysis yields a low three- and five-firm concentration ratio, underscoring that most value remains with small and medium operators rather than a few large incumbents. For 2026 strategy, this implies two clear timelines for action:
- Near term (12–18 months): non‑scale players should pursue channel optimisation, targeted partnerships with DMOs, and product tiering to capture domestic and shoulder‑season demand.
- Medium term (18–36 months): scale players and financial sponsors should prepare acquisition playbooks focused on bolt-on consolidation in key cities and platform technology to capture distribution economics.
Signals from recent developments — reading the tea leaves
Recent product launches and destination initiatives provide practical signals about where competitive advantage will be created in 2026:
- Product innovation (plant-based premium experiences): a launch of a fully plant-based omakase concept demonstrates how heritage formats can be reimagined to capture specialty demand segments and dietary trends without sacrificing perceived authenticity.
- Destination-led programming: national and regional tourism initiatives (from flagship gastronomy programs to locally curated food weeks) highlight public sector willingness to co-invest in culinary placemaking — a lever operators should use for marketing, logistics and capacity building.
- Festival proliferation: new and expanded food festivals continue to act as demand multipliers, enabling retailers, farms and small operators to co-create scale around concentrated calendar events and diversify revenue beyond per-experience tickets.
Together these signals indicate where to allocate R&D and partnership capital: product formats that modularise authenticity (allowing local operator participation at scale), public-private delivery models that underwrite destination marketing, and calendar optimisation to create year‑round demand curves.
Priority 2026 playbook — six tactical moves
- Product modularisation: design experience templates that can be localised quickly — core scripts, sourcing specifications, standardised safety & service protocols — to enable rapid expansion with local partners.
- Channel rebalancing: invest in direct-booking funnel efficiencies (CRM, loyalty, dynamic packaging) while keeping a calibrated OTA and traditional agent mix to capture discovery and group business.
- Partnership economics: negotiate shared-risk marketing arrangements with DMOs and festival organisers, and co-create bundled city passes or micro‑itineraries that increase length of stay and ancillary spend.
- Price architecture & yield management: apply seasonal pricing, subscription passes for domestic repeaters, and bundled multi-venue tickets to mitigate low-utilisation months and convert price-sensitive audiences.
- Data & digital enablement: implement basic telemetry (guest profiles, dietary preferences, NPS) to personalise offers and drive incremental spend; for scale, plan for single-platform booking to aggregate city-level inventory.
- Authenticity & ESG safeguards: codify sourcing transparency, host-community revenue shares and carbon-aware logistics as minimum entry requirements for premium positioning.
Risks to monitor
Executives must treat three non-obvious risks as scenario triggers in 2026 planning cycles:
- Widening consumer price sensitivity — if competitor discounting escalates, margin pressure will force either scale plays or premium differentiation to maintain unit economics.
- Event concentration risk — over-reliance on festival windows or a single destination marketing campaign can create lumpy revenues and operational backlogs.
- Authenticity credence failure — as operators scale, perceptions of “manufactured” experiences can erode willingness to pay; preserving local curation and transparent supply chains is vital.
How boards, investors and operators should use this intelligence in 2026
For boards: treat culinary tourism initiatives as an integrated product-market timing decision. Approve a three-year roadmap that aligns capital deployment with channel maturity milestones and a prioritized set of markets and experience archetypes.
For investors: the sector offers consolidation arbitrage and recurring-revenue productisation opportunities. Execute diligence with a focus on unit economics by channel, partner dependency, and the veracity of claimed local supplier networks.
For operators: the immediate actions are operational. Standardise core delivery, lock in mutually beneficial DMO partnerships, and invest in direct booking and CRM capabilities that convert visitors into repeat domestic guests.
Access full intelligence
This briefing highlights the strategic value of our Worldwide Culinary Tourism Market report for 2026 decision-making. The full report includes granular segmentation, regional breakdowns, activity-type forecasts, booking-channel economics, supplier-level profiles and proprietary scenario models that support detailed budgeting, M&A valuation and route-to-market planning. To maintain the integrity of our data-driven recommendations while preserving a concise strategic narrative here, we’ve intentionally withheld the detailed segment matrices and company-specific revenue estimates — they are available in the full report and subscriber portal.
For immediate assistance in translating these findings into a bespoke 90‑day action plan for your organisation, PW Consulting’s sector team is available for strategy workshops and transaction advisory. Contact details and the full dataset can be accessed on the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Culinary Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Antarctic Krill (Euphausia superba) Market Hits USD 846.2 Million in 2025, Forecast to Grow at a 7.7% CAGR Through 2032
By pmarketresearch, 2026-07-13
Worldwide Antarctic Krills (Euphausia superba) Market — Strategic Outlook for 2026
PW Consulting's latest market intelligence on Antarctic krill (Euphausia superba) frames 2026 as an inflection year for commercial players, investors, and policy-makers. The industry that delivered global revenues approaching USD 846 million in our base year (2025) is projected to continue its steady expansion—driven by nutritional science, aquaculture demand, and supply-side consolidation—at a compound annual growth rate (CAGR) of approximately 7.7% across our 2026–2032 forecast window. By 2032, the market is modeled to exceed USD 1.4 billion under our central case, with downside and upside scenarios reflecting regulatory, operational, and demand shocks.
Worldwide Antarctic Krills (Euphausia superba) Market
Why this report matters to decisions you will make in 2026
- Actionable horizon: Our analysis converts macro momentum into executable 6–24 month playbooks for procurement, product innovation, M&A screening, and sustainability verification.
- Risk-calibrated opportunity: We quantify how plausible shifts in catch management, fleet availability, and certification standards propagate through prices, margins, and supply security—enabling defensible sourcing allocations and contingency planning.
- Competitive clarity without exposure: The report packages high-resolution competitor profiles, capability maps, and commercial signals—but follows a “trailer” approach here: the most granular segment shares and dollar allocations are reserved for subscribers to preserve competitive value.
Market trajectory: what the headline numbers tell us
The krill market has expanded markedly from a mid-single-hundred million-dollar base in the early 2020s to roughly USD 846 million in 2025 (base year for this study). Our central forecast anticipates continuation of that trajectory, with the sector crossing the USD 1 billion threshold in the late 20200s and approaching an overall market size above USD 1.4 billion by 2032 under current trends. This growth is not uniform: it is concentrated where nutritional science, formulation technologies, and aquafeed demand converge—creating differentiated margin pools for suppliers with integrated processing and stable raw-material access.
Worldwide Antarctic Krills (Euphausia superba) Market
Supply-side dynamics and regulatory inflection points
- Management regime and catch capacity: The Antarctic krill fishery continues to be managed under CCAMLR’s precautionary framework, reinforced by real-time monitoring and industry self-governance through ARK (Association of Responsible Krill Harvesting Companies). Annual operational catch limits remain a critical exogenous variable; the formal operational limit in Area 48 provides an upper bound for commercial activity, while spatial management evolutions (notably the expiration of certain subarea restrictions in 2025) recalibrate where vessels can operate. These governance shifts materially affect accessible biomass and therefore near-term supply dynamics.
- Observed extraction levels: Industry catch reports show that the fishery has not been exploited to its formal ceiling in recent seasons, leaving room for fleet-scale adjustments and new entrants—subject to certification, monitoring, and political constraints.
- Concentration and resilience: The market displays measurable concentration at the top: our concentration metrics indicate that the leading firms command a majority share of industry throughput, with the top five firms encompassing an even larger proportion of capacity. This creates both stability (predictable supply lanes) and strategic risk (single-firm operational disruptions can ripple through end markets).
Industry structure and competitive positioning
Our company-level diligence highlights a bifurcated landscape: a set of vertically integrated specialists that harvest, process, and market branded krill ingredients; and a cohort of processors and regional operators focused on commodity ingredients and B2B supply. Key structural themes that inform 2026 decisions include:
Worldwide Antarctic Krills (Euphausia superba) Market
- Vertical integration as a competitive moat: Firms with fleet assets, in-house processing, and direct-to-consumer channels are better positioned to capture value throughout the chain and to enforce traceability and sustainability claims—attributes increasingly demanded by buyers and regulators.
- Certification and science-driven differentiation: Marine Stewardship Council (MSC) and similar endorsements remain table stakes for premium positioning in North America, Europe, and parts of Asia. Producers that pair certification with peer-reviewed evidence of bioavailability and clinical endpoints unlock price premiums in supplements and pharmaceuticals.
- Recent strategic moves: Leading harvesters have accelerated fleet investments, circular packaging partnerships, and R&D into ingredient stability and formulation—signals that the incumbents are both defending market share and expanding addressable use-cases.
Technology and product trends shaping 2026 choices
Two technological arcs deserve upfront attention for their direct commercial implications in 2026:
- Encapsulation and oxidative stability: Advances in microencapsulation, nitrogen-flushing packaging, and UV-opaque containers materially extend shelf life and protect omega-rich profiles from oxidation. For formulators and brand owners, these technologies lower product returns, enable broader distribution, and expand co-packaging options for multi-ingredient SKUs.
- Downstream product diversification: Krill-derived hydrolysates, protein fractions, and microencapsulated oils are migrating from niche supplements into aquafeed, pet nutrition, and selected food applications. Companies that can validate functional benefits for aquaculture growth performance or pet health stand to disrupt existing ingredient mixes and capture higher-volume offtake.
Regulatory, sustainability and reputational vectors
Regulatory stewardship and sustainability verification are no longer optional. CCAMLR oversight, ARK’s real-time reporting, and cross-border certification regimes create both compliance obligations and market access gates. Buyers with ESG mandates are increasingly incorporating supplier audits, chain-of-custody verification, and third-party certifications into procurement criteria. For corporate strategists, this translates into three priority actions:
- Embed certification checks into procurement KPIs and contract terms.
- Prioritise suppliers with demonstrable science programs and traceability systems.
- Invest in upstream partnerships (including minority equity and offtake agreements) with certified harvesters to lock in supply and share the sustainability narrative.
Strategic implications and recommended 2026 moves
For corporate executives and investors, our research translates into a short list of pragmatic strategies to be executed in 2026. Each item is tied to measurable decision criteria and expected business outcomes outlined in the full report.
- Secure diversified, certification-backed supply: Negotiate staggered multi-year supply agreements with certified harvesters and processors to reduce volatility. Include audit clauses, escalation thresholds, and capacity release options to manage unforeseen fleet disruptions.
- Prioritise integration of formulation technologies: Fund or partner on encapsulation and oxidative-stability tech to reduce dependence on cold-chain logistics and expand retail channels—especially in regions where ambient storage is common.
- Assess M&A selectively for capability gaps: Target bolt-on acquisitions or strategic alliances focused on processing capacity, R&D in hydrolysates, or regional off-take networks. Use stress-tested supply scenarios from our model to size earn-outs and covenant structures.
- Activate sustainability as a commercial lever: Convert MSC, Friend of the Sea, and ARK-aligned credentials into premium positioning through verified traceability claims and science-backed health messaging.
- Run combinatorial scenario planning: Model simultaneous shocks (e.g., fleet outage + regulatory tightening) to size cash buffers and alternate sourcing routes. Our scenario suite quantifies the profit and volume implications across a range of plausible outcomes.
What is included in the full PW Consulting report
The complete study provides a practical toolkit for 2026 decision-making, including:
- Detailed market sizing and bottom-up demand models for 2020–2032, with base year 2025 and scenario variants for regulatory and operational shocks.
- Proprietary supply-demand balances and price-sensitivity analyses calibrated to CCAMLR catch trajectories and fleet capacity plans.
- Comprehensive competitor dossiers, capability matrices, and a proprietary concentration assessment that supports supplier risk scoring and M&A screening.
- Operational playbooks: contracting templates, traceability checklists, and formulation technology requirements for product development teams.
- Investment decision frameworks and a shortlist of high-conviction strategic moves tailored to different corporate objectives (premium-brand growth, ingredient commoditisation, vertical integration).
Concluding perspective
Antarctic krill has moved from an emerging specialty ingredient to a scaling global market with distinct pockets of premium value. The 2026 decision window favors organisations that: (a) lock in sustainable, certified supply; (b) invest selectively in formulation and stability capabilities to access broader channels; and (c) apply scenario-based capital allocation to navigate a market characterised by concentrated supply and evolving governance. Our central forecast—mid single-digit to high single-digit annual growth resulting in a market exceeding USD 1.4 billion by 2032—captures this transition. The full PW Consulting report operationalises these insights into executable steps and quantitative tables that stakeholders will need to negotiate 2026 effectively.
Next steps
For executives preparing sourcing plans, innovation roadmaps, or transaction pipelines in 2026, the full report contains the financial templates, supplier scorecards, and regional demand matrices that you will require. Visit our report page to access the complete dataset, downloadable models, and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Antarctic Krills (Euphausia superba) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Porcelain Enamel Market Reaches USD 2,030 Million in 2025 — Poised for Further Growth into 2026–2032
By pmarketresearch, 2026-07-13
Worldwide Porcelain Enamel Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s forthcoming Worldwide Porcelain Enamel Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) frames an actionable commercial roadmap for executives planning capital allocation, product roadmaps, and supply‑chain redesign through 2026 and beyond. The market reached approximately USD 2,030 Million in 2025 and is forecast to expand at a steady compound annual growth rate (CAGR) of 4.12% across the 2026–2032 horizon, reaching an estimated USD 2,693 Million by 2032. This preview highlights the strategic implications of those trends, synthesizes competitive movements and regulatory headwinds, and outlines the tactical priorities companies should consider as they set budgets and M&A agendas for 2026. For full segment-level tables, granular regional and application shares, and transaction‑level valuation detail, see the full report at the PW Consulting portal.
Worldwide Porcelain Enamel Market
Why this report matters for 2026 planning
-
Decision timing — Porcelain enamel is capital‑intensive and energy‑dependent; capacity investments and line upgrades typically require 12–24 months lead time. The 2026 planning cycle is therefore the pivot point to operationalize insights from 2025 outcomes and to secure supply and talent before cost or regulatory compression materializes.
Worldwide Porcelain Enamel Market -
Profitability levers — Margins in enamel value chains are increasingly tied to formulation innovation (lead‑free, nickel‑free, low‑quartz), energy utilization in firing, and vertical coupling with substrate providers. The report isolates which levers deliver the fastest payback across common business models.
Worldwide Porcelain Enamel Market -
Risk mitigation — Suppliers face volatile feedstock pricing and tightening compliance regimes; the analysis prioritizes hedging and sourcing strategies that reduce exposure while preserving product performance specifications.
Market trajectory and inflection points
Historical data from 2020–2025 shows a market that absorbed pandemic distortion and rebalanced around appliance replacement cycles, construction activity, and industrial refurbishment projects. The 2026–2032 forecast reflects a return to secular demand for durable, corrosion‑resistant enamel solutions across appliances, water heating, cookware, sanitaryware and architectural uses, balanced by efficiency gains and the gradual introduction of higher‑performance premium formulations.
Key inflection drivers identified in the report include regulatory compliance demands in potable water applications, the push to low‑hazard food‑contact enamels, and targeted product innovation that emphasizes heat‑resistance and colour stability. We expect steady expansion rather than explosive growth, with opportunities concentrated in higher‑margin specialty coatings and service‑enabled enamelling.
Cost, supply‑chain and raw material dynamics
-
Feedstock sensitivity — Primary raw materials such as silica (reported Q4 2025 U.S. price roughly USD 53/MT), borates and feldspars remain the dominant input cost drivers. Price volatility in these commodities, combined with the energy intensity of high‑temperature firing, constrains margin expansion unless offset by formulation or process innovation.
-
Energy and process efficiency — Firing kilns and coating lines are significant energy consumers. The report quantifies energy cost contribution to finished enamel pricing and identifies retrofit and process control investments with 2–5 year paybacks under typical regional electricity and gas tariffs.
-
Vertical integration tradeoffs — Players that combine frit manufacture with enamelling services or tie into appliance producer supply chains can realize scale and quality advantages, but must manage capital intensity and operational complexity.
Regulatory landscape and standards impact
Regulatory requirements are an increasingly active determinant of product strategy. European potable water directives and food‑contact standards (e.g., directives and standards comparable to DIN 4753‑3 and ISO 4531) are accelerating demand for nickel‑ and lead‑free enamels and for formulations with controlled quartz content. Conversely, select regional exemptions and legislative nuances—such as the 2025 Minnesota HF‑4 adjustments—create short‑term windows for legacy product lines in some jurisdictions.
For 2026 planning, the critical implication is that compliance‑driven product reengineering is not optional for companies seeking to sell into regulated appliance or potable water markets. The report includes a regulatory matrix that ranks geographies by adoption timelines and compliance cost impact to support prioritization of certification and reformulation spends.
Competitive landscape — who matters and why
The industry shows a moderate level of concentration: top‑3 players account for roughly 38% of market share, while the top‑5 reach about 52%—indicative of strong national champions alongside a fragmented long tail of regional specialists and service providers. Our competitive profiles emphasize capabilities, channel positions, and strategic intent rather than only static share figures, enabling executives to map alliance and acquisition targets against capability gaps.
-
Vibrantz Technologies (incorporating Ferro and Prince Minerals) — A global leader with broad formulation capabilities across powder, paste and ready‑to‑use frits. Vibrantz’s recent product launches (heat‑resistant coatings for industrial ovens and cooktops, April 2025) and an innovation award in 2025 underscore its R&D momentum. Expect continued investment in engineered colourants and performance enamels.
-
A.O. Smith Corporation — A major integrated user and producer, especially in water‑heating systems. A.O. Smith represents the archetype of a downstream OEM that controls portions of the enamelling chain to secure performance and regulatory compliance for potable applications.
-
Regional specialists and service providers — Firms such as AkCoat, Tomatec, Hunan Noli (Nolifrit), Keskin Kimya, Cherokee Porcelain Enamel, Capron, Bootz Industries, Al‑Khudair, Independence Porcelain Enamel and Lovink Technocast play critical roles supplying niche formulations, enamelling services, or finished enameled components. These players often compete on turnaround, customization and local certifications.
-
M&A and capacity moves — Mergers and acquisitions continue to reshape supply footprints: notable activity includes CMF Group’s acquisition of a porcelain enamel frit division (2025) and multi‑year supply contracts awarded to regional producers (e.g., Hindusthan National Glass & Industries contract in 2025), which collectively indicate selective consolidation and capacity rationalization in strategic corridors.
Strategic implications — five actions for 2026
-
Prioritize compliance‑led product investment: Fast‑track low‑hazard, nickel‑free and low‑quartz reformulations for potable and food‑contact endpoints to avoid losing access to premium channels.
-
Invest in thermal efficiency and process controls: Target kiln and line upgrades that reduce energy intensity and improve yield — these projects generally pay back under typical 2026 cost assumptions and protect margins against feedstock cycles.
-
Hedge raw material and logistics exposure: Implement multi‑sourcing and structured purchase contracts for silica and borates; consider strategic inventory buffering where economically justified.
-
Pursue targeted M&A or partnerships: Seek bolt‑on acquisitions that add specialty frits, local certification capabilities, or enamelling services to reduce customer friction and shorten lead times.
-
Differentiate through service and lifecycle economics: Build commercial models that emphasize total cost of ownership (durability, energy savings, lifecycle recovers) for appliance OEMs and specifiers, rather than competing solely on unit price.
What the full PW Consulting report contains (operational highlights)
-
Detailed annual market sizing (2020–2032) and scenario-based forecasts, with sensitivity analysis around energy and raw material prices.
-
Granular segmentation by region, product family and end‑use application, alongside demand‑pull narratives for each channel. (Note: granular segment tables are included only in the full report.)
-
Comprehensive competitive profiles and capability maps, including technical competencies, plant footprints, and partnership pipelines.
-
Cost stacks and margin waterfall diagnostics for representative product lines, with suggested levers to capture margin uplift.
-
Regulatory matrix covering potable water, food contact and hazardous substance controls, plus certification timelines to guide product rollout sequencing.
-
M&A playbook and valuation benchmarks, focused on frit manufacturers, enamelling service providers and integrated OEMs.
-
Primary research appendices (supplier interviews, buyer surveys) and a reproducible methodology section for financial modelling and forecasting assumptions.
Concluding perspective
For 2026, executives in porcelain enamel value chains face a choice: implement defensive measures now (compliance reengineering, energy retrofits, hedging) and accept incremental returns, or invest in differentiated, high‑performance formulations and service offerings that can capture premium end markets. Our analysis shows the market is growing at a measured pace (CAGR ~4.12% to 2032) with meaningful pockets of higher margin opportunity tied to product innovation and regulatory compliance. Moderate industry concentration leaves room for focused scale plays and targeted acquisitions, while regional specialists will continue to command value where agility and certification matter.
PW Consulting has structured the full report to support that strategic decision process — providing the granular, actionable intelligence necessary to convert 2026 planning into funded projects and executable timelines. For the complete dataset, segmented tables, proprietary vendor scorecards and the downloadable executive playbook, visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Porcelain Enamel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PLA Biodegradable Stretch Film Market to Grow at 12.99% CAGR, Reaching USD 1,799.75 Million by 2032
By pmarketresearch, 2026-07-13
PLA Biodegradable Stretch Film Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
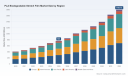
PW Consulting’s latest market study on the PLA biodegradable stretch film market delivers a focused, decision-ready view for leadership teams preparing plans in 2026. Built on a 2025 base year (with historical coverage from 2020–2025 and forecast through 2026–2032), the report quantifies a market that has roughly doubled in scale since 2020 and is poised to continue rapid expansion. Our modeling shows total market revenue rising from USD 765.0 Million in 2025 to USD 1,799.75 Million by 2032, representing a compounded expansion trajectory consistent with a 12.99% CAGR across the forecast window.
PLA Biodegradable Stretch Film Market
Why this matters now
-
Timing: 2026 is the inflection year for many procurement and innovation programs. Regulatory momentum, buyer preference shifts, and improving PLA supply economics are converging to make commercial launches and scale-ups materially more attractive this year.
PLA Biodegradable Stretch Film Market -
Margin and sourcing pressure: Raw-material dynamics and regional cost divergence are already affecting supplier selection and margin expectations. Our price and feedstock analysis highlights a narrow but meaningful band of PLA cost structures across primary markets, and a lactic-acid and PLA industry that expanded in value between 2025 and 2026 — a factor buyers and CFOs must model into 2026 budgets.
PLA Biodegradable Stretch Film Market -
Commercial differentiation: Brand owners and logistics operators face accelerating demands for credible compostable alternatives to conventional stretch film. Firms that lock in validated suppliers, performance-tested formulations, and compliant certification frameworks in 2026 will hold a decisive advantage in RFPs and sustainability reporting cycles in 2027–2028.
What PW Consulting’s report delivers — practical, executable intelligence
The report is structured to give immediate, operational lift to strategy, procurement, product, and M&A teams. Key deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario layers that stress-test demand under conservative, base, and accelerated adoption paths.
-
Driver and restraint maps tying policy, circular-economy infrastructure, and feedstock economics to short- and medium-term adoption curves.
-
Supply-chain and cost models: landed-cost templates, supplier scorecards, sourcing playbooks, and a raw-material sensitivity matrix that quantifies EBITDA exposure to PLA price moves.
-
Regulatory and compliance roadmaps that translate EU directives, national single-use plastics restrictions, and export-compliance expectations into actionable checklists for product development and labeling.
-
Procurement negotiation kits and pilot-to-scale implementation guides, including sample technical acceptance criteria, testing protocols, and consumer-claims guardrails for compostability certifications.
-
Competitive landscape analysis and M&A playbooks that prioritize targets by technological fit, manufacturing footprint, and capability to deliver PLA/PBAT blends at scale.
-
Risk register and mitigation playbooks covering feedstock fluctuation, certification misalignment, composting infrastructure gaps, and substitution threats from other bio-based resins.
Competitive landscape: who’s shaping the market and how
The market exhibits a moderate concentration profile: the top three suppliers command a significant niche presence while the top five broaden that influence. This structure creates a dual-speed market — established players able to supply global programs, and nimble regional specialists that drive innovation in formulations and localized service models.
-
YITOPACK (Huizhou Yito Packaging Co., Ltd.) — A leading Chinese OEM focusing on PLA and PLA/PBAT blends for pallet wrapping. Strengths include scale manufacturing for industrial logistics applications and the capacity to provide customizable thicknesses and specifications tailored to customer handling systems.
-
RTG Films — US-based converter specializing in compostable PLA films with clear grades suitable for sustainable stretch and packaging. Their market positioning is built on conversion expertise and integration with North American supply chains.
-
BUHE Technology Ltd — Chinese producer emphasizing PLA + PBAT blends positioned as compostable alternatives without microplastic risk. Their go-to-market focus is industrial pallet wrapping where compostability claims must be defensible.
-
Hongren Packing — A China-based supplier with a certification-led proposition (OK Compost, EN13432, BPI). They serve customers requiring documented end-of-life performance and export-ready certification packs.
-
Torise Biomaterials — Specializes in tailored PLA/PBAT films with engineering emphasis on clarity, strength, and consistency — attractive to brand owners seeking parity with conventional film performance.
-
Taghleef Industries — A global player offering biodegradable BoPLA films (Nativia® line). Their international production footprint and product breadth make them a logical partner for multi-region rollouts.
-
Shanghai Yifu Packaging, Chintec, Hubei HYF, Easy Flux — Regional manufacturers driving localized innovation, speed-to-market, and competitive pricing. Collectively they serve fast-moving segments including food, retail, and domestic logistics.
Raw materials and regulatory context
PLA production remains anchored in renewable feedstocks, principally corn-derived starch, which continues to represent the majority route-to-market for PLA monomers. The upstream lactic-acid and PLA value chain expanded meaningfully between 2025 and 2026, reflecting both capacity additions and higher commercial uptake. PLA feedstock costs vary by market; in early 2026 we observed a meaningful band of regional price differentials that suppliers and buyers must account for when comparing landed costs and negotiating multi-territory contracts.
On the regulatory front, Europe’s sustained restrictions on single-use plastics and a mosaic of more than 70 national-level bans are accelerating adoption of PLA-based alternatives for packaging. Complementary policy drivers in China (industrial-park biodegradable packaging programs and export-aligned compliance) are encouraging PLA-PBAT hybrids as practical industrial solutions. These policy forces make 2026 a critical year for firms to align technical specifications with credible end-of-life claims and to secure supply certainty ahead of tightened compliance windows.
Scenarios and risks that should shape your 2026 roadmap
-
Price volatility: PLA feedstock swings will influence commercial thresholds for replacing conventional PE-based stretch films. Hedged purchasing and multi-supplier strategies are prudent.
-
Certification vs. infrastructure mismatch: Compostability claims are only as valuable as the composting infrastructure to process them. Market winners will couple claims with downstream processing partnerships or take-back pilots.
-
Performance trade-offs: PLA/PBAT blends bridge the mechanical gaps versus conventional film, but technical benchmarking against customer handling systems remains essential to avoid claim-based recalls or uplift costs.
-
Supply concentration: With a moderate top-tier concentration in the vendor pool, single-source exposures can create lead-time and pricing risk for large-scale rollouts.
Priority moves for 2026 — a tactical checklist
-
Procurement: Implement a two-tier sourcing strategy (global preferred suppliers + regional fast-fail converters) and model landed cost scenarios against PLA price-band sensitivities.
-
Product development: Prioritize PLA/PBAT formulations for pallet-wrap applications that meet minimum durability thresholds; embed certification and on-package guidance from the outset.
-
Commercial pilots: Launch targeted logistics pilots with tier-1 carriers and distribution centers where composting or industrial processing can be documented.
-
M&A and partnerships: Screen acquisition targets that provide either capacity to scale or specialized formulation IP that shortens time-to-market for clear, high-strength grades.
-
Regulatory readiness: Map your product claims to regional waste-processing realities and prepare labeling, chain-of-custody, and certification dossiers to support global tenders.
How PW Consulting’s report helps you execute in 2026
This publication is deliberately tactical. It equips commercial, procurement, and technical teams with the precise inputs they need to set 2026 budgets, prioritize pilots, and negotiate supplier contracts with confidence. The full report includes downloadable cost-model workbooks, supplier scorecards, test protocol templates, and an interactive scenario dashboard designed to stress-test programs against PLA price and policy shifts.
Next step
We have deliberately provided this preview to surface the strategic implications and practical actions companies must consider in 2026. The full report contains the detailed segmentation, supplier datasets, and localized market intelligence that procurement and product teams require to operationalize the recommendations shown here. Access the complete study to obtain the granular supplier profiles, regional matrices, and downloadable decision tools that will convert 2026 opportunity into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: PLA Biodegradable Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Rising Stem Ball Valve Market Poised to Expand at a 5.86% CAGR Through 2032
By pmarketresearch, 2026-07-13
Worldwide Rising Stem Ball Valve Market: Strategic Primer for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Rising Stem Ball Valve market provides a decision-grade, practice-oriented intelligence package designed to influence capital, product, and commercial strategies in 2026. Built on a 2020–2025 historical base and projecting through 2032, the report benchmarks the market using a 2025 base year and quantifies an expected mid-single-digit compound annual growth rate (CAGR) of 5.86% across the forecast window. From an addressable-market perspective, the research synthesizes firm-level positioning, supply chain risk, standards compliance, and aftermarket economics to translate macro growth into executable choices for C-suite and business unit leaders.
Worldwide Rising Stem Ball Valve Market
Why 2026 Is a Pivotal Year
-
Transition from maintenance-driven to performance-driven purchasing: Operators in severe-service industries are increasingly valuing lifecycle cost, zero-leakage assurance, and high-cycle durability over lowest initial price—creating room for differentiated product and service strategies.
Worldwide Rising Stem Ball Valve Market -
Supply chain and raw-material volatility remain central: Recent price and availability swings for carbon, stainless, and exotic alloys mean procurement and design decisions made in 2026 will materially affect margins and delivery capability across the medium term.
Worldwide Rising Stem Ball Valve Market -
Regulatory and standards convergence: Adoption of stringent specifications—especially for critical onshore and offshore oil and gas applications—continues to favour manufacturers who can demonstrate compliance with API and ASME frameworks while minimizing operational risk for end users.
-
Consolidation and competitive clustering: The market’s top tier exhibits meaningful concentration, leaving mid-market suppliers and specialists opportunities to capture niche stacks if they deploy clear technical differentiation and service models.
What the Report Contains — Practical, Executable Components
-
Market sizing and scenario forecasts: A base-year assessment with conservative, central, and upside demand scenarios through 2032, translated into revenue impacts and capacity requirements in USD (Million).
-
Demand-driver heat maps: Industry-by-industry intelligence that maps use-cases for rising stem designs (high-cycle, zero-leakage, particle-tolerant environments), including adoption velocity indicators.
-
Supply chain and raw-material stress-testing: Supplier tier maps, cost-sensitivity models, and hedging playbooks to mitigate price and lead-time risk for key alloys and components.
-
Competitive benchmarks and capability matrices: Side-by-side technical and commercial comparisons of global suppliers, with a focus on design attributes, serviceability, certification, and aftermarket revenue potential.
-
Commercial playbooks: Packaging of product, aftermarket, and field-service propositions with pricing ladders, ROI calculators for customers, and bid/no-bid decision trees for project suppliers.
-
M&A and partnership screening: A prioritised list of asset types and company profiles aligned to three different corporate strategies—scale, capability, and geographic expansion—supported by valuation sensitivity models.
-
Implementation templates: RFP and technical-specification templates, test-plan outlines, and KPI dashboards for procurement and operations teams to shorten decision cycles.
Market Dynamics and Strategic Implications
-
Performance requirements are intensifying. Rising stem ball valves are being specified more frequently where zero leakage and frequent actuation are mandatory. Mechanically energized seats and designs that reduce seal rubbing are becoming standard expectations for critical-service valves.
-
Materials selection is both a cost and reliability lever. The total cost of ownership analysis in the report shows that choices between carbon, stainless, and higher-grade alloys materially shift lifecycle economics—particularly when factoring repair frequency, down-time cost, and parts lead time.
-
Standards matter and act as market gates. Compliance with API 6D, ASME B16.34, and equivalent regional standards is not only a technical requirement but a commercial filter in supplier shortlists for major projects; manufacturers who proactively demonstrate rigorous test protocols capture specification leadership.
-
Aftermarket services are a multiplier. Field-proven designs that minimize friction and particle ingress reduce maintenance calls and enable premium aftermarket contracts; our modelling projects aftermarket attach rates as a key margin driver for suppliers who invest in service delivery.
-
Concentration creates both risk and opportunity. The market shows meaningful clustering among a small number of global players while leaving pockets of specialist demand accessible to challengers; corporate strategy should therefore balance defence in core verticals with targeted penetrations in underserved niches.
Competitive Landscape — Who’s Shaping Technology and Commercial Trends
Our competitive analysis profiles global manufacturers and identifies where technical innovations and go-to-market moves are reshaping the field. Highlights:
-
Flowserve Corporation (Irving, Texas, USA) — Emphasises mechanically energized solutions and product lines engineered to prevent leakage and contamination in oil and gas environments; a go-to name for project-spec heavy applications.
-
Orbit Valves (SLB) (Tulsa, Oklahoma, USA) — Known for tilt-and-turn designs that reduce seal rubbing and deliver reliable zero-leakage performance across multiple pressure classes.
-
Trillium Flow Technologies (Red Point) (Netherlands) — Pioneering non-contact rising stem concepts aimed at extending service life and lowering maintenance in dirty-service oil and gas applications; recently launched a weld-free, friction-reducing design that illustrates the direction of innovation.
-
DHV Industries (USA) — Focused on heavy-duty, trunnion-mounted designs and broad pressure/size coverage; recent catalogue updates reflect ongoing alignment with ASME design requirements.
-
SCV Valve, Maverick Valves, SchuF, ARFLU, ATV SpA — Each vendor brings distinct mechanical architectures (offset cams, top-entry servicing, bottom trunnions) and niche service propositions suitable for specific process scenarios.
Market concentration metrics in the report quantify that the three largest suppliers control a meaningful share of revenue, with the top five commanding a clear majority—an arrangement that reinforces opportunities for strategic partnerships, specialized differentiation, and selective M&A.
Recent Industry Moves You Should Track
-
Trillium Flow Technologies (June 2025) introduced a new non-contact rising stem valve under the Red Point brand designed for dirty-service oil and gas applications. Its weld-free, bottom-trunnion architecture addresses particle ingress and friction—features that shorten downtime and improve lifecycle cost.
-
DHV Industries (February 2025) updated product literature covering expanded ASME B16.34-compliant offerings across a wide range of sizes and pressure classes—an indication of continuing demand for certified, project-grade hardware.
-
Raw-material and regulatory dynamics remain active: price volatility for steels and alloys, plus rising specification stringency for zero-leakage performance, are shaping procurement and product strategies across the board.
Strategic Playbook for 2026 — Concrete Actions
-
Prioritise product architectures that lower lifecycle cost: Invest in designs that reduce friction and ingress (non-contact or mechanical cam systems) and validate those benefits with field trials tied to explicit outage-cost metrics.
-
Lock in materials and components through blended procurement: Combine long-term agreements for critical alloys with dual-sourcing strategies for castings and trim to reduce lead-time exposure.
-
Raise the aftermarket profile: Bundle predictive maintenance, spares agreements, and rapid-response service to convert one-off sales into high-margin annuity streams.
-
Use standards compliance as a commercial weapon: Create simplified compliance dossiers that procurement teams can drop into contract negotiations to accelerate shortlisting.
-
Pursue targeted M&A and JV moves: Look for assets that bolster capability (e.g., top-entry servicing, weld-free trunnions) rather than size alone; our valuation templates help you assess medium-term earnings accretion.
-
Embed scenario-based capital planning: Adopt the report’s stress-tested demand scenarios to size capacity additions, working capital needs, and pricing strategies for 2026–2028.
How PW Consulting Can Help
-
Decision-ready datasets and dashboards calibrated to your product and geographic footprint.
-
Risk-adjusted financial models for procurement, capex, and M&A decisions.
-
Supplier due diligence and technical validation workshops to accelerate buy-side confidence.
-
Commercial playbook execution support: RFP drafting, bid coaching, and aftermarket launch plans.
Our full report provides the granular segmentation, supplier scorecards, and downloadable models that business leaders and investors need to operationalize these recommendations. This executive primer outlines the strategic choices 2026 will demand; the complete study contains the market-detail and supporting tools you’ll reference across budgeting cycles and board decisions. For access to the full dataset, vendor matrices, and scenario models, visit the PW Consulting research page to request the comprehensive Worldwide Rising Stem Ball Valve Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Rising Stem Ball Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide White Cane Market to Expand at 5.5% CAGR—Revenue Forecasted to Reach USD 326.59 Million by 2032, Asia Pacific Leading with USD 83M
By pmarketresearch, 2026-07-13
Worldwide Blind Cane (White Cane) Market — Strategic Preview for 2026 Decisions
PW Consulting’s new market intelligence briefing frames how mobility-aid manufacturers, assistive-technology integrators, health procurement teams and impact investors should position themselves as the white cane market transitions from a mature assistive product into a hybrid category that blends mechanical design with sensing, connectivity and regulatory complexity. Our analysts forecast a continuation of steady growth — underpinned by demographic demand, product innovation and nascent smart-cane adoption — with a compound annual growth rate (CAGR) of approximately 5.5% over the 2026–2032 horizon. On a macro level, the market is projected to expand from a 2025 baseline (USD 224.5 Million) to roughly USD 245.3 Million in 2026 and to about USD 326.6 Million by 2032 (million USD, reporting in our base currency).
Worldwide Blind Cane(White Cane) Market
Why this preview matters for 2026 strategic planning
- Timing of investment and product launches: 2026 will be the inflection year when several smart-cane second-generation devices and advanced mechanical tips move from prototype/demos to broader pre-orders and limited commercial distribution. The window for securing early OEM partnerships, sensor-sourcing contracts and pilot public procurement slots is narrow; delayed moves will mean competing for smaller shares of incremental growth.
- Channel and procurement complexity: Buyers include public blindness federations, rehabilitation centers, online retail, and medical suppliers — each with different purchasing cycles, quality standards and certification expectations. In 2026 firms must align regulatory and reimbursement positioning in parallel with distribution planning.
- Technology convergence: The pairing of lightweight materials and low-power sensing/AI stacks is creating new value propositions (safety, navigation augmentation, and data-enabled services). Strategic choices now determine whether a company is a component supplier, a licensed product brand, or a platform owner of user data and services.
Market dynamics: drivers, constraints and near-term signals
Demand drivers remain familiar but are being reshaped by three concurrent trends. First, demographic growth and higher diagnosis rates in several markets sustain baseline demand for conventional canes. Second, a wave of design-led products (carbon-fiber lightweight canes, improved folding mechanisms, and novel rolling tips) is expanding use-cases — encouraging activity and adoption among younger blind and partially sighted users. Third, the emergence of smart-cane adapters and fully integrated electronic canes is creating an adjacent market for sensors, haptics, and cloud services.
Worldwide Blind Cane(White Cane) Market
Constraints that will influence 2026 outcomes include regulatory classification and reimbursement policy. National and regional rules remain a determining factor for procurement: for example, in the United States, white canes are typically classified as identifying/self-help devices and therefore fall outside routine Medicare coverage under existing NCD language. Conversely, certain walking canes can meet Durable Medical Equipment criteria when medical necessity is demonstrated, creating nuanced reimbursement pathways that specialized entrants can exploit via clinical evidence and procurement strategy. In Europe, manufacturers seeking to market advanced mobility aids must navigate medical device certification frameworks for product quality and safety — a gating item for many smart-cane players.
Worldwide Blind Cane(White Cane) Market
Technology and product evolution
- Mechanical refinement: Materials science — lighter carbon and engineered composites — continues to reduce weight while improving durability. Design improvements in tips and folding mechanisms will continue to drive user comfort and outdoor usage.
- Smart integration: Second-generation smart canes focus on reliable upper-body obstacle detection, refined voice/navigation integration, and lower false-positive rates in crowded environments. Edge AI and sensor fusion are the key value levers.
- Accessory ecosystems: Rolling tips, interchangeable heads, IoT adapters and app platforms create recurring-revenue and aftermarket opportunities. Companies that control accessory ecosystems can capture higher lifetime value from each user.
Competitive landscape — who matters and what they bring
The market remains moderately fragmented: the top three and top five suppliers do not dominate to the extent seen in many other assistive-device sectors, leaving room for regional leaders, specialty manufacturers and fast-following smart entrants. A strategic read on notable players illustrates current positioning and competitive moves:
- Ambutech Inc. (Winnipeg, Canada) — A global manufacturer with a broad physical product portfolio (rigid, folding, and composite canes) and deep distribution channels in many countries. Their scale in classic mechanical products makes them a preferred procurement partner for institutions and NGOs seeking proven, certified hardware.
- Ossenberg GmbH (Rheine, Germany) — European specialist known for product variety and engineering of ergonomic handles and adjustable systems. Strong in markets where regional standards and localized fit matter.
- whitecane. (IO White Cane, Duderstadt, Germany) — Focused on lightweight carbon solutions and medical-device compliant products. Their certification posture and ergonomic focus make them a key reference for clinical procurement and premium segments.
- WeWALK (Istanbul area) — One of the most recognizable smart-cane brands; its Smart Cane 2 (launched to market in 2025) combines upper-body sensing, AI voice assistant and navigation integration. WeWALK is a bellwether for how well users will accept and pay for integrated electronics.
- Mizuno Corporation (Japan) — Brings sports-grade composites and brand cachet to a lightweight carbon fiber cane aimed at more active users and markets that value design-led products.
- BAWA Tech (Malaysia) — Developer of IoT-enabled adapters that retrofit traditional canes, representing an attractive route for incumbents to add "smart" features without redesigning core mechanical platforms.
- Regional manufacturers and federations — Established manufacturers across Asia and institutional suppliers (including federations distributing free or subsidized canes) remain vital channels and influence standards, training and adoption.
Recent industry signals underscore the bifurcation of the market: WeWALK’s Smart Cane 2 roll-out (2025) confirms commercial appetite for integrated solutions, while product innovations such as advanced rolling tips presented at trade fairs in 2026 show mechanical refinement remains a powerful differentiator.
Actionable strategic recommendations for 2026
- Prioritize one of three strategic plays: (a) Core-mechanical excellence — double down on materials, ergonomics and low-cost manufacturing for institutional tenders; (b) Hybridization — partner with sensor/AI suppliers to offer retrofit kits or co-branded smart canes; (c) Platform play — develop a software and services layer (navigation, remote monitoring, training) to capture recurring revenue.
- Develop certification-first roadmaps: For any product entering regulated markets, align design and clinical-evidence generation with the relevant medical device certification pathways from concept stage to avoid time-to-market delays.
- Segment go-to-market by buying center: Institutional tenders require lifecycle cost models and proof of durability; consumer channels prioritize design, user experience and app ecosystems. Tailor GTM and pricing accordingly.
- Secure supply resilience: Materials (carbon fiber, engineered composites) and specialized rolling tips are bottlenecks. Build second-source agreements and evaluate nearshoring to reduce lead-time risk for 2026 launches.
- Match evidence to reimbursement levers: Where possible, generate limited clinical or usability studies that demonstrate reduced fall risk or increased mobility hours — this assists in local reimbursement arguments and institutional procurement bids.
- Make acquisition and partnership scouting disciplined: M&A targets to watch include sensor-stack developers, rolling-tip innovators, and regional distributors with institutional contracts. Use staged earn-outs tied to certification and sales milestones.
What the full PW Consulting report delivers (practical, operational content)
- Detailed market sizing and forecast models (2020–2032) with scenario sensitivity analyses — including baseline, accelerated smart-adoption and downside-demand scenarios.
- Go-to-market playbooks for producers, distributors and software-platform entrants — with tender templates, pricing levers, and channel-split considerations by buyer type.
- Regulatory and reimbursement navigators — checklists for US, EU and key APAC markets that map certification pathways, clinical evidence thresholds and procurement rules.
- Component and supplier maps — bill-of-material cost drivers, preferred sensor suppliers, and manufacturing cost curves for major materials.
- Competitive dossiers on leading companies and 20+ regional manufacturers — strategic profiles, capability matrices and deal trackers.
- Investment and M&A playbook — valuation benchmarks, integration risk checklists, and sample term structures for bolt-on acquisitions.
- Field research and user-journey case studies — behavioral insights from users across mobility-training centers and consumer pilots to guide product design and service features.
How to use this briefing to set priorities in 2026
If you are preparing a 2026 product roadmap, target a tightened launch window for either a mechanical improvement or a certified smart variant — not both. If you are a distributor or NGO, prioritize supplier relationships with certified manufacturers and specify evidence requirements in RFQs. For investors, favor companies with defensible platforms (software, accessory ecosystems) and clear pathways to certification and institutional procurement.
PW Consulting’s analysis shows that while headline growth is moderate and predictable, value capture is shifting: premiumization through materials and margins on accessories, plus recurring revenue from connected features, will drive outsized returns for firms that execute quickly and manage regulatory pathways effectively.
Next steps and access to the complete intelligence
This release is a strategic preview designed to help leaders prioritize resources for 2026. The full Worldwide Blind Cane (White Cane) Market report contains the complete data tables, region- and product-level forecasts, supplier scorecards and tender-ready appendices that operational teams need to execute. For access to the full dataset and a customized briefing from our industry practice, please visit the PW Consulting report page and schedule a consultation with our audit-ready analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Blind Cane(White Cane) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com