

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Worldwide Highlighters Market to Grow at 4.18% CAGR, Reach USD 2,466.2 Million by 2032
By pmarketresearch, 2026-07-13
Worldwide Highlighters Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategic Consultant and Chief Industry Analyst, I am pleased to introduce a concise preview of our newest market research: the Worldwide Highlighters Market (base year 2025, forecast 2026–2032). This briefing is designed as a strategic “trailer” for executives, investors, and innovation leaders who must make decisive calls in 2026. It highlights the structural dynamics, competitive vectors, regulatory inflection points, and the actionable playbook contained in the full report — while intentionally reserving detailed segment-level figures and proprietary models to drive readers to the full deliverable.
Worldwide Highlighters Market
Market Snapshot: Macro Trajectory and What It Means
After steady recovery and incremental product innovation through the early 2020s, the global highlighters market reached approximately USD 1.85 billion in 2025. Our forecast model projects a steady compound annual growth rate (CAGR) of 4.18% through 2032, bringing the market to roughly USD 2.47 billion by the end of the forecast window. This trajectory reflects a mixture of long-term demand stability in education and office channels, plus rising incremental demand in creative, journaling, and specialty applications driven by product innovation and premiumization.
Worldwide Highlighters Market
For 2026 planning cycles this macro view provides three immediate implications:
Worldwide Highlighters Market
- Growth is predictable, not explosive — enabling capacity planning and capital allocation that favor targeted investments over expansive rollouts.
- Profitability will be driven by product mix, channel economics, and formulation/packaging efficiencies rather than by sheer volume expansion.
- Sustainability and regulatory readiness are value drivers that will materially influence procurement and retail assortment decisions.
Primary Growth Drivers and Structural Headwinds
Our market model and qualitative research identify a constellation of drivers that will shape 2026 decisions.
- Product innovation and premiumization: New ink chemistries (including water-based and biodegradable pigments), dual-tip formats, and pastel palettes continue to expand use cases beyond traditional highlighting — attracting hobbyists, planners, and creative consumers.
- Sustainability and compliance: Global buyers increasingly demand formulations and packaging that meet green product certifications and stricter chemical-safety standards. Companies that can certify compliance will unlock institutional and education channel advantages.
- Omnichannel distribution dynamics: Online platforms are maturing as a discovery channel for premium and niche SKUs, while traditional stationery and supermarket channels remain critical for scale. The nuanced economics of each channel will determine promotional cadence and SKU rationalization in 2026.
- Supply-chain and tariff considerations: Customs classifications and duty regimes create friction for manufacturers who rely on global sourcing. Procurement teams must factor total landed cost and compliance into sourcing decisions.
Countervailing headwinds include episodic regulatory actions and product-safety incidents that can produce reputational and recall costs, and the slow but steady commoditization pressure in mainstream SKUs that compresses margins.
Regulatory and Raw-Material Environment — A 2026 Playbook
Regulatory noise has crystallized into a real operational consideration. Recent recalls related to banned phthalates and the ongoing push to greener formulations have pushed major manufacturers to reformulate and repackage. In response, we recommend three immediate actions for 2026:
- Implement a regulatory-monitoring cell that maps formulations to jurisdictional restrictions and certification pathways to preempt recalls and maximize access to public and institutional tenders.
- Prioritize R&D investments into water-based and biodegradable pigments to reduce future reformulation costs and to create marketing differentiation tied to environmental claims.
- Quantify supplier risk using a total-cost-of-ownership (TCO) framework that includes tariff exposure, testing timelines, and certification costs.
These measures will be core components of the operational playbooks we provide in the full report.
Competitive Landscape — Strategic Positions of Leading Manufacturers
The competitive field blends global CPG incumbents, heritage writing-instrument houses, and specialty brands targeting niche segments. The market is neither a pure commodity battle nor fully consolidated — it rewards scale in distribution while allowing nimble brands to capture premium niches.
- Newell Brands (Sharpie, Paper Mate) : Leverages iconic brand equity and broad distribution to defend core office and school segments. Their multi-format product lines and learning-oriented positioning give them scale advantages in trade promotions and shelf presence.
- BIC : A cost-and-reach leader for mass-market applications; excels in simple, reliable chisel-tip designs and price-led channel strategies that maintain penetration in high-volume retail environments.
- Stabilo : Differentiates through technology (e.g., anti-dry-out) and high-volume fluorescent portfolios, capturing users who prioritize performance for heavy-note-taking use cases.
- Pilot, Zebra, Pentel : These Japan-based incumbents combine steady product development with regional distribution strengths; their offerings — including erasable and mild pastel formats — cater to both functional and aesthetic use cases.
- Staedtler, Faber-Castell, Crayola, Edding, ACCO Brands : Each plays a complementary role across premium, eco-conscious, and education-focused niches; several emphasize refillable or eco-friendly packaging and safety-first formulations to win institutional accounts.
Competitive advantage in 2026 will be a function of four capabilities: formulation and IP (ink chemistry), design and packaging, channel orchestration (brick-and-mortar vs. online vs. institutional), and compliance-certification velocity.
Recent Developments That Reframe Strategic Options
- Product-safety incidents have tangible consequences: A recall tied to phthalate content serves as a sober reminder that compliance lapses materially affect supply continuity and brand trust.
- Material innovation is visible across adjacent categories: Specialty pigment innovations showcased at industry events signal crossover opportunities — for example, formulations developed for cosmetics and effects pigments that could inform premium highlighter inking and finishes.
- Packaging and sustainability moves by incumbents show where consumer-facing differentiation is migrating: eco-packaging launches in 2025 demonstrate that even small-format stationery items can be positioned on sustainability platforms.
What the PW Consulting Report Contains — Practical, Transaction-Ready Modules
The full Worldwide Highlighters Market report provides a pragmatic suite of tools for 2026 decision cycles. Highlights include:
- Executive summary and scenario-based forecasts (2026–2032) with sensitivity analyses.
- Actionable go-to-market playbooks for brand owners, private-label manufacturers, and retailers — including promotional calendars and SKU rationalization templates.
- Channel economics models that compare EBITDA contribution across stationery retail, supermarkets, online platforms, and direct institutional sales.
- R&D and sustainability roadmap with formulation benchmarking, certification pathways, and cost-benefit analyses for green claims.
- Supplier maps and sourcing scorecards, plus an M&A screening matrix identifying targets by strategic rationale (technology, distribution, or category extension).
- Regulatory compliance matrix and recall-response playbook, with templated testing timelines and external counsel checklists.
- Competitive intelligence dossiers on leading manufacturers, including capability heatmaps and strategic options for partnership, licensing, or competitive defense.
- Workshops and interactive dashboards designed for executive alignment and 90–180 day implementation sprints.
Strategic Recommendations for 2026
Below are the priority actions we counsel for organizations active or considering entry into the highlighters market in 2026. Each recommendation is supported by the quantitative and qualitative analyses contained in the full report.
- Prioritize a “compliance-first” product roadmap: reformulate high-risk SKUs now to avoid costly recalls and to access institutional tenders.
- Invest selectively in premium and specialty SKUs (pastel/mild, dual-tip, novelty/scented-free alternatives) where margin uplift justifies NPD spend.
- Adopt a differentiated channel strategy: use online platforms to incubate premium variants and brick-and-mortar to drive high-velocity mainstream SKUs.
- Integrate sustainability claims with third-party certification to monetize green premiums and reduce time-to-shelf for institutional buyers.
- Implement scenario-based inventory hedges that account for tariff shifts and testing lead times to reduce supply disruptions.
- Explore M&A or licensing opportunities to acquire niche ink chemistries or patented anti-dry-out technologies that accelerate product differentiation.
Why This Preview — and Why Now
Our preview is intended to equip decision-makers with the strategic lens required for 2026: a year where steady market growth coexists with heightened regulatory expectations and material-driven innovation. The market’s predictability enables focused investments, but the winners will be those who combine compliance rigor, channel intelligence, and product differentiation.
PW Consulting’s full report converts these insights into executable plans — from unit-economics models and SKU-level margin tables to supplier risk matrices and M&A screening criteria. For boards, commercial leaders, and R&D heads, it offers both the evidence base and the implementation tools to act with confidence in 2026.
Accessing the Full Analysis
This preview intentionally omits the proprietary segment-level benchmarks and scenario tables that underpin our recommendations. To obtain the complete dataset, granular country- and channel-level dashboards, and our proprietary valuation models, please visit PW Consulting’s market research portal or contact our markets desk for a briefing and licensing options.
Our team is available to conduct tailored briefings, workshop the findings with your commercial leadership, or deliver an implementation-ready sprint to translate insights into measurable top- and bottom-line outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Highlighters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Marine High-Pressure Water Mist Market Set to Reach USD 864.68 Million by 2032
By pmarketresearch, 2026-07-13
Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
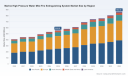
PW Consulting’s latest market study on Worldwide Marine High Pressure Water Mist Fire Extinguishing Systems synthesizes five years of historical data, a forward-looking forecast through 2032, and a highly practical toolkit for procurement, engineering and strategic planning. The marine water‑mist market has evolved from an estimated USD 410.5 Million in 2020 to USD 558.3 Million in 2025, and our model projects continued expansion to approximately USD 582.2 Million in 2026 and beyond, reaching an estimated USD 864.7 Million by 2032. The compound annual growth rate for the forecast period (2026–2032) is 6.45%—a trajectory that makes water‑mist systems a core consideration for vessel designers, operators and classification‑driven procurement teams in 2026.
Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market
This announcement is designed as a strategic preview: we outline the themes, competitive dynamics, regulatory inflection points and the practical deliverables inside the full report. Consistent with our “trailer” principle, detailed regional, component and vessel‑type splits are intentionally withheld from this release to encourage direct engagement with the full report and the interactive models available on the PW Consulting portal.
Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market
Why this matters for 2026 corporate decisions
- Regulatory inflection: From 2026, amendments to the IMO FSS Code and new national guidance for passenger ships raise the bar for fixed water‑based extinguishing systems and address weather deck and vehicle‑carriage risks. These changes convert previously optional design choices into regulatory must‑haves for newly constructed vessels and refits.
- Growing exposure vectors: The increasing prevalence of battery‑powered vehicles and more complex fuel/oil scenarios aboard modern vessels elevates the operational importance of rapid, water‑efficient suppression solutions that can be validated under SOLAS acceptance pathways.
- Market momentum and scale: With a steady growth path and forecast CAGR of 6.45%, capital planners and safety managers must balance near‑term capital expenditure against long‑term reductions in damage risk and potential insurance benefits.
- Supplier concentration and negotiation leverage: Market concentration metrics indicate a consolidated supply base (top‑3 firms account for a majority share and the top‑5 further extend control). Buyers can exploit this structure to negotiate service agreements, bundled maintenance and multi‑vessel discounts—but must remain aware that approval credentials and proven marine track records are differentiating factors.
What the report delivers — practical, decision‑grade content
The full PW Consulting study was built for operators, class society liaisons, OEM shipyards and investor committees. It goes well beyond market sizing to provide executable modules:
Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market
- Proprietary demand model and scenario engine: interactive Excel models calibrated to historical uptake (2020–2025) and our baseline 2026–2032 forecast. Model inputs can be manipulated for alternative growth, retrofit rates and regulatory adoption curves.
- Regulatory compliance matrix: a crosswalk of IMO/SOLAS, national guidance (including the 2026 amendments) and classification society acceptance criteria—mapped to design choices and approval documentation requirements.
- Procurement and specification playbooks: standardized technical specifications, inspection checklists and test protocols tailored to marine environments, plus vendor evaluation scorecards for OPEX and life‑cycle cost comparison.
- Commercial benchmarking and contracting templates: total cost of ownership templates, spare‑parts provisioning norms and service‑level templates keyed to maritime operations and port logistics realities.
- Competitive heatmap and supplier profiles: deep, comparative intelligence on leading technology providers with strengths, approval footprints and go‑to‑market plays (summary provided below; full profiles in the report).
- Case studies and retrofit frameworks: real‑world installation, commissioning and failure‑mode case studies drawn from cruise, ro‑ro and offshore installations, with retrofit roadmaps to minimize downtime and certification risk.
Competitive landscape — what market leaders are doing
The supplier ecosystem is populated by both specialist innovators and diversified industrial groups. Across the leaders we track, three strategic differentiators determine competitive positioning: proven IMO/class‑society approvals for marine applications, nozzle and materials engineering for corrosive shipboard environments, and service/ commissioning footprints that reduce client downtime and compliance risk.
- Marioff Corporation Oy — the established pioneer in high‑pressure water‑mist with its HI‑FOG® platform. Marioff’s systems are engineered specifically for marine applications and have a long record of full‑scale testing and SOLAS‑oriented acceptance. Recent corporate steps (including factory investment to expand manufacturing capacity and sustainability measures in early 2026, and a visibility roadshow in 2025) signal a push to broaden service and aftermarket offerings alongside core product sales.
- Siemens AG — brings scale and systems integration capability with its Sinorix solutions. Siemens positions water‑mist as a systems‑level safety engineering option for confined shipboard spaces, leveraging its competence in control systems and detection integration—an advantage where monitoring and integration with vessel automation is a procurement priority.
- The Hiller Companies (Hiller Water Mist / Securiplex) — focuses on high‑pressure, marine‑approved platforms (e.g., FIRE‑SCOPE® 5000) with materials and nozzle design tailored to naval and offshore standards. Their historical approvals with classification bodies and military installations represent a ready choice where strict approval footprints are non‑negotiable.
- Johnson Controls International — with AquaMist Fog, supplies both cylinder‑based and pumped high‑pressure solutions targeted at machinery spaces and turbine protection. Their global service network supports fleet operators looking for a single supplier for fire suppression across shipboard and shore‑side facilities.
- Danfoss Semco, Ultra Fog, FOGTEC and AQUASYS Technik — these specialist suppliers concentrate on engineered micro‑nozzle performance, compact piping and minimal water use. Each brings regional strengths, approval pedigrees and niche engineering options for specific vessel types and hazard profiles.
Collectively, top players capture a significant share of the market (the top‑3 and top‑5 concentration bands indicate a market where established suppliers dominate product approvals and large marine program installations). That makes supplier selection a strategic choice between established approval footprints and localized engineering agility.
Regulatory and technical dynamics that will drive procurement in 2026
- IMO FSS Code amendments effective 2026 and related SOLAS guidance elevate engineering documentation and testing requirements for fixed water‑mist systems. Buyers who delay specification updates risk retrofit complexity and schedule slippage.
- National guidance (for example, updated passenger ship rules addressing vehicle decks and individually addressable detection in ro‑ro spaces) creates immediate design implications for new builds and major refits commencing in 2026.
- Approval pathways remain critical: acceptance under IMO testing guidelines (e.g., MSC.1/Circ.1312 equivalency testing) is a gating factor for machinery‑space installations and for insurers and class approval.
- Material selection continues to matter: nozzle and piping metallurgy (austenitic stainless steel with titanium orifice tips in some systems) is now a standard consideration for marine longevity and corrosion resistance—impacting CAPEX and life‑cycle maintenance planning.
Recommended 90‑day actions for shipowners and yards
- Immediate compliance audit: map existing fleet and new‑build pipelines against 2026 IMO and national amendments. Prioritize vessels where certification exposure is highest and where retrofit windows coincide with scheduled yard visits.
- Supplier pre‑qualification sprint: narrow long‑list with mandatory approval and service criteria. Use a weighted‑score template (available in the full report) that balances approval pedigree, local service footprint and life‑cycle cost.
- Procurement and warranty alignment: negotiate bundled warranty and spare‑parts packages to offset higher initial capital for corrosion‑resistant assemblies and to secure predictable OPEX.
- Scenario budgeting: incorporate the PW Consulting model’s downside, base and upside scenarios for retrofit adoption rates into 2026 capex requests to finance and insurance stakeholders.
How to access the full intelligence
This release highlights the strategic contours and actionable playbooks inside PW Consulting’s Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market report. To preserve the integrity of procurement negotiations and to deliver a focused, consultative engagement with operator teams, detailed regional, component and vessel‑type splits are not published in this public summary. The full report contains the complete segmentation tables, interactive model files, supplier scorecards and raw data downloads required for transaction‑grade decision‑making.
For boards, procurement committees and technical teams planning capital and compliance decisions in 2026, the full study provides the calibrated forecasting, compliance mapping and step‑by‑step implementation guidance necessary to convert regulatory change and market growth into defensible, cost‑effective safety outcomes.
Contact PW Consulting to request the full report and access the interactive forecast model, supplier due‑diligence templates and retrofit playbooks that will underpin high‑confidence decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Marine High Pressure Water Mist Fire Extinguishing System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Pupil Expanders Market to Reach USD 51.05 Million by 2032, Growing at a 6.25% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Worldwide Pupil Expanders Market — Strategic Imperatives for 2026
PW Consulting is pleased to release an executive briefing drawn from our forthcoming Worldwide Pupil Expanders Market report (base year 2025, forecast 2026–2032). This synthesis outlines the strategic value of the full study for executive decision-making in 2026, highlighting demand dynamics, competitive posture, regulatory and reimbursement pressure points, and practical playbooks that buyers, manufacturers and investors can deploy. The briefing is intended as a high-value preview: it demonstrates the depth of our analysis while preserving proprietary segment-level tables and models that are available only in the full report.
Worldwide Pupil Expanders Market
Why this market matters in 2026
Pupil expanders have moved from niche adjunct tools to mission-critical disposables in contemporary anterior-segment surgery. Our market model — built from historical volumes (2020–2025) and bottoms-up supply-side analysis — places the global pupil expanders market at approximately USD 33.4 Million in 2025, with a steady compound annual growth rate of 6.25% across the forecast window. Under our central-case projection the market grows to roughly USD 34.5 Million in 2026 and reaches about USD 51.1 Million by 2032.
Worldwide Pupil Expanders Market
For 2026 corporate planners, these topline dynamics translate into three practical realities:
Worldwide Pupil Expanders Market
- Predictable, mid-single-digit growth allows for targeted investment rather than transformational capital deployments.
- Device differentiation (material, insertion ergonomics, compatibility with femtosecond workflows) is now a decisive commercial lever.
- Reimbursement and facility coding set the ceiling for price realization in many end markets; strategies must be aligned to payment architecture.
What the full PW Consulting report delivers (practical content)
We designed the report to be a working tool for commercial, clinical and corporate strategy teams. The deliverables include:
- Detailed market sizing and consensus scenario forecasts (base year 2025, forecast 2026–2032) with downloadable model files for sensitivity testing.
- Channel and end‑user demand mapping that links procedure volumes to device adoption trajectories and product form factors.
- Reimbursement and payer intelligence: coding overlays, facility-fee dynamics, and country-level payment realities that influence price capture.
- Regulatory pathway compendium: clearance patterns, typical 510(k) predicates, and compliance risk checklists for new entrants.
- Competitor benchmarking: product feature matrices, go‑to‑market footprints, recent launches and pipeline signals for the leading suppliers.
- Commercial playbooks: tender/pricing negotiation templates, OR education frameworks, distribution optimization and ASC vs. HOPD strategies.
- M&A and partnership checklist: value levers, integration risks, and carve‑out metrics that private equity and strategics use in diligence.
- Primary research appendices: surgeon and purchasing decision‑maker survey results, unmet needs prioritization and case studies of clinical adoption.
Each section is written and modeled to be actionable within a 90-to-180 day execution horizon. The report focuses on the levers that will matter most to 2026 budgets — not academic exercises — and it includes templates you can drop into commercial plans and board materials.
Competitive landscape — what to watch
The market is shaped by a set of established device specialists and a number of agile niche players. Our assessment of leading firms highlights product, regulatory and route-to-market differences that materially affect competitive strategy:
- MicroSurgical Technology (MST) — Redmond, WA ( https://microsurgical.com). MST’s Malyugin Ring Classic is a proven polypropylene ring used widely for small pupil and IFIS cases. The product’s clinical reputation for atraumatic, stable expansion makes MST a go‑to incumbent for many surgeons. Strategic implication: incumbency and strong clinical advocacy increase switching costs; challengers must demonstrate either superior clinical outcomes or clear OR efficiency gains to displace the Malyugin.
- OASIS Medical, Inc. — Glendora, CA ( https://www.oasismedical.com). OASIS markets a single‑use polypropylene iris expander with an integrated inserter. Its disposability and procedural ergonomics make it attractive in high‑throughput ASCs. Strategic implication: companies should evaluate inserter design as a product differentiator and an asset for bundle contracting with ambulatory centers.
- BVI Medical (Beaver‑Visitec International) — Waltham, MA ( https://www.bvimedical.com). The Visitec I‑Ring (polyurethane) emphasizes atraumatic circular expansion and single‑use sterility. Strategic implication: material choice (polyurethane vs. polypropylene) drives surgeon preference and inventory segmentation; manufacturers must validate their material claims with head‑to‑head clinical data to win share.
- Med Invent Devices Pvt. Ltd. — India. The B‑HEX Pupil Expander is FDA‑registered and positioned to address limitations of traditional rings. Strategic implication: lower-cost regional manufacturers are credible competitors in price-sensitive markets and for large, volume-based tenders.
- FCI‑Ophthalmics , AJL Ophthalmic SA (Canabrava Ring), APX Ophthalmology , Diamatrix and Ambler Surgical . Each offers differentiated designs (external fixation systems, femtosecond-compatible expanders, novel geometry rings) that target discrete clinical use-cases. Strategic implication: product portfolios that emphasize procedure-specific advantages (e.g., femto integration, corneal fixation) can command preferential adoption among high-volume specialists.
Collectively, the leading vendors maintain strong clinical advocacy and regional distribution. The marketplace rewards demonstrable improvements in OR efficiency, reduction in iris trauma, and compatibility with existing phaco and femtosecond platforms.
Regulation, reimbursement and materials — the operational levers
- Regulatory profile: Pupil expanders are regulated as ophthalmic devices in major markets. The 510(k) pathway is a common route to clearance, and we continue to see active predicate use and iterative clearances across suppliers. A recent example is a 510(k) clearance activity in the anterior segment category reported in March 2025, underscoring ongoing product refresh cycles and clearance activity in this device class.
- Reimbursement dynamics: Procedure coding materially affects pricing strategy. CPT code 66982 (complex cataract surgery) is broadly used and, in many systems, includes the cost of iris expansion devices within the facility fee. This means device-level supplemental reimbursement is often limited; pricing must therefore consider the facility payment ceiling and the purchaser’s total cost of care calculus.
- Materials and single‑use economics: Common materials include polypropylene, polyurethane, and medical‑grade nylon or silicone. Material selection impacts manufacturing cost, sterilization approach, tactile properties and perceived trauma risk. Given prevailing single‑use sterility expectations, manufacturing scale and supply‑chain resilience are critical determinants of margin.
Strategic recommendations for 2026
Based on our analysis, Pw Consulting recommends the following actions for market participants planning 2026 initiatives:
- For manufacturers: prioritize incremental clinical evidence that quantifies OR time saved and adverse‑event reductions. Invest in inserter ergonomics and femto compatibility as pragmatic differentiation pathways. Build supply‑chain redundancy for single‑use components to minimize stockouts that affect ASCs.
- For hospital procurement and ASCs: treat pupil expanders as part of the bundled procedural cost. Negotiate volume-based agreements that allow migration to preferred suppliers while preserving surgeon choice via pilot programs and clinical validation periods.
- For investors and M&A teams: target companies that combine a defensible clinical value proposition with scalable manufacturing. Pricing pressure from facility fee inclusion favors companies with low per-unit COGS or those that can sell complementary value-added services to surgeons and facilities.
- For regulators and policy teams: monitor predicate evolution and device claims around atraumatic outcomes; refinements in labeling and claims may open or restrict competitive positioning.
How PW Consulting’s report helps you act in 90–180 days
The full report contains scenario-tested models you can use to stress-test pricing, launch timing, and regional entry strategies for 2026. It includes sales playbooks, an RFP template for ASCs and hospitals, and a regulatory checklist for 510(k) filings. We provide templates for contracting negotiations that reflect the reality that pupil expander costs are commonly embedded in facility reimbursement frameworks — a critical fact when calculating allowable price uplift.
This preview is intended to guide your strategic prioritization. The complete report provides the granular segmentation tables, regional and end-user breakouts, and company market shares that are necessary for detailed budgeting and territory planning. Those proprietary tables and downloadable models are available exclusively through the PW Consulting report portal.
Next steps
If your 2026 planning cycle includes procurement review, product development prioritization, or M&A diligence in the ophthalmic disposables space, PW Consulting’s Worldwide Pupil Expanders Market report is designed to be immediately operational. Visit our report page to access the full dataset, supporting models, and supplier scorecards that are necessary to convert these insights into measurable actions.
For team briefings, data-extraction support or bespoke scenario modelling, PW Consulting’s senior analysts are available to provide workshops and board-level presentations tailored to your organizational needs.
For detailed analysis of this topic, please visit the official page: Worldwide Pupil Expanders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide TMQ Rubber Antioxidant Market to Reach USD 701.05 Million by 2032 at a 4.12% CAGR; Asia Pacific Leads with USD 295.93M in 2025
By pmarketresearch, 2026-07-13
Worldwide TMQ Rubber Antioxidant Market: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
As companies prepare their 2026 strategic plans, TMQ (2,2,4-trimethyl-1,2-dihydroquinoline) rubber antioxidants occupy a uniquely consequential position within tire and rubber supply chains. PW Consulting’s latest Worldwide TMQ Rubber Antioxidant Market report — built on a 2025 base year and extending through a 2026–2032 forecast horizon — synthesizes market sizing, technology pathways, supply-chain vulnerabilities, regulatory inflection points and competitive positioning into actionable guidance for procurement, R&D and corporate strategy teams.
Worldwide TMQ Rubber Antioxidant Market
Market trajectory in context
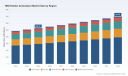
Our analysis shows a steady, data-backed expansion of the global TMQ market. From a 2025 base (our analytical anchor), the market continues on a mid-single-digit growth trajectory with a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast window. That trajectory reflects a balance of forces: mature end-markets such as tires and industrial rubber products continuing to modernize formulations for longevity, while sustainability and regulatory pressures reshape supplier choices and product innovation. By the end of the forecast horizon, the market is projected to be materially larger than the mid-decade base — a growth profile that supports continued supplier investment but also invites competitive consolidation and strategic differentiation.
Worldwide TMQ Rubber Antioxidant Market
Why 2026 is a decisive year for corporate decision-makers
- Procurement and supply security: Companies that lock in diversified sourcing strategies in 2026 will be better positioned against raw-material cyclicality and capacity swings. TMQ production uses commodity inputs that can be subject to supply squeezes; early risk-mitigation contracts, regional dual-sourcing and inventory hedges are pragmatic outcomes of our scenario analysis.
- R&D and formulation roadmaps: OEMs and compounders face a two-track challenge: maintaining performance benchmarks (e.g., heat/oxidative aging resistance) while responding to customer and regulatory demand for lower lifecycle impact. 2026 is the year to accelerate lab-to-pilot validation of sustainable TMQ variants and complementary stabilizer systems.
- CapEx and capacity planning: Given the measured market growth and the industry’s concentration dynamics (our concentration metrics indicate the top three firms account for a significant share of supply, with CR3 at 42.15% and CR5 at 58.6%), strategic investment decisions on capacity expansion versus contract farming or tolling should be revisited with a focus on flexibility and sustainability certification.
Report utility — what executives will use immediately
The report is constructed as a playbook, not just an academic exercise. Key deliverables include:
Worldwide TMQ Rubber Antioxidant Market
- Market sizing and forward-looking scenarios calibrated to 2025 baselines and to multiple demand trajectories through 2032, enabling stress-tested budgeting.
- Procurement and risk-mitigation frameworks that prioritize supplier scorecards, dual-sourcing thresholds and inventory-buffer design tailored to TMQ’s production economics.
- Technical annexes explaining production chemistry, key upstream inputs and process levers that influence unit cost and impurity profiles — essential for compounders and quality teams.
- Competitive benchmarking modules featuring supplier profiles, capability maps and strategic moves (product launches, certifications, capacity shifts) to inform vendor selection and partnership negotiations.
- A regulatory and sustainability tracker highlighting certifications and recognized eco-variants — a practical guide for compliance teams and sustainability leads mapping their procurement policies.
- M&A and JV playbooks with valuation heuristics and integration checklists for companies considering inorganic growth to secure TMQ access or downstream integration.
Key dynamics shaping the market
- Supply-side structure and concentration: The TMQ supplier landscape combines a set of large-scale incumbents with specialized regional producers. Our concentration metrics indicate a moderately consolidated market where a handful of suppliers exert meaningful pricing and availability influence. That structure favors buyers who pursue strategic relationships and certifications as levers for preferred pricing and assured supply.
- Sustainability and certification as market differentiators: Certification and sustainable-feedstock variants are no longer boutique selling points. Recent industry moves — including ISCC PLUS certifications and product launches that emphasize high sustainable input content — demonstrate how sustainability credentials are translating into commercial advantages in tender processes and OEM sourcing lists.
- Regulatory developments and technology endorsement: Inclusion of TMQ variants and production technologies in national innovation promotion lists can accelerate adoption and stimulate capacity additions. These dynamics are particularly salient where policy and procurement intersect, altering competitive positioning for certified producers.
- Raw material and process considerations: TMQ’s production chemistry — condensation routes using aniline and acetone under acid catalysis — has implications for feedstock sourcing, impurity management and process upscaling. Small differences in feedstock ratios, catalysts, and polymerization practices can materially affect product performance and cost.
Competitive landscape — how to read supplier signals
The competitive map contains a mix of global specialty players and regionally focused producers. Several tactical implications emerge from our company-level review:
- Industry leaders drive scale and credibility: Firms with large-scale units and high-content TMQ capacity lead on reliability and long-term contracts. These suppliers are often selected for large tire manufacturers and major compounders where continuity of supply and standardization are paramount.
- Certifications and sustainable variants are becoming table stakes for premium positioning: Suppliers that have secured ISCC PLUS certification or launched high-sustainability TMQ variants demonstrate both upstream feedstock integration and downstream marketing advantages. Such moves are rapidly altering RFP evaluation criteria.
- Regional manufacturers offer agility and cost competitiveness: A cohort of regional suppliers provides responsiveness, backward-integration opportunities and appeal for short-lead-time local sourcing. For many buyers, a blended sourcing strategy that mixes global incumbents and agile regional partners optimizes cost and risk.
- Technology and process IP matter: Proprietary production practices, including greener synthesis routes and pre-dispersion capabilities for compound compatibility, are meaningful differentiators that influence formulation performance and processing efficiency.
Recent industry developments to watch (evidence-based)
- Mid-2025 ISCC PLUS certifications and product announcements have accelerated the commercial rollout of sustainable TMQ variants; these moves signal a shift in buyer expectations and a new layer of supplier selection criteria focused on certified feedstock pathways.
- Corporate announcements of capacity upgrades and product launches by both multinational and regional firms suggest strategic bets on the mid-term demand resilience of TMQ in tire and industrial rubber applications. Buyers should interpret this as both opportunity and a prompt for rigorous supplier due diligence.
Practical recommendations for 2026 decision cycles
Our report translates intelligence into execution-ready recommendations across four priority areas:
- Procurement strategy: Implement a tiered sourcing model combining long-term agreements with leading certified suppliers and flexible spot arrangements with regional players. Insert sustainability and certification clauses into contracts to future-proof supply and reduce requalification costs.
- Product and formulation strategy: Co-invest with strategic suppliers to pilot sustainable TMQ variants and pre-dispersed formats that can reduce mixing energy and improve dispersion in modern compounding processes.
- CapEx & footprint planning: Delay irreversible greenfield expansions until pilot outcomes for sustainable TMQ derivatives are validated; prefer modular or tolling arrangements where controllable scale-ups are required.
- M&A & partnerships: Target bolt-on acquisitions or JVs with regional manufacturers that offer feedstock proximity, process IP or certification pathways — these yield faster access to regional markets and mitigate single-source exposure.
What PW Consulting’s report will not give away — and why
In keeping with our “trailer” approach, the public executive brief is designed to evidence deep analytical rigor while intentionally withholding granular segmentation-by-region and by-application shares, and specific supplier revenue breakdowns. These detailed segment tables, supplier financial profiles, and client-specific benchmarking matrices are available exclusively in the full report and in our interactive client portal. This calibrated disclosure protects sensitive commercial insights while delivering immediate strategic value to readers.
How decision-makers should use this report in 2026
Use the report as a decision-support tool across scenario planning, supplier negotiation, sustainability roadmapping and M&A screening. For procurement leaders, it delivers the quantitative baseline and vendor scoring frameworks needed to redesign sourcing strategies. For R&D and product teams, the technical annexes and process analysis de-risk formulation changes. For strategy and corporate development teams, the competitive intelligence and scenario outputs accelerate prioritization and valuation choices.
Next steps
- Engage PW Consulting for a tailored briefing to translate the report’s scenarios into a 90–180 day action plan aligned with your 2026 budget cycles.
- Request the supplier due-diligence addendum for procurement teams preparing RFPs or strategic contracts that require verified sustainability and production-capacity evidence.
- Commission a focused pilot study on sustainable TMQ variants or pre-dispersed formats to quantify cost, performance and qualification timelines for OEMs and compounders.
PW Consulting’s Worldwide TMQ Rubber Antioxidant Market report combines rigorous market sizing, concentration analysis and evidence-based scenario planning designed to make 2026 strategic choices less uncertain. For executives who need to convert market signals into defensible decisions — procurement teams, product leaders and corporate strategists — the full report and our bespoke advisory services provide the precision input your 2026 playbook requires.
For detailed analysis of this topic, please visit the official page: Worldwide TMQ Rubber Antioxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Isononanoyl Chloride Market to Grow at a 4.8% CAGR in 2026–2032 Outlook
By pmarketresearch, 2026-07-13
Worldwide Isononanoyl Chloride Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies plan investments, sourcing strategies, and product roadmaps for 2026, the Isononanoyl Chloride (INCL) market will require a combination of supply-chain finesse, regulatory discipline, and targeted sustainability investments. PW Consulting’s Worldwide Isononanoyl Chloride Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) projects a continued expansion from an estimated global market size of USD 75.5 Million in 2025 to roughly USD 104.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.8% across the forecast window. This briefing highlights how that trajectory should shape commercial choices in 2026 while intentionally withholding detailed subsegment tables to encourage readers to consult the full report for actionable granularity.
Worldwide Isononanoyl Chloride Market
Market snapshot & forward view
-
Historical momentum (2020–2025) shows resilience amid feedstock volatility and episodic demand swings. After a moderate dip in the early-2020s, the market recovered steadily, reaching near-term stability by our 2025 base.
Worldwide Isononanoyl Chloride Market -
Near-term inflection (2026): PW Consulting’s forecast anticipates an uptick as downstream industries re-optimize inventories and invest in differentiated peroxide initiators and specialty intermediates. Our point forecast for 2026 is approximately USD 82.1 Million, with steady growth thereafter to 2032 under the central-case assumptions.
Worldwide Isononanoyl Chloride Market -
Structural outlook (2026–2032): A mid-single-digit CAGR of ~4.8% masks underlying heterogeneity — pockets of higher growth tied to specialty applications and sustainability-driven product conversions, alongside mature segments where competition centers on cost and logistics efficiency.
Why 2026 is pivotal for corporate strategy
-
Raw material dynamics: Isononanoyl Chloride production is materially exposed to feedstock inputs — principally the chlorination of isononanoic acid. Volatility in upstream acids or substitute fatty acid streams transmits quickly to producer margins. Companies entering contracts or expanding capacity in 2026 must build price- and availability-sensitivity into their models.
-
Regulatory and operational risk: INCL hydrolyses in the presence of moisture to release hydrochloric acid, creating explicit handling, storage, and transport requirements under standard chemical safety regimes. Compliance investments — containment, secondary containment for logistics, and specialised packaging — become differentiators rather than cost centers for high-integrity suppliers and buyers.
-
Sustainability as a commercial lever: Mass-balanced, BMBcert-type variants that replace fossil feedstocks with renewables are now commercially available for organic peroxide manufacturing. In many industrial procurement cycles starting in 2026, preference or contract language increasingly favors suppliers capable of supplying renewably-sourced mass-balanced product streams — not merely “greenwashing” claims.
-
Competitive concentration: The market exhibits meaningful concentration — our analysis indicates that the top three suppliers account for a majority share and the top five substantially more. This concentration creates both supply-side bargaining power and M&A opportunity windows for challengers with regional or technical niche advantages.
What the PW Consulting report delivers (practical, operational intelligence)
We designed the report to serve as a working playbook for commercial teams, corporate development groups, and procurement functions. Highlights include:
-
Market sizing and demand modelling: granular scenarios calibrated to feedstock price regimes and downstream demand elasticity. We provide inputs to stress-test capacity assumptions and margin sensitivity across high-, base-, and low-demand cases.
-
Supply-chain mapping: annotated supplier matrices, logistics risk heatmaps, and a tiered supplier-dependency index. These tools enable prioritised contingency planning (e.g., dual-sourcing thresholds and critical spares positioning).
-
Regulatory and HSE checklist: operational controls and transport-classification guidance based on hydrolysis risk and regional handling standards — distilled into a compliance readiness score for rapid auditability.
-
Sustainability transition roadmap: pragmatic pathways to procure mass-balanced or renewable-derived product variants, including cost-to-carbon curves, supplier certification checkpoints (BMBcert and equivalents), and commercial contractual language to capture Scope 3 decarbonisation value.
-
Commercial playbooks: pricing strategy frameworks, indexation clauses, hedging approaches for raw acids, and template SLAs for tolerance, shelf-life, and incident response.
-
Competitive benchmarking and M&A criteria: supplier scorecards combining capacity, geographic footprint, technical capability, and ESG credentials — designed for rapid integration into divestiture or bolt-on acquisition screens.
Competitive landscape: strategically relevant profiles
The market includes a mix of global chemical majors, specialised phosgene-derivative producers, and regional oleochemical and specialty chemical manufacturers. Each archetype requires a different engagement model:
-
BASF SE (Germany) — A global intermediates player offering INCL alongside a full portfolio of acid chlorides and chloroformates, with options for standard and mass-balanced renewable variants. Recent moves at Ludwigshafen to run acid chloride production with renewable electricity credits and to commercialise BMBcert variants underscore a strategy to monetize sustainability while retaining scale advantages. For buyers seeking integrated sustainability credentials and global logistics coordination, BASF remains a primary counterparty.
-
VanDeMark Chemical Inc. (USA) — A specialty phosgene-derivative and custom fatty-acid chloride manufacturer offering technical flexibility and plant-scale customisation. The company is positioned as a development and scale partner for pharmaceutical and agrochemical intermediates where tailored synthesis and regulatory documentation are pivotal.
-
CABB Chemicals (Switzerland) — Operates as a building-block supplier across crop sciences, life sciences, and performance materials. CABB’s global reach and portfolio approach make it a strategic partner for multinational formulators seeking consistent quality across regions.
-
Shiva Pharmachem and Transpek Industry (India) — Regional players delivering cost-competitive acid chloride streams and catering to local and export markets; they are attractive for customers optimizing landed cost with acceptable lead-times and requiring adaptable batch sizes for intermediates.
-
Wilmar International (Singapore) — An oleochemicals specialist with product offerings positioned for organic peroxide manufacture and agricultural intermediates. Wilmar’s feedstock integration strengths provide alternative sourcing options, particularly in markets where oleochemical supply chains reduce exposure to petrochemical price cycles.
Recent company-level development to note
March 2026: BASF announced that its Intermediates division now produces its acid chloride portfolio at Ludwigshafen using renewable electricity credits and commercialises biomass-balanced (BMBcert) variants. This initiative is one concrete example of how sustainability investments are moving from marketing to production reality — and why procurement teams should assess supplier certification pathways and traceability now rather than later.
Strategic recommendations for 2026 decision-makers
-
Embed feedstock volatility into contracts: use hybrid price-indexation clauses tied to feedstock acid indices and define clear pass-through mechanics to protect margins while keeping supply committed.
-
Pursue supplier diversification with capability overlays: pair at least one large, certified global supplier for sustainability and logistics certainty with one technical-specialist supplier for bespoke intermediates and rapid formulation support.
-
Prioritise certified mass-balanced product lanes: where customers or regulations expect decarbonisation evidence, having BMBcert-capable suppliers reduces contract friction and accelerates product approvals in downstream procurement cycles.
-
Invest in logistic robustness: mitigate hydrolysis and HCl incident risk through improved secondary containment, enhanced packaging protocols, and regional warehousing to reduce transit exposures.
-
Calibrate capacity decisions to scenarios: defer greenfield capacity expansions unless anchored by long-term offtake agreements. Instead, consider tolling, contract-manufacturing, or JV structures to capture upside without full upstream capital exposure.
-
Screen M&A targets quantitatively: use the report’s supplier scorecards to set thresholds on technical capability, certification readiness, and margin accretion potential — not just headline capacity.
How to use this preview — and where to get the full playbook
This article provides a strategic scaffold for 2026 planning, illustrating the forces shaping supply, pricing, regulation, and sustainability preferences in the Isononanoyl Chloride market. It intentionally omits full subsegment breakdowns, regional application tables, and supplier-specific volume shares that are central to transaction diligence and tactical sourcing. PW Consulting’s full report contains those high-resolution datasets, including:
-
Region-by-region demand and price curves, with reforecast scenarios keyed to feedstock price regimes
-
Application-level segmentation and margin maps for organic peroxide, agrochemicals, lubricants/surfactants, and pharmaceutical intermediates
-
Supplier-specific scorecards and single-point failure risk indices for supply continuity planning
-
Operational templates: SLA language, HSE checklists, and contract annexes for mass-balanced delivery verification
For boards, procurement heads, and corporate development teams preparing strategic moves in 2026, the difference between an opportunistic outcome and a defensible one will be the quality of forward-looking, operationally relevant intelligence. PW Consulting’s full Worldwide Isononanoyl Chloride Market report is engineered to provide exactly that: a tactical, data-driven foundation for decisions that matter.
For detailed analysis of this topic, please visit the official page: Worldwide Isononanoyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Shoe Drying Racks Market to Grow at 6.12% CAGR, Reaching USD 735.82 Million by 2032
By pmarketresearch, 2026-07-13
Worldwide Shoe Drying Racks Market — Strategic Outlook for 2026 Decision Makers
As organizations plan capital allocations, product roadmaps and channel investments for 2026, the global shoe drying racks market presents a mix of steady demand growth, technological differentiation opportunities, and supply-chain uncertainties that require targeted, actionable strategies. PW Consulting’s latest market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes primary research, trade flows and proprietary modeling to quantify the market’s trajectory — including a compound annual growth rate (CAGR) of 6.12% — and to deliver tactical playbooks that executives can deploy immediately. This release is an executive “trailer”: it surfaces the strategic implications and capabilities embedded in the full report while reserving the full granular datasets and segment-level figures for subscribers.
Worldwide Shoe Drying Racks Market
Why this market matters in 2026
-
Durable consumer-home categories with clear utility (shoe and boot drying) are benefiting from a convergence of product innovation, heightened hygiene expectations and increased off-season outdoor participation. The category has moved beyond undifferentiated plastic stands to value-added electric systems, hygiene-centric solutions and space-saving fixtures for denser living environments.
Worldwide Shoe Drying Racks Market -
Measured on a macro basis, the market size recorded meaningful growth through 2025 and our model indicates continued expansion across the 2026–2032 forecast as consumers and commercial operators invest in protective care for footwear and gear. That growth is underpinned by a calculated combination of product upgrades, channel evolution and selective commercialization into adjacent B2B verticals.
Worldwide Shoe Drying Racks Market -
For 2026 planning cycles, the market presents immediate ROI levers: product premiumization, channel mix optimization (digital-first plus experiential retail), and targeted contracts with commercial buyers (e.g., ski resorts, fire and safety services, food service operators) that can accelerate topline while stabilizing seasonality.
What PW Consulting’s report delivers (practical content)
-
Validated market sizing and demand scenarios — base year 2025 calibration with three demand-case forecasts out to 2032, enabling stress-tested revenue planning and portfolio prioritization.
-
Competitive benchmarking and capability maps — company profiles, product positioning matrices, and an assessment of manufacturing footprints and channel strengths to help buyers pursue partnerships or acquisitions.
-
Go-to-market playbooks — tailored launch plans for DTC, marketplace and wholesale pathways that include CAC/LTV sensitivity templates, sample promotional calendars, and return-on-marketing simulations.
-
Supply-chain and procurement toolkits — supplier-risk matrices, raw-material exposure analysis, recommended hedging approaches and sample contract clauses that guard against resin and component price volatility.
-
Product & technology roadmap guidance — prioritized feature sets (energy efficiency, hygiene coatings, modularity, low-noise convection and IoT-enabled diagnostics) with estimated time-to-market windows and margin-friendly bill-of-material tradeoffs.
-
M&A screening and valuation frameworks — criteria for strategic bolt-ons and tuck-ins, including a short-listing methodology and a model for accretion/dilution across revenue and margin scenarios.
Competitive landscape — who matters and why
The market remains fragmented with several specialized vendors demonstrating deep product expertise and differentiated distribution models. PW Consulting’s competitive analysis highlights both long-established incumbents and focused innovators whose execution paths illustrate the range of strategic options available.
-
Peet Dryer (St. Maries, Idaho, USA; https://www.peetdryer.com/) — A pioneer dating back to 1968, Peet’s strengths are brand heritage, U.S.-based manufacturing for many SKUs, and proven convection-based dryers that emphasize safe, silent drying for a wide array of footwear. Recent independent testing has reaffirmed the brand’s reliability profile, reinforcing its premium positioning among households and outdoor enthusiasts.
-
Alpine Dryers (USA; https://www.alpinedryers.com/) — Focused on wall-mounted and freestanding systems optimized for ski and work boots; their engineering emphasis on high-velocity blowers, self-regulating heaters and rust-free materials enables cross-application sales into residential, athletic and industrial channels as well as international 230V product lines.
-
Williams Direct Dryers (USA; https://www.directdryers.com/) — Positioned firmly in the commercial/industrial segment with wall-mounted and in-locker models tailored to high-throughput environments (ski resorts, industrial facilities, military). The company continues to innovate around energy efficiency and hygienic drying approaches and recently extended its product family to address moisture- and bacteria-related risks in food service environments — a tactical diversification move that could broaden addressable commercial spend.
-
JobSite — Offers silent, convection-based solutions with no moving parts, targeting end-users who prioritize quiet, low-maintenance operation in homes, cabins and quiet workplaces.
-
Lenz Products ( https://lenzproducts.com/) — Known for gentle, temperature-controlled electric dryers and warmers focused on hygiene and prolonging footwear lifespan; a strong contender in hygiene-conscious segments and premium consumer niches.
-
Thermic ( https://www.therm-ic.us/) — Offers scalable solutions for cold-weather gear, prioritizing efficient moisture removal and compact designs for sporting applications such as ski boots and gloves.
PW Consulting’s competitive scorecards in the full report include capability heatmaps, channel pull-through analyses and a multi-factor valuation model designed for M&A screening. The public summary here intentionally omits share estimates and granular CR-levels that subscribers can access in full.
Market dynamics and risks for 2026 planners
-
Raw-material pressure: The consumer hardware segment is sensitive to polymer and component inputs. Recent commodity movements — including quarterly increases in polyethylene and polypropylene resin prices — and indices for plastics and rubber products point to episodic cost pressures. These dynamics materially affect mid- and high-volume manufacturers and should be modeled into 2026 margin scenarios.
-
Tariff and trade effects: Import price movements for core durable goods rose in recent periods, amplifying landed cost volatility for manufacturers reliant on offshore components. Executives should stress-test sourcing footprints and evaluate near-shore or domestic capacity options for critical parts.
-
Regulatory and PPI signals: Producer price indices for rubber and plastics, together with evolving regulatory guidance around flame retardants and antimicrobial claims, imply additional compliance and testing spend for manufacturers pursuing differentiated hygiene claims.
-
Channel evolution: E-commerce continues to reshape buyer acquisition economics, while offline specialty and experiential retail retain importance for higher-ticket, premium appliances that benefit from hands-on demonstration.
-
Seasonality & commercialization: The sector combines consumer seasonality (winter/active months) with steady B2B demand from industrial and service verticals. Diversifying into recurring service contracts in commercial accounts can flatten seasonality and increase customer lifetime value.
Product and innovation themes to watch
-
Energy efficiency and low-noise convection: Differentiation that increases willingness-to-pay while reducing perceived operating cost.
-
Hygiene and material science: Antimicrobial surfaces, moisture-busting airflow design and validated bacteria-reduction claims are marketable features for both consumers and commercial buyers (e.g., food service, PPE custodians).
-
Space-saving and modularity: Wall-mounted and expandable footprints address urban living constraints and multi-user locker applications.
-
Connectivity and diagnostics: Early-stage IoT for fault detection, usage telemetry and service scheduling could unlock new service revenue streams and improve product uptime for commercial customers.
Strategic recommendations for 2026
-
Prioritize product families that combine hygiene claims with low operating cost — these carry higher price elasticity and defendable margins.
-
Establish commercial pilots with high-value institutional buyers (ski resorts, fire departments, food service chains) to secure multi-year contracts and reference sites for channel expansion.
-
Rebalance sourcing: secure multi-year resin and component agreements indexed to transparent benchmarks; evaluate near-shoring options for critical subassemblies to mitigate tariff risk and lead-time variability.
-
Optimize channel mix: scale DTC for margin capture while maintaining selective offline partnerships for premium SKUs and installation-heavy solutions.
-
Use M&A selectively to acquire specialized tech (e.g., IoT diagnostics or hygiene materials) or to consolidate fragmented regional supply chains at accretive multiples.
-
Embed sustainability and end-of-life design considerations to preempt regulatory pressure and to appeal to increasingly value-driven consumers and institutional buyers.
How PW Consulting’s report will accelerate your 2026 decisions
Beyond the strategic overview above, subscribers gain access to the granular worksheets, scenario models and vendor-level data that make these recommendations operational. The full deliverable includes downloadable Excel models, a vendor database with capability filters, procurement templates and a phase-by-phase commercialization timeline tailored to common corporate structures (small OEM, mid-sized specialty brand, private equity platform).
If your 2026 planning includes portfolio repricing, channel reallocation, procurement re-sourcing, or M&A screening in the shoe drying and footwear-care category, PW Consulting’s Worldwide Shoe Drying Racks Market study offers the empirical backbone and tactical assets to move from strategy to execution. For access to the full dataset, segment-level analytics and proprietary vendor scores, please visit our website or contact PW Consulting’s industry practice.
For detailed analysis of this topic, please visit the official page: Worldwide Shoe Drying Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dolomite Products Market to Hit USD 38,559.12 Million by 2032, Expanding at a 3.82% CAGR
By pmarketresearch, 2026-07-13
Worldwide Dolomite Products Market — Strategic Outlook for 2026: A PW Consulting Primer
PW Consulting’s latest market study on Worldwide Dolomite Products offers a decisive playbook for corporate leaders, investors and procurement teams preparing strategies for 2026 and beyond. Drawing on an exhaustive historical review (2020–2025), near-term base-year calibration (2025) and an actionable forecast horizon (2026–2032), the report synthesizes market sizing, competitive dynamics, price signals, regulatory headwinds and operational levers into pragmatic guidance that supports transaction, investment and sourcing decisions in the coming 12–24 months.
Worldwide Dolomite Products Market
Macro snapshot: growth trajectory and market structure
The dolomite products market has demonstrated steady expansion through the 2020–2025 period, with the 2025 base year representing a broadly higher level of activity than at the start of the decade. Our forecast shows the market continuing to grow through the 2026–2032 window at a compound annual growth rate of approximately 3.82%, reflecting steady demand from core industrial applications alongside pockets of higher-margin specialty demand.
Worldwide Dolomite Products Market
- Market momentum in 2026 is projected to extend the recovery and growth trends observed in the base year, with an uptick in capital-intensive downstream uses driving selective capacity investments.
- Concentration is moderate: the top three and top five producers control a meaningful but not dominant share of the value pool (CR3 and CR5 figures indicate room for both global scale advantages and regional incumbency benefits).
- The market’s structure—an interplay of large integrated producers, regional quarry specialists and upstream raw-material owners—creates differentiated risk-reward profiles across players.
Why this report matters to 2026 decision-makers
2026 will be a year of choices: reinvest, consolidate, hedge, or innovate. The report is designed to translate macro visibility into tactical steps with immediate applicability:
Worldwide Dolomite Products Market
- For producers: a prioritized capital allocation roadmap that balances brownfield optimization versus greenfield capacity to serve refractory, construction and aggregate markets.
- For buyers (steelmakers, glassmakers, agribusiness): a supply-security framework combining short-term contractual levers and medium-term co-investment structures to manage both price volatility and quality variance.
- For investors: an M&A playbook identifying targets by asset type (quarry, calcination, pelletizing, specialty processing), synergies, and regulatory exposure.
- For equipment and services providers: a serviceable addressable market lens that distinguishes commoditized product segments from growing specialty niches where margin uplift and technical partnerships are achievable.
Key dynamics shaping 2026 strategies
- Price dispersion and margin pressure: Regional price variability and trade flows are producing divergent margin pools. Our industry price analysis highlights notable regional spreads and a modest upward trend in global export prices. Procurement teams should incorporate scenario-adjusted price curves into supplier negotiations and hedging strategies.
- Regulatory escalation: Tighter mine permitting, environmental compliance and rehabilitation policies in multiple jurisdictions are increasing operating costs and elongating development timetables. Producers must accelerate permitting programs and embed rehabilitation economics in feasibility studies; buyers should factor potential supply squeezes from permitting delays into inventory and alternative-sourcing plans.
- Downstream sensitivity: Policies affecting steel, cement and construction sectors — including tariffs and trade measures — are indirectly influencing demand for dolomite-derived fluxes and refractories. Supply-chain monitoring tied to downstream policy moves is now table-stakes for commercial planning.
- Consolidation and M&A dynamics: The market shows active strategic M&A, with cross-border acquisitions used to secure feedstock and broaden refractory portfolios. Buyers and sellers should prepare value capture cases that reflect integration costs, logistics optimization and product mix synergies.
Competitive landscape: positioning and strategic moves
Our competitor analysis synthesizes public profiles, asset footprints and recent moves to map competitive positioning and likely next steps. The market is populated by global integrated groups, regional champions and specialized processors. Representative names include legacy lime and mineral groups that leverage quarry-to-product integration, refractory-focused manufacturers with sintered and calcined lines, and agile regional producers serving local industrial clusters.
- Integrated multinational producers continue to use scale, distribution networks and product breadth to defend share in commodity applications while selectively investing in higher-value specialty lines.
- Refractory and sintered-dolomite specialists are consolidating upstream supply or forming offtake partnerships to secure consistent ore quality for high-temperature applications.
- Regional miners and processors retain competitive advantages in local logistics and permitting but face increasing capital needs to meet upgraded environmental standards.
- Recent headline moves — including acquisitions to strengthen regional footprints and strategic testing programs for specialty applications — underscore a mixed approach of inorganic growth combined with tech validation for new use cases.
Report contents: practical, replicable tools included
PW Consulting’s study is deliberately operational. It contains:
- Quantitative market model: annual historical series (2020–2025) and a full forecast (2026–2032) with sensitivity runs; interactive dashboards allow scenario toggles for demand shocks, price trajectories and capex timelines.
- Supply-side asset register: geocoded quarry and processing assets, production capacity tiers, ore-quality indicators and an indexed cost-to-produce curve calibrated regionally.
- Commercial playbooks: supplier segmentation, contract templates, elasticity-informed pricing guidance and negotiating levers for buyers and sellers.
- Regulatory and ESG overlays: permitting timelines, rehabilitation cost benchmarks and an emissions-intensity scorecard for processing pathways.
- M&A and investment screens: shortlists for bolt-on vs. transformational targets, valuation multiples ranges, and integration risk checklists.
- Scenario planning matrices and stress tests: tailored for procurement, operations and corporate development teams to stress-test capital and inventory plans under three policy and demand scenarios.
- Company briefs: comparative profiles for major players with capability maps, strategic priorities and near-term playbook recommendations (note: detailed share and volume breakdowns by region/product are reserved for the full report).
Actionable recommendations for 2026
Based on the combined quantitative and qualitative evidence, PW Consulting recommends a four-point agenda for market participants planning for 2026:
- Secure feedstock and quality through a blended contracting approach: combine short-term indexed purchases with medium-term fixed offtakes and strategic equity in critical quarries to mitigate both price and grade risk.
- Prioritize brownfield capacity and product-differentiation: upgrades to calcination lines, sintering capability and pelletizing can unlock specialty margins faster than greenfield projects subject to permitting delays.
- Embed regulatory and ESG programming into feasibility: allocate upfront capex for rehabilitation and emissions reduction to avoid costly retrofits and permit denials; use third-party verification to improve access to sustainable procurement lists.
- Run targeted M&A and partnership screens: identify assets that deliver logistical synergies or downstream integration into refractory and specialty markets, and prepare integration playbooks that focus on ore blending and quality control.
Signal events and market “watch points” for 2026
Our monitoring framework calls for close tracking of: raw-material price dispersion across major origins; the pace of regulatory approvals and any material tightening of extraction norms; downstream demand shifts tied to steel, cement and glass cycles; and consolidation activity among the major integrated producers. Specific events—such as major acquisitions or commercial-scale testing for new dolomite applications—should trigger immediate reassessment of mid-cycle capital allocation.
For example, recent sector activity illustrates these dynamics: testing and certification projects validating dolomite for novel thermal applications are progressing, and acquisitions intended to deepen regional refractory portfolios have already been executed by leading firms. Both types of developments materially influence strategic priorities for producers and buyers alike.
How to use the full report
This public primer is intentionally selective. PW Consulting’s full Worldwide Dolomite Products Market report contains the granular datasets, regional and product-type splits, downloadable models and interactive visualizations that enable scenario execution and transaction-level diligence. If your 2026 plans require precise source-by-source cost curves, multi-scenario P&L templates or a confidential list of prioritized acquisition targets, the full study is the operational toolset you will need.
- Producers and technical teams: use the supply-side register and ore-quality index to optimize blending and capex sequencing.
- Buyers and procurement: deploy the commercial playbooks and hedged sourcing templates to lower total cost of ownership and secure consistent quality.
- Investors and advisors: leverage the M&A screens and scenario outputs to size investment cases and perform downside stress testing.
Next steps
PW Consulting stands ready to brief leadership teams on tailored implications derived from the report’s scenario engine and to support rapid strategy sprints — from sourcing optimization and capex prioritization to M&A diligence and regulatory risk mitigation. For access to the full report, datasets and bespoke advisory engagements, please visit our report page or contact our industry desk for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dolomite Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FC‑BGA Package Substrates Market Poised for 15% CAGR Through 2032
By pmarketresearch, 2026-07-13
FC-BGA Package Substrates Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive summary
As semiconductor architectures pivot toward extreme I/O density and advanced compute, the flip-chip ball grid array (FC‑BGA) package substrate market is undergoing one of the most consequential growth phases in its history. PW Consulting’s new FC‑BGA Package Substrates Market report (base year 2025) finds that the global market has expanded rapidly from a modest multi‑billion USD base in 2020 to a significantly larger market by 2025, and is forecast to continue a high‑growth trajectory through 2032 at a compound annual growth rate (CAGR) of approximately 15% for the 2026–2032 horizon. Our bottom‑up market model projects total market value crossing key inflection points in 2026 and nearly tripling by 2032 under the base case — dynamics that will materially shape capital allocation, supplier strategy, and industrial policy throughout 2026 and beyond.
FC-BGA Package Substrates Market
Why this matters for 2026 corporate decision‑making
- Capacity timing is strategic: Long lead times and concentrated capacity mean that openings made in 2026 will determine supply balances and pricing power into the next decade. Our scenario analysis shows that investment decisions taken in 2026 produce outsized effects on utilization and delivery windows through 2028–2030.
- Raw materials and input risk are binding constraints: ABF build‑up films, high‑end copper foil, and CCL availability are now first‑order drivers of cost and throughput. Price shocks and extended supply lead times are already being observed and amplify the consequences of delayed capacity expansions.
- Customer segmentation is shifting: Data center, HPC, and AI workloads are the principal demand engines for advanced FC‑BGA substrates, while adjacent segments (networking, automotive, and edge compute) create complementary demand patterns that reward flexible capacity and qualification pathways.
Market trajectory and macro view
PW Consulting’s multi‑scenario forecast integrates historical trends (2020–2025) and forward modeling for 2026–2032. Industry recovery and reinvestment lifted the market from its 2020 base to a substantially larger market by 2025, with 2026 representing a critical acceleration point in absolute market value. Under our central scenario, the market grows at roughly 15% CAGR over 2026–2032, with 2026 marking the transition from the immediate post‑cycle replenishment phase into a sustained expansion driven by AI servers, GPUs, and high‑layer count requirements.
FC-BGA Package Substrates Market
Supply‑side dynamics: capacity, concentration and strategic chokepoints
- Concentration and scale matter: The supply base is moderately concentrated; the top three suppliers command a substantial share of market capacity, and the top five become dominant when capacity expansions are considered. This concentration accelerates during cyclical tightness and increases the strategic value of securing preferred supplier status.
- New lines and geographic shifts: Recent capacity announcements and launches — including major production starts and greenfield expansions in multiple jurisdictions — will reshape regional supply balances. These moves are tactical responses to both customer requirements and geopolitical incentive structures, and they materially influence lead times and pricing across 2026.
- Raw material friction points: Price increases for ABF films, extended lead times for CCLs, and a widening gap in high‑end copper foil availability create multi‑layered bottlenecks. These input constraints imply that nominal substrate capacity is not equivalent to effective throughput unless raw material contracts and inventory strategies are synchronized.
Competitive landscape: who matters and why
Leading global substrate manufacturers have differentiated along technical capability, scale, and customer proximity. Key players analyzed in the report include long‑standing Japanese manufacturers renowned for ultra‑fine microfabrication; Taiwanese producers that balance volume with rapid qualification cycles; Korean groups investing heavily to capture AI substrate demand; European specialists targeting niche high‑reliability applications; and a growing set of Chinese and regional suppliers pursuing volume and cost leadership.
FC-BGA Package Substrates Market
- Manufacturers with advanced microfabrication and ultra‑fine wiring capabilities are best positioned to serve the highest layer‑count, highest I/O density packages needed by AI and HPC customers.
- Large Taiwanese players remain pivotal for server and GPU supply chains due to scale and established customer relationships.
- Korean investments — particularly new greenfield capacity targeted at high‑growth compute centers — are rapidly changing the competitive map.
- European and select regional suppliers are capitalizing on premium, high‑reliability segments and localized demand for automotive and industrial electronics.
Notable recent industry developments include production line launches and capacity expansion programs by global incumbents, and multi‑billion‑KRW scale investments to add FC‑BGA capacity in lower‑cost manufacturing jurisdictions. These moves validate our market view that substrate capacity will be a primary battleground in 2026.
Segment and raw‑material intelligence (what we include in the report)
PW Consulting’s full report provides a practical, operational playbook designed for procurement teams, product planners, and corporate strategy groups. Key deliverables include:
- Granular demand model (bottom‑up by package type and application) with vintage demand curves for 2020–2025 and scenario projections for 2026–2032.
- Supply capacity database including age, technology node capability, planned expansions, and ramp profiles — enabling accurate lead‑time and utilization forecasts.
- Input supply assessment for ABF films, CCLs, and high‑end copper foil, including supplier concentration, lead‑time elasticity, and price shock sensitivity.
- Supplier scorecards and qualification roadmaps to support accelerated onboarding or dual‑sourcing for mission‑critical programs.
- Contract negotiation playbook — practical terms and protective clauses designed for periodic shortages, force majeure, and long lead‑time management.
- Scenario and stress tests for pricing, capacity shutdowns, tariffs, and raw‑material supply shocks, with quantified P&L impacts under multiple cases.
- Strategic M&A and J‑V playbook tailored to substrate value chain consolidation and capability acquisition opportunities.
To preserve commercial value for clients, our public summary intentionally withholds certain granular split figures and price trajectories — these are contained in the full report and the downloadable data annex.
Strategic implications and recommended actions for 2026
- Prioritize lead‑time management: Establish multi‑tiered supplier agreements with capacity reservations and clear ramp milestones. For companies dependent on high‑layer count substrates, securing allocation in 2026 is more valuable than spot‑market purchases later.
- Hedge raw‑material exposure: Negotiate long‑term procurement contracts for ABF films and premium copper foil, and evaluate strategic inventory positioning. Joint procurement or off‑take agreements with substrate makers can reduce price volatility and secure throughput.
- Invest selectively in qualification: Accelerate parallel qualification tracks with at least two qualified suppliers for each strategic product family. Passing qualification earlier in 2026 will unlock capacity priority in 2027–2028 cycles.
- Reconsider vertical integration and partnerships: Where scale and margin dynamics justify, explore partial vertical integration or exclusive co‑investment with substrate manufacturers to secure technological roadmaps and priority capacity.
- Localize with eyes open: Geography matters — incentives, tariffs, and industrial policy can materially shift landed costs. Use our scenario maps to model total landed cost under varying tariff regimes and incentive packages before siting decisions.
- Prepare for consolidation: Industry profit pools and capacity imbalances make M&A attractive. Identify targets with complementary technology (e.g., ultra‑fine wiring capability or specialized build‑up processes) to accelerate time to market.
Risk matrix: what keeps supply chain executives awake at night
- Input price spikes: Historic and recent ABF film price increases demonstrate that raw‑material inflation can outpace substrate pricing adjustments, squeezing margins.
- Lead‑time escalation: Extended lead times for CCLs and substrate production have been observed during peaks, with episodes of beyond‑30‑week delivery timelines in prior cycles.
- Geopolitical/tariff risk: Tariff regimes on advanced substrates and critical inputs are reshaping cost competitiveness and driving strategic re‑routing of supply chains.
- Capacity under‑utilization: Premature capacity additions without raw‑material assurance can create stranded assets and depressed returns.
What PW Consulting’s report enables for 2026
For executives preparing 2026 budgets and capital plans, our FC‑BGA report provides actionable intelligence to convert growth forecasts into executable supply strategies. Clients will receive the data and tools to quantify the trade‑offs between speed to market, cost, and risk exposure — enabling precision in negotiating supplier commitments, scheduling capital projects, and shaping governance for sourcing critical substrates.
Next steps and access
PW Consulting’s public brief is intentionally selective. The detailed demand and supply matrices, supplier scorecards, contract templates, and model workbooks — including our near‑term allocation model and upside/downside scenarios — are included in the full report and protected data annex. Organizations planning capacity decisions, procurement negotiations, or strategic investments in 2026 should consult the full deliverable to translate the high‑level imperatives above into executable plans.
For access to the complete FC‑BGA Package Substrates Market report, model license, and bespoke advisory engagements tailored to 2026 decision cycles, please visit PW Consulting’s report page or contact our advisory desk for a guided walkthrough of the findings and scenario tools.
For detailed analysis of this topic, please visit the official page: FC-BGA Package Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com