

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
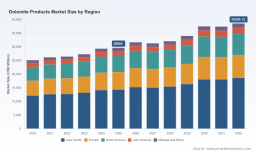
PW Consulting: Worldwide Dolomite Products Market to Hit USD 38,559.12 Million by 2032, Expanding at a 3.82% CAGR

Worldwide Dolomite Products Market — Strategic Outlook for 2026: A PW Consulting Primer
PW Consulting’s latest market study on Worldwide Dolomite Products offers a decisive playbook for corporate leaders, investors and procurement teams preparing strategies for 2026 and beyond. Drawing on an exhaustive historical review (2020–2025), near-term base-year calibration (2025) and an actionable forecast horizon (2026–2032), the report synthesizes market sizing, competitive dynamics, price signals, regulatory headwinds and operational levers into pragmatic guidance that supports transaction, investment and sourcing decisions in the coming 12–24 months.
Worldwide Dolomite Products Market
Macro snapshot: growth trajectory and market structure
The dolomite products market has demonstrated steady expansion through the 2020–2025 period, with the 2025 base year representing a broadly higher level of activity than at the start of the decade. Our forecast shows the market continuing to grow through the 2026–2032 window at a compound annual growth rate of approximately 3.82%, reflecting steady demand from core industrial applications alongside pockets of higher-margin specialty demand.
Worldwide Dolomite Products Market
- Market momentum in 2026 is projected to extend the recovery and growth trends observed in the base year, with an uptick in capital-intensive downstream uses driving selective capacity investments.
- Concentration is moderate: the top three and top five producers control a meaningful but not dominant share of the value pool (CR3 and CR5 figures indicate room for both global scale advantages and regional incumbency benefits).
- The market’s structure—an interplay of large integrated producers, regional quarry specialists and upstream raw-material owners—creates differentiated risk-reward profiles across players.
Why this report matters to 2026 decision-makers
2026 will be a year of choices: reinvest, consolidate, hedge, or innovate. The report is designed to translate macro visibility into tactical steps with immediate applicability:
Worldwide Dolomite Products Market
- For producers: a prioritized capital allocation roadmap that balances brownfield optimization versus greenfield capacity to serve refractory, construction and aggregate markets.
- For buyers (steelmakers, glassmakers, agribusiness): a supply-security framework combining short-term contractual levers and medium-term co-investment structures to manage both price volatility and quality variance.
- For investors: an M&A playbook identifying targets by asset type (quarry, calcination, pelletizing, specialty processing), synergies, and regulatory exposure.
- For equipment and services providers: a serviceable addressable market lens that distinguishes commoditized product segments from growing specialty niches where margin uplift and technical partnerships are achievable.
Key dynamics shaping 2026 strategies
- Price dispersion and margin pressure: Regional price variability and trade flows are producing divergent margin pools. Our industry price analysis highlights notable regional spreads and a modest upward trend in global export prices. Procurement teams should incorporate scenario-adjusted price curves into supplier negotiations and hedging strategies.
- Regulatory escalation: Tighter mine permitting, environmental compliance and rehabilitation policies in multiple jurisdictions are increasing operating costs and elongating development timetables. Producers must accelerate permitting programs and embed rehabilitation economics in feasibility studies; buyers should factor potential supply squeezes from permitting delays into inventory and alternative-sourcing plans.
- Downstream sensitivity: Policies affecting steel, cement and construction sectors — including tariffs and trade measures — are indirectly influencing demand for dolomite-derived fluxes and refractories. Supply-chain monitoring tied to downstream policy moves is now table-stakes for commercial planning.
- Consolidation and M&A dynamics: The market shows active strategic M&A, with cross-border acquisitions used to secure feedstock and broaden refractory portfolios. Buyers and sellers should prepare value capture cases that reflect integration costs, logistics optimization and product mix synergies.
Competitive landscape: positioning and strategic moves
Our competitor analysis synthesizes public profiles, asset footprints and recent moves to map competitive positioning and likely next steps. The market is populated by global integrated groups, regional champions and specialized processors. Representative names include legacy lime and mineral groups that leverage quarry-to-product integration, refractory-focused manufacturers with sintered and calcined lines, and agile regional producers serving local industrial clusters.
- Integrated multinational producers continue to use scale, distribution networks and product breadth to defend share in commodity applications while selectively investing in higher-value specialty lines.
- Refractory and sintered-dolomite specialists are consolidating upstream supply or forming offtake partnerships to secure consistent ore quality for high-temperature applications.
- Regional miners and processors retain competitive advantages in local logistics and permitting but face increasing capital needs to meet upgraded environmental standards.
- Recent headline moves — including acquisitions to strengthen regional footprints and strategic testing programs for specialty applications — underscore a mixed approach of inorganic growth combined with tech validation for new use cases.
Report contents: practical, replicable tools included
PW Consulting’s study is deliberately operational. It contains:
- Quantitative market model: annual historical series (2020–2025) and a full forecast (2026–2032) with sensitivity runs; interactive dashboards allow scenario toggles for demand shocks, price trajectories and capex timelines.
- Supply-side asset register: geocoded quarry and processing assets, production capacity tiers, ore-quality indicators and an indexed cost-to-produce curve calibrated regionally.
- Commercial playbooks: supplier segmentation, contract templates, elasticity-informed pricing guidance and negotiating levers for buyers and sellers.
- Regulatory and ESG overlays: permitting timelines, rehabilitation cost benchmarks and an emissions-intensity scorecard for processing pathways.
- M&A and investment screens: shortlists for bolt-on vs. transformational targets, valuation multiples ranges, and integration risk checklists.
- Scenario planning matrices and stress tests: tailored for procurement, operations and corporate development teams to stress-test capital and inventory plans under three policy and demand scenarios.
- Company briefs: comparative profiles for major players with capability maps, strategic priorities and near-term playbook recommendations (note: detailed share and volume breakdowns by region/product are reserved for the full report).
Actionable recommendations for 2026
Based on the combined quantitative and qualitative evidence, PW Consulting recommends a four-point agenda for market participants planning for 2026:
- Secure feedstock and quality through a blended contracting approach: combine short-term indexed purchases with medium-term fixed offtakes and strategic equity in critical quarries to mitigate both price and grade risk.
- Prioritize brownfield capacity and product-differentiation: upgrades to calcination lines, sintering capability and pelletizing can unlock specialty margins faster than greenfield projects subject to permitting delays.
- Embed regulatory and ESG programming into feasibility: allocate upfront capex for rehabilitation and emissions reduction to avoid costly retrofits and permit denials; use third-party verification to improve access to sustainable procurement lists.
- Run targeted M&A and partnership screens: identify assets that deliver logistical synergies or downstream integration into refractory and specialty markets, and prepare integration playbooks that focus on ore blending and quality control.
Signal events and market “watch points” for 2026
Our monitoring framework calls for close tracking of: raw-material price dispersion across major origins; the pace of regulatory approvals and any material tightening of extraction norms; downstream demand shifts tied to steel, cement and glass cycles; and consolidation activity among the major integrated producers. Specific events—such as major acquisitions or commercial-scale testing for new dolomite applications—should trigger immediate reassessment of mid-cycle capital allocation.
For example, recent sector activity illustrates these dynamics: testing and certification projects validating dolomite for novel thermal applications are progressing, and acquisitions intended to deepen regional refractory portfolios have already been executed by leading firms. Both types of developments materially influence strategic priorities for producers and buyers alike.
How to use the full report
This public primer is intentionally selective. PW Consulting’s full Worldwide Dolomite Products Market report contains the granular datasets, regional and product-type splits, downloadable models and interactive visualizations that enable scenario execution and transaction-level diligence. If your 2026 plans require precise source-by-source cost curves, multi-scenario P&L templates or a confidential list of prioritized acquisition targets, the full study is the operational toolset you will need.
- Producers and technical teams: use the supply-side register and ore-quality index to optimize blending and capex sequencing.
- Buyers and procurement: deploy the commercial playbooks and hedged sourcing templates to lower total cost of ownership and secure consistent quality.
- Investors and advisors: leverage the M&A screens and scenario outputs to size investment cases and perform downside stress testing.
Next steps
PW Consulting stands ready to brief leadership teams on tailored implications derived from the report’s scenario engine and to support rapid strategy sprints — from sourcing optimization and capex prioritization to M&A diligence and regulatory risk mitigation. For access to the full report, datasets and bespoke advisory engagements, please visit our report page or contact our industry desk for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dolomite Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com