

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Isononanoyl Chloride Market to Grow at a 4.8% CAGR in 2026–2032 Outlook

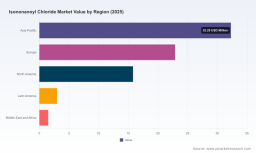
Worldwide Isononanoyl Chloride Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies plan investments, sourcing strategies, and product roadmaps for 2026, the Isononanoyl Chloride (INCL) market will require a combination of supply-chain finesse, regulatory discipline, and targeted sustainability investments. PW Consulting’s Worldwide Isononanoyl Chloride Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) projects a continued expansion from an estimated global market size of USD 75.5 Million in 2025 to roughly USD 104.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.8% across the forecast window. This briefing highlights how that trajectory should shape commercial choices in 2026 while intentionally withholding detailed subsegment tables to encourage readers to consult the full report for actionable granularity.
Worldwide Isononanoyl Chloride Market
Market snapshot & forward view
-
Historical momentum (2020–2025) shows resilience amid feedstock volatility and episodic demand swings. After a moderate dip in the early-2020s, the market recovered steadily, reaching near-term stability by our 2025 base.
Worldwide Isononanoyl Chloride Market -
Near-term inflection (2026): PW Consulting’s forecast anticipates an uptick as downstream industries re-optimize inventories and invest in differentiated peroxide initiators and specialty intermediates. Our point forecast for 2026 is approximately USD 82.1 Million, with steady growth thereafter to 2032 under the central-case assumptions.
Worldwide Isononanoyl Chloride Market -
Structural outlook (2026–2032): A mid-single-digit CAGR of ~4.8% masks underlying heterogeneity — pockets of higher growth tied to specialty applications and sustainability-driven product conversions, alongside mature segments where competition centers on cost and logistics efficiency.
Why 2026 is pivotal for corporate strategy
-
Raw material dynamics: Isononanoyl Chloride production is materially exposed to feedstock inputs — principally the chlorination of isononanoic acid. Volatility in upstream acids or substitute fatty acid streams transmits quickly to producer margins. Companies entering contracts or expanding capacity in 2026 must build price- and availability-sensitivity into their models.
-
Regulatory and operational risk: INCL hydrolyses in the presence of moisture to release hydrochloric acid, creating explicit handling, storage, and transport requirements under standard chemical safety regimes. Compliance investments — containment, secondary containment for logistics, and specialised packaging — become differentiators rather than cost centers for high-integrity suppliers and buyers.
-
Sustainability as a commercial lever: Mass-balanced, BMBcert-type variants that replace fossil feedstocks with renewables are now commercially available for organic peroxide manufacturing. In many industrial procurement cycles starting in 2026, preference or contract language increasingly favors suppliers capable of supplying renewably-sourced mass-balanced product streams — not merely “greenwashing” claims.
-
Competitive concentration: The market exhibits meaningful concentration — our analysis indicates that the top three suppliers account for a majority share and the top five substantially more. This concentration creates both supply-side bargaining power and M&A opportunity windows for challengers with regional or technical niche advantages.
What the PW Consulting report delivers (practical, operational intelligence)
We designed the report to serve as a working playbook for commercial teams, corporate development groups, and procurement functions. Highlights include:
-
Market sizing and demand modelling: granular scenarios calibrated to feedstock price regimes and downstream demand elasticity. We provide inputs to stress-test capacity assumptions and margin sensitivity across high-, base-, and low-demand cases.
-
Supply-chain mapping: annotated supplier matrices, logistics risk heatmaps, and a tiered supplier-dependency index. These tools enable prioritised contingency planning (e.g., dual-sourcing thresholds and critical spares positioning).
-
Regulatory and HSE checklist: operational controls and transport-classification guidance based on hydrolysis risk and regional handling standards — distilled into a compliance readiness score for rapid auditability.
-
Sustainability transition roadmap: pragmatic pathways to procure mass-balanced or renewable-derived product variants, including cost-to-carbon curves, supplier certification checkpoints (BMBcert and equivalents), and commercial contractual language to capture Scope 3 decarbonisation value.
-
Commercial playbooks: pricing strategy frameworks, indexation clauses, hedging approaches for raw acids, and template SLAs for tolerance, shelf-life, and incident response.
-
Competitive benchmarking and M&A criteria: supplier scorecards combining capacity, geographic footprint, technical capability, and ESG credentials — designed for rapid integration into divestiture or bolt-on acquisition screens.
Competitive landscape: strategically relevant profiles
The market includes a mix of global chemical majors, specialised phosgene-derivative producers, and regional oleochemical and specialty chemical manufacturers. Each archetype requires a different engagement model:
-
BASF SE (Germany) — A global intermediates player offering INCL alongside a full portfolio of acid chlorides and chloroformates, with options for standard and mass-balanced renewable variants. Recent moves at Ludwigshafen to run acid chloride production with renewable electricity credits and to commercialise BMBcert variants underscore a strategy to monetize sustainability while retaining scale advantages. For buyers seeking integrated sustainability credentials and global logistics coordination, BASF remains a primary counterparty.
-
VanDeMark Chemical Inc. (USA) — A specialty phosgene-derivative and custom fatty-acid chloride manufacturer offering technical flexibility and plant-scale customisation. The company is positioned as a development and scale partner for pharmaceutical and agrochemical intermediates where tailored synthesis and regulatory documentation are pivotal.
-
CABB Chemicals (Switzerland) — Operates as a building-block supplier across crop sciences, life sciences, and performance materials. CABB’s global reach and portfolio approach make it a strategic partner for multinational formulators seeking consistent quality across regions.
-
Shiva Pharmachem and Transpek Industry (India) — Regional players delivering cost-competitive acid chloride streams and catering to local and export markets; they are attractive for customers optimizing landed cost with acceptable lead-times and requiring adaptable batch sizes for intermediates.
-
Wilmar International (Singapore) — An oleochemicals specialist with product offerings positioned for organic peroxide manufacture and agricultural intermediates. Wilmar’s feedstock integration strengths provide alternative sourcing options, particularly in markets where oleochemical supply chains reduce exposure to petrochemical price cycles.
Recent company-level development to note
March 2026: BASF announced that its Intermediates division now produces its acid chloride portfolio at Ludwigshafen using renewable electricity credits and commercialises biomass-balanced (BMBcert) variants. This initiative is one concrete example of how sustainability investments are moving from marketing to production reality — and why procurement teams should assess supplier certification pathways and traceability now rather than later.
Strategic recommendations for 2026 decision-makers
-
Embed feedstock volatility into contracts: use hybrid price-indexation clauses tied to feedstock acid indices and define clear pass-through mechanics to protect margins while keeping supply committed.
-
Pursue supplier diversification with capability overlays: pair at least one large, certified global supplier for sustainability and logistics certainty with one technical-specialist supplier for bespoke intermediates and rapid formulation support.
-
Prioritise certified mass-balanced product lanes: where customers or regulations expect decarbonisation evidence, having BMBcert-capable suppliers reduces contract friction and accelerates product approvals in downstream procurement cycles.
-
Invest in logistic robustness: mitigate hydrolysis and HCl incident risk through improved secondary containment, enhanced packaging protocols, and regional warehousing to reduce transit exposures.
-
Calibrate capacity decisions to scenarios: defer greenfield capacity expansions unless anchored by long-term offtake agreements. Instead, consider tolling, contract-manufacturing, or JV structures to capture upside without full upstream capital exposure.
-
Screen M&A targets quantitatively: use the report’s supplier scorecards to set thresholds on technical capability, certification readiness, and margin accretion potential — not just headline capacity.
How to use this preview — and where to get the full playbook
This article provides a strategic scaffold for 2026 planning, illustrating the forces shaping supply, pricing, regulation, and sustainability preferences in the Isononanoyl Chloride market. It intentionally omits full subsegment breakdowns, regional application tables, and supplier-specific volume shares that are central to transaction diligence and tactical sourcing. PW Consulting’s full report contains those high-resolution datasets, including:
-
Region-by-region demand and price curves, with reforecast scenarios keyed to feedstock price regimes
-
Application-level segmentation and margin maps for organic peroxide, agrochemicals, lubricants/surfactants, and pharmaceutical intermediates
-
Supplier-specific scorecards and single-point failure risk indices for supply continuity planning
-
Operational templates: SLA language, HSE checklists, and contract annexes for mass-balanced delivery verification
For boards, procurement heads, and corporate development teams preparing strategic moves in 2026, the difference between an opportunistic outcome and a defensible one will be the quality of forward-looking, operationally relevant intelligence. PW Consulting’s full Worldwide Isononanoyl Chloride Market report is engineered to provide exactly that: a tactical, data-driven foundation for decisions that matter.
For detailed analysis of this topic, please visit the official page: Worldwide Isononanoyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com