

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: E1422 Food Additive Market Poised for Robust Expansion — 5.42% CAGR Projected Through 2026–2032
By pmarketresearch, 2026-07-13
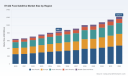
Worldwide E1422 Food Additive Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive summary
As food manufacturers and ingredient suppliers prepare budgets and strategic plans for 2026, acetylated distarch adipate (E1422) is re-emerging as a tactical lever for product differentiation, cost control and supply-chain resilience. PW Consulting’s Worldwide E1422 Food Additive Market study (base year 2025) identifies a stable, mid-single-digit growth profile for the market, backed by rising demand in processed food segments and ongoing product innovation from major starch converters. From 2020 through 2025 the market expanded steadily, and our forecast through 2032 projects continued growth at a compound annual growth rate of 5.42%, culminating in a materially larger market by the end of the forecast horizon.
Worldwide E1422 Food Additive Market
Why this preview matters for 2026 decision-makers
- Procurement & cost management: Volatility in tapioca and corn feedstock pricing is already affecting unit economics for modified starches. Early 2026 spot observations indicate upward pressure that will influence raw-material sourcing, contract strategies and pass-through pricing in downstream food production.
- Product development & reformulation: Clean-label aspirations, frozen applications with tougher freeze-thaw performance, and high-temperature/shear tolerant systems are driving formulators toward specific E1422 variants. Suppliers are responding with purpose-built SKUs for frozen dough and bakery segments — a trend that will shape 2026 launches.
- Regulatory & risk oversight: E1422 remains an approved modified starch in major regulatory regimes, with JECFA classifying its acceptable daily intake as “not specified.” A recent EFSA data call and ongoing assessments require companies to refresh compliance dossiers and monitor potential changes in labeling or purity expectations.
- M&A and capacity planning: The market’s moderate concentration profile and heterogeneous supplier landscape mean targeted asset plays and capacity expansions can materially affect supply dynamics in specific geographies and applications.
Macro view: market scale and trajectory
PW Consulting’s dataset traces the market from 2020 through 2025 and projects forward to 2032. The market has shown resilient expansion through the historical period and is forecast to maintain growth into the next planning cycle, reflecting steady demand from sauces, dairy, frozen foods, bakery and convenience segments, as well as continued adoption by global CPG formulators. Our forecast model (2026–2032) embeds a 5.42% CAGR and scenarios that stress-test raw-material shocks, regulatory headwinds and accelerated clean-label adoption.
Worldwide E1422 Food Additive Market
What the full report delivers — practical, board-ready intelligence
The PW Consulting market study is designed for commercial, R&D and corporate-development teams that must make 2026-capex and portfolio decisions under uncertainty. Key deliverables include:
Worldwide E1422 Food Additive Market
- High-resolution market model: annual market sizing and demand drivers with deterministic and probabilistic scenarios for 2026–2032.
- Pricing & cost ladder: bottom-up cost build-ups for common feedstocks and conversion routes, plus sensitivity analyses on tapioca and maize price swings.
- Application roadmaps: prioritized use-cases (sauces, dairy, frozen/convenience, bakery/confectionery and meat processing), formulation levers, and barrier-to-entry profiles for each application cluster.
- Supplier scorecards: comparative assessment of leading producers across technical capability, geographic footprint, compliance certifications, capacity and new-product pipelines.
- Commercial playbooks: go-to-market options for ingredient companies and CPGs — ranging from co-development agreements and preferred-supplier contracts to tolling and backward integration.
- M&A & portfolio diagnostics: screens to identify acquisition targets and greenfield locations that improve margin capture or mitigate supply risk.
- Regulatory watch-list and stakeholder map: actionable monitoring plan for EFSA/JECFA developments and country-specific labeling/impurity expectations.
Competitive landscape — who matters and why
The E1422 supplier base is a mix of global ingredient majors, regional starch processors and specialist manufacturers. Market concentration is moderate, with the leading three and five suppliers capturing an influential share of industry revenues — an important consideration when evaluating bargaining power and potential supply disruptions.
- Ingredion Incorporated (United States) — Strengths: broad ingredient portfolio, technical application labs and targeted product development (notably a 2025 launch for frozen-dough optimized E1422). Strategic implication: Ingredion’s R&D cadence and global sales network make it a preferred partner for multi-market reformulations and private-label co-development.
- Tate & Lyle PLC (United Kingdom) — Strengths: focused product lines for bakery and dairy, and recent European capacity expansion announced in late 2025 aimed at corn-based E1422 to meet rising bakery demand. Strategic implication: Tate & Lyle is positioning to capture growth in high-margin bakery segments and to serve customers seeking consistency at scale.
- Roquette Frères (France) — Strengths: specialized waxy corn E1422 lines engineered for thermal and shear stability with strong acceptance in sauces, soups and dairy desserts. Strategic implication: Roquette’s product depth provides a competitive edge in formulations requiring high process tolerance.
- Cargill, Incorporated (United States) — Strengths: diversified feedstock capability (maize, waxy maize, tapioca) and global distribution. Strategic implication: Cargill’s scale and feedstock optionality make it a resilient counterparty under commodity stress.
- AGRANA Beteiligungs-AG (Austria) — Strengths: targeted product series for condiments and convenience foods. Strategic implication: AGRANA is attractive for co-manufacturers focused on specialty condiment and convenience applications.
- Regional and specialty suppliers (Vietnam, India, China) — Examples include Golinse, Landschaft Food Products, Spark Starch, Qingdao Doeast and Kosnature. Strengths: localized cost positions, certifications (HACCP, Halal, Kosher, FSSC) and flexibility on small-batch customizations. Strategic implication: These players are valuable for regional sourcing, cost-competitive spot supply and certification-driven market entries, but buyers should validate consistency and scale before shifting critical volumes.
Recent developments shaping 2026 strategy
- Tate & Lyle’s 2025 European capacity expansion targets the bakery channel and clean-label formulations — a direct response to elevated bakery demand and processing tolerance requirements.
- Ingredion’s 2025 launch of a frozen-dough optimized E1422 underscores ingredient innovation focused on freeze-thaw resilience — a priority for manufacturers of frozen and convenience foods.
- Feedstock supply signals in early 2026 show upward price pressure on tapioca (spot ranges with short-term spikes), creating near-term margin stress for tapioca-dependent converters and opportunity for corn- or potato-based alternatives.
- Regulatory monitoring continues: E1422 maintains approvals under major frameworks, while EFSA’s re-evaluation processes emphasize the need for updated dossiers and traceability documentation.
Strategic recommendations for 2026 (practical next moves)
- Hedge raw-material exposure: move from tactical spot buying to hybrid contracts (partial fixed-price + index-linked) tailored to projected throughput and storage constraints.
- Prioritize supplier diversity: qualify at least two alternative suppliers across feedstocks and geographies for critical SKUs to reduce single-source risk.
- Accelerate formulation workstreams: invest in application-specific trials (especially frozen dough and high-acid sauces) to capture white-space created by new E1422 grades on the market.
- Align commercial strategy with capacity shifts: where supplier expansions target your segment, reassess preferred-supplier negotiations to capture volume leverage and improved lead times.
- Embed regulatory hedges: update compliance dossiers, ensure traceability for modified-starch inputs and maintain direct lines to suppliers’ regulatory affairs teams.
- Use M&A tactically: prioritize bolt-on acquisitions that add missing feedstock capability, geographic reach or technical lab capacity rather than broad scale plays.
How PW Consulting’s report supports board-level decisions
The full study is structured to move teams from insight to action rapidly: editable financial models, supplier procurement scorecards, scenario simulations and a playbook for reformulation prioritization are included. Clients use the report to set 2026 procurement budgets, define product roadmaps, evaluate capital allocation for plant investments and screen acquisition targets with transparent valuation levers tied to E1422 demand projections.
Methodology note & limited disclosure
PW Consulting combines primary interviews, proprietary shipment and pricing datasets, and validated public filings to produce its market sizing and forecast. In this preview we intentionally display high-level market scale, growth trajectory and strategic implications while omitting granular regional, source- and application-level splits. This “trailer” approach demonstrates analytical depth and commercial relevance; the full report contains the detailed segmentation tables, company-level share estimates, and downloadable models that procurement, R&D and corporate-development teams require to implement the recommendations outlined above.
Next steps
For executives planning 2026 capex, procurement and product launches, the full Worldwide E1422 Food Additive Market report provides the actionable intelligence and modeling assets needed to translate market signals into defensible decisions. Contact PW Consulting to arrange a brief walkthrough of the report and receive the dataset and supplier scorecards that correspond to your specific region and application priorities.
For detailed analysis of this topic, please visit the official page: Worldwide E1422 Food Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cryogenic Lasers Market Poised for Robust 9.0% CAGR
By pmarketresearch, 2026-07-13
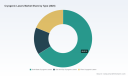
Worldwide Cryogenic Lasers Market — Strategic Outlook for 2026: Navigating Opportunity, Supply Volatility, and Competitive Consolidation
PW Consulting’s latest market study, Worldwide Cryogenic Lasers Market (base year 2025; historical window 2020–2025; forecast 2026–2032), delivers the strategic intelligence executives need to make high‑stakes decisions in 2026. Our analysis synthesizes historical momentum, technology inflection points and supplier economics to produce a forward-looking playbook: the market is entering a phase of accelerated commercialisation, with macro demand growing at a projected compound annual growth rate (CAGR) of 9.0% across the 2026–2032 forecast horizon.
Worldwide Cryogenic Lasers Market
High-level market trajectory
From a base market size of USD 279.22 Million in 2025, our model anticipates measurable expansion in 2026 and across the forecast period, with the total market expected to rise to roughly USD 510.41 Million by 2032 under the central case. That trajectory reflects a combination of steady capital expenditure in research institutions, increased industrial adoption for precision material processing, and nascent but rapidly maturing demand from quantum technology and specialized medical applications.
Worldwide Cryogenic Lasers Market
Why 2026 is a strategic inflection point
- Commercial readiness meets macro tailwinds. The past five years (2020–2025) saw prototype performance breakthroughs and demonstrable reliability improvements. Entering 2026, several system architectures cross the threshold from lab validation to repeatable factory production runs, enabling OEMs and integrators to plan two- to three‑year product roadmaps with realistic launch timelines.
- Capital availability for deep-tech deployment. Investment appetite for enabling technologies—particularly those that underpin quantum computing and advanced micro‑machining—has strengthened. Our scenario work shows that even conservative capital deployment rates materially affect addressable market size over the forecast.
- Regulatory and safety framing that supports adoption. U.S. and international safety frameworks—specifically OSHA guidelines on laser hazard assessment and FDA/ CDRH Federal Laser Product Performance Standard (FLPPS) requirements for emission classification and labeling—are increasingly integrated into procurement checkpoints, shortening qualification cycles for compliant products.
Supply-side dynamics and near-term risks
- Cryogens and raw material volatility. The cryogenic lasers ecosystem is sensitive to input markets. In Q1 2025 helium reached record high spot levels (reported in the sector around USD 97,200–117,660 per metric ton) before a correction in H2 2025 following new production ramps in South Africa, the United States and Russia. That episode exposed procurement concentration risks and the lead‑time sensitivity of long‑term helium contracts.
- Pressure on component and fabrication costs. Cryogenic systems rely on stainless steels and specialized alloys; swings in metal prices and spot shortages can erode margins. We observed increased gray‑market activity for components during 2024–2025, highlighting the need for validated supplier networks and tighter procurement governance.
- Regulatory compliance as a gating factor. Compliance with OSHA and FDA/ CDRH expectations—particularly for Class IV systems and non‑beam hazards arising from cryogens or cooling infrastructure—is a material gating factor for market access in major geographies. Early investment in compliance documentation shortens sales cycles and supports premium positioning.
Competitive landscape — consolidation, specialization, and new entrants
The market is moderately concentrated: the top three players account for approximately 42.5% of market share (CR3), while the top five represent roughly 58.8% (CR5). This concentration underpins two strategic realities—technology leadership is a differentiator, and there remains room for specialist vendors and partnerships that target narrow high‑value applications.
Worldwide Cryogenic Lasers Market
- Advanced Photonic Sciences (APS Lasers) — United States. APS has established reputational leadership through sustained performance records in cryogenic laser benchmarks, including high average continuous‑wave powers and picosecond pulse energies. Their strengths lie in deep physics competency, module‑level productisation and a track record of moving lab‑grade capabilities into repeatable product lines—qualities that favor strategic customers seeking best‑in‑class performance for scientific and quantum workloads.
- Coherent Inc. — United States. As a global photonics incumbent, Coherent brings scale, channel reach and systems integration expertise. Its broad portfolio and established relationships across industrial, scientific and medical buyers make it a pivotal partner (or competitor) for platform playbooks that integrate cryogenic cooling with broader laser subsystems.
Across the vendor ecosystem we observed three business models gaining traction: (1) high‑performance niche providers that compete on physics and bench performance; (2) systems integrators that prioritise turnkey capability and regulatory compliance; and (3) component suppliers that enable cost reduction through modularisation and scale manufacturing.
What the PW Consulting report delivers (practical, executable content)
Our report is designed as an operational toolkit—structured to support procurement directors, R&D leaders, BD and corporate development teams as they build 12–36 month plans. Key deliverables include:
- Actionable market sizing and validated demand scenarios (base, upside, downside) for 2026–2032, with sensitivity analyses tied to helium availability, metal price trajectories and regulatory adoption rates.
- Technology radar and readiness matrix that compares architectures (solid‑state, fiber, gas/dye and hybrid cryogenic approaches) against KPIs meaningful to buyers: beam quality, average power, pulse energy, system MTBF and total cost of ownership.
- Vendor profiles and commercial scorecards (including financial robustness proxies, IP positioning and integration capabilities) to support short‑lists and due‑diligence prioritisation.
- Procurement playbooks—contract structures, hedging strategies for cryogen supply, and validated vendor risk assessment templates—that reduce single‑sourced exposure.
- Regulatory compliance checklist and certification timelines by jurisdiction to accelerate product approvals and procurement clearances.
- M&A and partnership opportunity maps identifying pockets of consolidation, tuck‑in targets and strategic OEM partners across the value chain.
- Scenario‑based pricing and ROI calculators enabling buyers to compare cryogenic solutions against conventional laser options on productivity, yield, and lifecycle cost metrics.
Strategic imperatives for 2026 decision‑makers
- Hedge supply; institutionalise procurement resilience. Negotiate multi‑year cryogen contracts with staggered delivery windows, qualify alternative cryogens where feasible, and maintain dual or triple sourcing for critical components. Short episode shocks (like the 2025 helium spike and later correction) can materially affect production economics; prudent hedging reduces revenue volatility.
- Prioritise regulatory readiness early. Build compliance activities into development sprints. For customers targeting regulated markets (medical devices, some industrial safety domains), certification timelines must be front‑loaded to avoid go‑to‑market delays that erode first‑mover advantage.
- Choose product strategy by use‑case economics. Where floor‑area adoption is driven by throughput and yield (advanced material processing), total cost of ownership and productivity uplift should guide architecture selection. For quantum and research customers, performance and stability are the primary purchase criteria even at higher unit costs.
- Pursue modularisation and manufacturability. Vendors that package cryogenic sub‑systems into repeatable, serviceable modules unlock faster deployments at lower field‑service cost. Investors should favour companies demonstrating clear roadmaps to scalable manufacturing and component standardisation.
- Explore targeted M&A and strategic partnerships. Given the mid‑level concentration of the market, strategic acquisitions or collaboration agreements—especially between component specialists and systems integrators—create rapid capability lifts and route‑to‑market synergies.
- Invest selectively in IP and talent. Physics‑heavy domains demand specialist R&D teams. Locking in IP around cooling architectures, hermetic packaging and beam management yields durable protective moats.
How to use this intelligence in 2026 planning cycles
Procurement planners should use our scenario outputs to stress‑test annual sourcing budgets. R&D leaders can prioritise projects using the technology readiness and ROI matrices included in the report. Corporate development teams should map M&A targets against the opportunity maps and concentration analytics to determine whether to pursue bolt‑on acquisitions or platform investments. Finally, operations and supply‑chain leaders must run the included supply‑stress simulations to quantify inventory buffering needs and supplier diversification thresholds.
Conclusion — the decision window is now
The cryogenic lasers market stands at a commercial pivot: technical progress, rising application demand and clearer regulatory frameworks create tangible opportunities for companies that prepare strategically in 2026. The choices made this year—about supplier risk, product architecture, regulatory investments and inorganic moves—will determine which players capture the premium segments of a market projected to approximately double in size by 2032 under our central forecast.
PW Consulting’s Worldwide Cryogenic Lasers Market report provides the empirical foundation and tactical instruments for those choices. For full segmented data, vendor scorecards, scenario models and downloadable decision tools, visit our report page or contact our industry team to request the comprehensive dataset and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Cryogenic Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Single Axis Automatic Tapping Machine Market to Grow from USD 478.36M in 2025 to USD 666.85M by 2032 at a 4.86% CAGR
By pmarketresearch, 2026-07-13
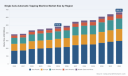
Strategic Outlook — Worldwide Single Axis Automatic Tapping Machine Market: A 2026 Decision Framework
PW Consulting’s latest market study on the Worldwide Single Axis Automatic Tapping Machine Market provides an actionable intelligence package tailored for executive teams planning capital allocation, sourcing, product strategy, and M&A activity in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the global market reached roughly USD 478 million in 2025 and is projected to expand at a steady mid-single-digit CAGR (around 4.9%) through 2032, reflecting a trajectory toward higher automation penetration across precision machining segments. This briefing highlights the report’s strategic value — enough depth to guide near-term decisions while reserving the granular segmentation tables and proprietary scorecards for the full report.
Worldwide Single Axis Automatic Tapping Machine Market
Why the 2026 Planning Horizon Is Critical
-
Capital cycles and procurement windows: Many OEMs and contract manufacturers set major CapEx decisions on two- to three-year cycles. 2026 is the inflection point for firms that deferred automation in the earlier recovery years; delaying decisions now risks longer lead times and missed productivity gains.
Worldwide Single Axis Automatic Tapping Machine Market -
Cost and supply-chain dynamics: Raw material pricing and lead-time normalization are creating an environment where equipment total cost of ownership (TCO) can be locked in more predictably — an important input to ROI calculations for automatic tapping investments.
Worldwide Single Axis Automatic Tapping Machine Market -
Workforce & productivity imperatives: Persistent skilled-labor shortages across machining and automation are accelerating adoption of automatic tapping solutions as a labor-mitigation and quality-control lever.
What the PW Consulting Report Delivers — Practical, Decision-Grade Insights
-
Robust market sizing and forward-looking scenarios: global market totals and a detailed forecast model that supports sensitivity testing against different demand and price assumptions.
-
Demand-driver diagnostics: quantifies the influence of end-market recoveries (e.g., automotive, electronics, general machinery, aerospace) and highlights which application classes are most likely to accelerate capex in 2026–2028.
-
Technology and product roadmaps: comparative analysis of electric, pneumatic and hydraulic single-axis tapping architectures with pragmatic guidance on when each architecture delivers the best TCO and cycle-time benefits without disclosing proprietary share metrics.
-
Supplier benchmarking and procurement playbook: a scored assessment of leading suppliers (product breadth, after-sales network, customization capability, and lead-time profile), tender playbooks, contract clauses to protect buyers, and spare-parts strategies.
-
Operational deployment templates: line-integration checklists, retrofit vs replace decision matrices, footprint and utility planning, and training curricula to accelerate uptime post-installation.
-
M&A and partnership intelligence: identification of target classes for bolt-on acquisitions or JV partnerships, prioritized by strategic fit and execution risk.
-
Data deliverables: an interactive Excel model, factory audit checklists, and a vendor feature-comparison matrix to accelerate procurement and engineering evaluation cycles.
Competitive Landscape — Reading Today’s Leaders
The market remains commercially active and technologically diverse: Japanese precision incumbents, scale-focused Chinese manufacturers, and specialist Western vendors coexist, each with distinct strategic plays. PW Consulting’s fieldwork examined product portfolios, factory capabilities, recent launches, and trade-show activity to infer strategic direction without disclosing proprietary market shares.
-
Sugino Machine Limited (Toyama Prefecture, Japan) — a technology-led player offering servo-feed drilling/tapping units and compact automatic stands. Recent trade-show participation underscores a continued emphasis on high-precision, modular single-unit automation and aftermarket support for high-mix manufacturers.
-
Hoporo Group (Ningbo, China) — positions on cost-competitive, dual-servo head designs with operator-friendly HMI and PLC integration. Their product focus signals a push to capture mid-volume assembly lines where cycle time and simplicity are the primary buyer criteria.
-
Zhejiang Shuangshi Machinery (Wenzhou, China) — leverages gear-type mechanisms for pitch accuracy and stability, with recent new-model introductions aimed at customers prioritizing repeatability under continuous operation.
-
Zhejiang Desheng Intelligent Equipment (Yueqing, China) — targets the electronics and precision metal-parts sectors with automated feeding systems and in-line debris management; their configuration choices reflect an emphasis on high-throughput, low-defect environments.
-
Dongguan Zhi Heng and Ningbo Bysen — both offer configurable single-axis platforms (servo and pneumatic variants) and emphasize quick-change tooling, alarm/interruption safeguards, and straightforward integration to minimize line disruption.
-
Kawai Machinery (Japan) and AutoDrill (United States) — smaller, specialist suppliers that compete on customization, short-run flexibility, and strong local service presence for customers requiring tight integration with existing cellular machining lines.
Strategic takeaway: buyers should evaluate vendors not only on unit price and cycle time, but on systems thinking — spare parts availability, service SLAs, control-system openness for Industry 4.0 integration, and retrofit capabilities.
Supply Chain & Cost Dynamics Shaping Supplier Strategy
-
Raw materials: international steel costs entered a trough in early 2026, and iron-ore price pressure is expected to ease supply-cost volatility near-term. For buyers, this window offers an advantageous time to lock equipment orders and negotiate favorable lead times.
-
Labor shortages: acute scarcity of skilled machinists and automation technicians is driving automation adoption. Suppliers that offer stronger commissioning packages and remote-diagnostic capabilities will capture outsized share gains among customers with labor constraints.
-
Digitization trend: AI-enabled monitoring and predictive maintenance are emerging as differentiators. Equipment that exposes clean telemetry with open APIs reduces integration friction and enables service models that extend lifetime value.
Portfolio & Go-to-Market Implications for OEMs and Suppliers
-
For OEM buyers — prioritize modular platforms that scale across product families: standardized automation nodes reduce engineering overhead and cut time-to-market for new lines.
-
For suppliers — invest selectively in digital services and global spare-parts distribution. Those who can bundle uptime guarantees with remote-support subscriptions will generate higher-margin, recurring revenue streams.
-
For private equity and corporate development teams — look for consolidation opportunities among regional suppliers with complementary channels or proprietary hardware/software integrations; prepare to value synergies from aftermarket scale rather than pure equipment sales.
Actionable Recommendations for 2026 Decision-Makers
-
Accelerate feasibility studies for line-level automation where labor and defect reduction yield the fastest payback; use the report’s ROI templates to model CapEx scenarios under different utilization and yield assumptions.
-
Negotiate equipment contracts with indexed raw-material pass-through clauses and capped lead-time penalties to insulate against supplier disruptions while benefitting from current cost troughs.
-
Require open-control architectures and telemetry readiness in new purchases to avoid vendor lock-in and preserve long-term value from digitization initiatives.
-
Prioritize vendors with strong aftermarket ecosystems or the willingness to co-invest in service infrastructure; short-term discounts on machinery can be outweighed by long-term downtime costs if service is weak.
-
Build a five-year spare-parts and obsolescence plan into procurement to avoid escalation of replacement costs as product lines evolve.
How to Use the Full PW Consulting Report
The complete report includes: granular segmentation tables (regional and application splits), vendor scorecards with qualitative and quantitative measures, scenario-ready forecast models, and an actionable procurement toolkit. Because strategic execution requires both the headline view and the underlying data, PW Consulting intentionally reserves the detailed segment matrices and vendor scoring algorithms for the full download — they are designed to plug directly into CFO, procurement and operations planning cycles.
For 2026 planning cycles, the report acts as both a reference and a playbook: it converts market trends into procurement tactics, supplier negotiation levers, product development priorities, and acquisition criteria. PW Consulting’s field interviews with OEMs and suppliers, plus in-factory audits and a dynamic Excel model, mean the study is ready for decision-makers who need to act this year.
Next Steps
-
Executive teams: use the report’s ROI and scenario tools to prioritize near-term CapEx approvals.
-
Procurement leaders: apply the supplier scoring framework during tender windows to reduce integration and service risk.
-
Corporate development: contact PW Consulting for a tailored shortlist of targets and a confidential valuation overlay using the study’s dataset.
PW Consulting’s Worldwide Single Axis Automatic Tapping Machine Market report synthesizes market sizing, supplier intelligence, technology trends and operational playbooks into a single resource designed to shorten decision cycles and increase the probability of successful automation investments in 2026. For access to the complete segmentation tables, vendor scorecards, and the interactive forecast model, please download the full report from PW Consulting’s official release.
For detailed analysis of this topic, please visit the official page: Worldwide Single Axis Automatic Tapping Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Duvelisib Capsule Market to Expand Nearly 2.6-Fold — From USD 72.15 Million in 2025 to USD 190.72 Million by 2032 at a 14.88% CAGR
By pmarketresearch, 2026-07-13
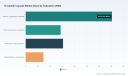
Worldwide Duvelisib Capsule Market: Strategic Imperatives for 2026 — A Preview of PW Consulting’s In-Depth Analysis
PW Consulting’s forthcoming Worldwide Duvelisib Capsule Market report provides senior leadership and deal teams with an evidence-based roadmap for high-stakes decisions in 2026. The duvelisib capsule market has demonstrated sustained expansion through the early 2020s and is projected to continue a rapid upward trajectory, rising from an estimated global market of USD 72.15 Million in 2025 to roughly USD 190.72 Million by 2032 — a compound annual growth rate (CAGR) of approximately 14.88% over the forecast horizon. This press release is a strategic preview designed to convey the report’s operational value while reserving the granular segment-level intelligence for report subscribers.
Worldwide Duvelisib Capsule Market
Why 2026 Is a Pivotal Year for Sponsors, Payers and Investors
Several converging forces make 2026 a decision-inflection point for companies in the duvelisib ecosystem. First, the overall market momentum is strong and sustained, reflected in multi-year market expansion from the mid-2020s into the next decade. Second, regulatory and guideline events in late 2025 materially altered the commercial and clinical landscape — changes that will influence reimbursement, label strategy, and physician adoption curves entering 2026. Third, market concentration is unusually high, with the top-tier competitors controlling a dominant share of revenue, amplifying the importance of targeted, differentiated strategies for newer entrants or adjacent-therapy incumbents considering life-cycle or line-extension plays.
Worldwide Duvelisib Capsule Market
Core Report Deliverables — What Executives Will Find Inside
- Comprehensive market sizing and probabilistic forecasting through 2032 that integrates historical performance (2020–2025) with scenario analysis to stress-test outcomes based on regulatory and clinical developments.
- Regulatory and guidelines mapping that tracks REMS modifications, boxed warnings, accelerated approval histories, and guideline placement — with explicit implications for label strategy, field force deployment, and risk communications.
- Competitive landscape profiles and go-to-market playbooks. These include capability matrices, commercialization footprints, and tactical recommendations for payer and KOL engagement tailored to different market entry routes.
- Clinical development and pipeline assessment, including late-phase should-win/lose scenarios, competitive trial readouts, and cross-therapy interactions that could accelerate or blunt uptake.
- Reimbursement and access frameworks, aligning NCCN positioning and payer decision levers with practical contracting and HCP education strategies to maximize formulary positioning while mitigating safety-related objections.
- Operational advisories covering manufacturing scale, supply chain resiliency, pricing architecture, and risk mitigation for REMS-driven distribution constraints.
- M&A and partnership opportunity mapping with prioritized targets and valuation sensitivities for buyers and licensors looking to enter or consolidate position in the duvelisib capsule market.
Key Strategic Insights
- Market growth is robust but nuanced. The overall market is expected to more than double from the mid-2020s to the early 2030s under the central forecast. That pace creates windows for revenue acceleration, but also amplifies the costs of misaligned regulatory or commercial strategies.
- High concentration favors incumbents. With the market controlled by a small number of players, new entrants face an access and awareness gap that requires disproportionate investment in differentiation and payer evidence generation.
- Safety and REMS define the go-to-market calculus. Ongoing and recent regulatory actions (including REMS maintenance and updated boxed warning language) materially affect prescriber confidence, hospital credentialing, and managed care coverage policy. Sponsors must build integrated risk communication and monitoring programs as a core component of any launch or life-cycle plan.
- Guideline movements unlock reimbursement pathways. Placement in disease guideline compendia can catalyze adoption and reimbursement — the late-2025 guideline updates that supported broader clinical use highlight how a single consensus change can materially shift payer openness and clinic-level uptake.
- Clinical differentiation remains the most durable lever. Meaningful, durable responses in specific subpopulations and favorable safety profiles in later-stage trials will be decisive for expanding label claims and broadening the addressable market.
Competitive Spotlight: Secura Bio, Inc.
Secura Bio is the primary commercial steward of duvelisib in the United States and is central to the market’s near-term trajectory. The company’s recent regulatory and clinical milestones through 2025/early 2026 underscore the interplay of evidence generation, label evolution, and market access execution that will shape 2026 outcomes.
Worldwide Duvelisib Capsule Market
- Regulatory and label management: Secura Bio secured FDA approvals for supplemental labeling changes and REMS updates in 2025 that reflect heightened safety surveillance and refined communication plans. These updates both constrain and enable market activity — constraining through boxed warnings and limitations of use, while enabling broader, safer adoption via clearer risk mitigation protocols.
- Clinical developments: Secura Bio’s extended analyses from the Phase 2 PRIMO trial and ongoing Phase 3 TERZO program have delivered clinically relevant response signals in peripheral T‑cell lymphomas, including subgroups that historically have limited therapeutic options. These data points materially inform product positioning and the design of post-marketing evidence generation required by payers.
- Guideline traction: The inclusion of duvelisib in consensus treatment pathways for certain cutaneous T-cell lymphomas in late 2025 provides a tangible reimbursement enabler that could accelerate uptake in specialized centers — an important precedent for market-access teams working to expand coverage.
Regulatory and Payer Dynamics — Practical Implications
Decision-makers must reconcile two realities: first, duvelisib’s clinical utility in relapsed/refractory populations is supported by meaningful activity in hard-to-treat subtypes; second, safety considerations (including treatment-related mortality signals in longer follow-up datasets) mandate continued REMS oversight and conservative use limitations. For market-facing teams, this duality translates into specific priorities for 2026:
- Design and fund post-approval studies that explicitly address payer and clinician endpoints — long-term safety, real-world effectiveness, and quality-of-life measures will be differentiators in contracting conversations.
- Create integrated REMS-compliant distribution strategies that remove administrative friction for appropriate prescribers while demonstrating robust risk mitigation to payers and institutions.
- Engage guideline committees and specialty societies proactively: timely, high-quality real-world evidence can translate into favorable guideline positioning and improved reimbursement terms.
Operational and Commercial Recommendations for 2026
For industry leaders and investors preparing 2026 playbooks, PW Consulting’s analysis yields several prioritized actions.
- Prioritize subpopulation targeting. Identify subgroups where clinical differentiation and unmet need converge — concentrate early commercial resources on centers of excellence and KOL champions to build durable referral patterns.
- Align pricing with evidence-generation commitments. Structured contracting (e.g., outcomes-based arrangements) tied to post-market study deliverables can unlock payer coverage while sharing risk between sponsors and payers.
- Strengthen pharmacovigilance and REMS infrastructures. Investments here reduce clinical adoption friction and demonstrate to payers and regulators a credible safety-management capability.
- Consider M&A and licensing as strategic accelerants. Given the high market concentration, carefully selected partnerships or bolt-on acquisitions can secure access to distribution, complementary assets, or geographies more efficiently than greenfield launches.
- Operationalize manufacturing resilience. Given forecasted volume expansion, early capacity commitments and dual-sourcing strategies reduce supply risk and support large-account contracting.
Why PW Consulting’s Report Matters to Your 2026 Boardroom
Boards and executive teams face complex trade-offs in 2026: invest heavily to capture rapid market growth, or take a defensive posture while safety, guideline, and reimbursement dynamics play out. PW Consulting’s report translates the market’s macro trajectory — including a projected CAGR near 14.9% and a multi-fold increase in market size into the early 2030s — into actionable options that preserve optionality while targeting achievable commercial outcomes.
The report does not merely forecast revenue curves; it prescribes operating models, evidence strategies, and deal structures calibrated to a market characterized by high concentration and elevated regulatory oversight. For decision-makers, the most valuable outputs are the prioritized 12–24 month roadmaps that link evidence generation to commercial levers and the financial sensitivities that clarify where incremental spend yields disproportionate value.
Next Steps
This preview highlights key strategic conclusions from PW Consulting’s Worldwide Duvelisib Capsule Market report and explains why 2026 decisions will disproportionately shape long-term value creation. For the complete dataset, granular segmentation, and the full suite of tactical playbooks — including the proprietary scenario matrices, payer negotiation scripts, and an executable post-approval evidence plan — access the full report on PW Consulting’s website.
Contact PW Consulting to schedule a briefing with our lead analysts and receive a customized decision memo for your executive team. Our advisory team will walk you through the specific implications of the 2026 market inflection points and tailor recommendations to your organization’s risk profile and strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Duvelisib Capsule Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Public Address & Voice Alarm (PAVA) Market Set to Expand at 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Worldwide Public Address and Voice Alarm (PAVA) Systems: Strategic Imperatives for 2026
As organizations prepare strategic technology and safety investments for 2026, the PAVA (Public Address and Voice Alarm) systems market is presenting both predictable growth and disruptive inflection points. PW Consulting’s latest Worldwide PAVA Market report synthesizes market-sizing, regulatory shifts, technology trajectories, and vendor dynamics to equip executives with decision-grade insight. This briefing pulls forward the report’s strategic value—while preserving the granular subsegment data we reserve for the full report—so leaders can prioritize near-term actions and governance checkpoints for 2026.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Market Trajectory: A Solid Growth Engine
The global PAVA market has demonstrated steady expansion over the past half-decade, moving from an estimated USD 2,814.22 Million in 2020 to USD 3,748.80 Million in 2025. Our base-year analysis and forward projection show continued momentum, with 2026 positioned as a transition year into a multi-year growth phase. Over the 2026–2032 forecast horizon, we model a compound annual growth rate (CAGR) of 6.5%, reflecting sustained investment in safety-critical audio systems across built environments and transport nodes.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
What this means for 2026 planning: organizations should treat PAVA procurement and modernization not as discretionary refreshes but as strategic, funded programs tied to compliance, continuity, and occupant experience. The macro growth supports vendor investment in product lines (notably, IP-native and cloud-managed architectures), while also creating opportunity for differentiated service offerings from integrators and security-as-a-service providers.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Why This Report Matters to 2026 Decision-Makers
-
Actionable market sizing and scenario planning: We provide validated topline market estimates and scenario-driven forecasts that illuminate upside and downside pathways for budget cycles that start in H2 2025 and will be executed in 2026.
-
Regulatory and standards alignment: With EN 54-16, NFPA 72, and regionally relevant standards shaping procurement specifications, the report translates compliance obligations into product and vendor selection checklists—reducing specification risk during tender design.
-
Technology adoption and TCO playbooks: Our modeling contrasts centralized analog, distributed/hybrid, and IP-based deployments to illustrate total cost of ownership dynamics across lifecycle, maintenance, and upgrade pathways—this is essential for capital planning for 2026–2028.
-
Vendor and supplier execution maps: We synthesize vendor strengths, recent product developments, and route-to-market channel dynamics—helping procurement teams prioritize vendor panels and risk-mitigation clauses for 2026 contracts.
What’s Inside the Full Report (Practical Tools)
- Validated market sizing by year and high-level growth drivers (macro numerics and trend analysis are included; granular subsegment shares are available only in the full report).
- Scenario-based demand forecasts and sensitivity analysis tied to three adoption pathways: retrofit-led, new-build integration, and cloud-managed migration.
- Procurement-ready templates: RFP language mapped to EN and NFPA compliance, scoring rubrics, and installation cost drivers to reduce ambiguity in bids.
- Vendor scorecards and technology risk matrices focused on certification status, interoperability, cybersecurity posture, and service coverage.
- Deployment playbooks for high-risk environments: transportation hubs, healthcare, education, and industrial sites—covering design redundancies, intelligibility testing, and maintenance regimes.
- CapEx vs. OpEx modeling for cloud-managed vs. on-prem PAVA deployments, including lifecycle replacement scheduling and expected maintenance consumption points.
Competitive Landscape — Players to Watch
The PAVA vendor ecosystem blends established systems integrators and manufacturers with specialized vendors that target vertical niches. Among the firms we profile in detail are global engineering brands and specialist audio-safety vendors whose product portfolios and recent moves reveal the priorities for 2026 procurement:
- Bosch Security Systems (Germany) — Notable for its Plena and Praesensa IP-native platforms, with recent firmware updates that enhance integration into smart-building ecosystems.
- TOA Corporation (Japan) — Strong IP-Network product lines positioned for large venues and transport hubs, and recent certification wins that reduce procurement friction.
- Honeywell International (USA) — Integrates PAVA into broader building and fire safety suites, advancing cloud-managed voice evacuation capabilities.
- Zenitel / Vingtor-Stentofon (Norway) — Specializes in high-reliability IP intercom and PAVA solutions for maritime and public-safety use cases.
- Biamp, RCF, AtlasIED, TOA, Baldwin Boxall, and other specialists — Each provides differentiated strengths across IP paging, evacuation, voice intelligibility, and certification footprints suitable for targeted verticals.
Notably, recent product and certification activities—from firmware refreshes to EN 54 certifications and maritime feature showcases—underscore vendor investment in interoperability and compliance. These developments accelerate procurement velocity in markets where certification is a gating criterion for deployment.
Regulation and Standards: Market Shapers
Compliance remains a primary driver of PAVA demand. EN 54-16 continues to define performance for voice alarm control in parts of Europe, while NFPA 72 is materially influencing specification requirements in North America—particularly intelligibility metrics for large assembly occupancies. Complementary standards, such as the BS 5839 family for VoIP-based emergency communications, create regional nuances organizations must reconcile in multi-jurisdiction deployments. Additionally, changes in UL standards for mass notification have shifted how suppliers frame compliance and certification narratives.
For procurement teams, the practical implication is two-fold: include standards verification as mandatory pass/fail criteria in tenders and insist on documented verification processes (e.g., speech intelligibility testing under occupied conditions) as contract deliverables.
Cost and Operational Dynamics
Installation economics continue to be a significant factor. Our analysis confirms that cabling and connectivity remain a material portion of installation cost—copper runs in large venues can constitute a notable share of on-site spend. That reality drives interest in strategies that reduce cabling intensity: fiber backbone designs, localized amplification, power-over-Ethernet approaches, and selective wireless links for non-critical ancillary systems.
Lifecycle service and remote management are emerging as competitive differentiators. Vendors offering cloud-managed monitoring, remote diagnostics, and software update pipelines reduce mean time to repair and can shift parts of maintenance spend from capex to predictable opex—an attractive shift for many facility management organizations budgeting in 2026.
Strategic Priorities for 2026
-
Embed compliance-first procurement: Require explicit EN/NFPA/BS conformance evidence and include speech intelligibility as a contractual KPI. For multi-site operators, mandate third-party verification of standards compliance at a representative sample of sites.
-
Prioritize IP-native architectures where lifecycle and integration benefits outweigh near-term capex increases. IP systems improve remote manageability and can converge with building management and security networks, but must be evaluated for cybersecurity and latency.
-
Pursue staged modernization: For owners of legacy analog systems, adopt a phased upgrade approach that targets critical zones first (e.g., assembly points and control rooms) and preserves investment through interoperable gateways.
-
Reduce cabling risk exposure: Re-evaluate specs that presuppose long copper runs; design appendices for fiber, amplifier distribution strategies, and loop-based architectures that reduce installation cost and schedule risk.
-
Engage vendors on lifecycle SLAs: Negotiate software-update cadences, cybersecurity responsibilities, and spares provisioning up-front to avoid unbudgeted refresh cycles during 2026–2028.
-
Test cloud-managed service economics: Run pilot projects that quantify the operational savings from remote monitoring, reduced site visits, and subscription-based management—these pilots should feed 2027 budget cycles.
How to Use the Report in Your 2026 Planning Cycle
- IT and Security Heads: Use the vendor scorecards and cybersecurity checklists to validate network segmentation and patching obligations before signing multi-site agreements.
- Procurement and FM Leaders: Adopt the RFP templates and cost-model worksheets to align CAPEX approvals with ongoing OPEX commitments tied to cloud services.
- CEOs and CFOs: Leverage the scenario forecasts and ROI matrices to prioritize projects that deliver compliance and continuity benefits while optimizing capital deployment.
Final Note — A Strategic Teaser
PW Consulting’s Worldwide PAVA Market report offers the granular dashboards, subsegment forecasts, and vendor scorecards that executive teams need to make defensible 2026 investments. In keeping with our “trailer” approach, this release highlights the market’s direction, regulatory inflection points, vendor moves, and recommended strategic plays—while detailed subsegment tables, regional splits and the complete vendor benchmarking matrix are reserved for the full report. For teams ready to convert market insight into procurement action plans, the full dataset and downloadable decision tools are available on our website.
2026 will be a pivotal year for organizations balancing safety compliance, networked systems strategy, and total cost of ownership. The choices made now—on architecture, standards compliance, and vendor governance—will set a 5–7 year trajectory for resilience and occupant safety. PW Consulting’s report is designed to make those choices clear, measurable, and executable.
For detailed analysis of this topic, please visit the official page: Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Press-on-Nails Market to Reach USD 2.37 Billion by 2032, Sustaining a 5.92% CAGR in 2026–2032
By pmarketresearch, 2026-07-13
Worldwide Press‑on Nails Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Press‑on Nails market surfaces the commercial priorities that will define success in 2026 and beyond. The sector has matured from a niche, DIY category into a resilient consumer beauty segment with clear commercialization pathways—from mass retail and private label to premium, tech‑enabled offerings. Our analysis shows the global market reached approximately USD 1,584 million in the report base year (2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.92% through 2032, approaching the USD 2.4 billion mark under the base scenario. This trajectory reflects both expanding household penetration and meaningful product innovation cycles.
Worldwide Press on Nails Market
Why this report matters to boards and executive teams in 2026
For strategy, corporate development, product and operations leaders, the press‑on nails category represents a classic convergence of consumer convenience, supply‑chain leverage, and brand differentiation opportunity. In 2026 companies face three interlocking decisions: where to play (price tiers, reusability, tech), how to win (channel mix, IP, manufacturing strategy), and how to defend (regulatory compliance, ingredient transparency, quality control). Our report is written to convert macro forecasts into near‑term operational choices—without leaking the granular proprietary splits that power our valuation and M&A recommendations.
Worldwide Press on Nails Market
- Market context: steady double‑digit recovery since 2020 has given way to durable mid‑single‑digit expansion driven by home‑application trends and premiumization.
- Competitive posture: the market exhibits low-to-moderate consolidation (top‑3 and top‑5 concentration metrics), which keeps open both organic scale plays and bolt‑on M&A strategies.
- Disruption vectors: reusable systems, app‑connected color technology, and premium direct‑to‑consumer product experiences are reshaping value capture.
What the report delivers — practical, transaction‑ready intelligence
This study is designed as a toolset for decision‑making. It moves beyond descriptive statistics to provide decision frameworks, operational models, and executable playbooks:
Worldwide Press on Nails Market
- Actionable market forecast model (2026–2032) with scenario analysis and sensitivity to raw‑material price shocks and regulatory tightening.
- Go‑to‑market playbooks for three strategic archetypes—mass‑market scale players, premium DTC challengers, and OEM/ODM partners—each with KPIs, budget allocations, and channel economics.
- Manufacturing and sourcing playbook, including cost‑build templates, supplier scorecards, and a tradeoff matrix for onshore vs. offshore production decisions.
- Regulatory and safety checklist aligned to major jurisdictions, mapping label, ingredient and adhesive compliance requirements to operational controls.
- Product innovation roadmap options: reusable systems, hybrid soft‑gel shells, and digital/color‑changing proofs of concept—each benchmarked for time‑to‑market and margin impact.
- M&A screening filters and a prioritized shortlist of archetypal targets (pure play brands, technology owners, manufacturing platforms) to accelerate time to scale.
- Commercial playbook for retailers and marketplaces covering assortment rationalization, pricing bands, promotional lift modeling and inventory velocity targets.
Competitive landscape — strategic takeaways
The category combines consumer brands, tech disruptors and high‑volume OEMs. Our competitive review synthesizes public positioning, product strategy and scalability considerations for active players.
- KISS Products: A mass‑market leader with broad retail distribution and brand equity. Scale advantages in retail placement and assortment management are offset by margin pressure and the need to defend premium tiers.
- Dashing Diva: A design and format innovator leveraging aesthetic trends and globalized manufacturing to support rapid SKU turnover—well positioned to monetize K‑beauty influences and gel‑strip adjacencies.
- Static Nails and Glamnetic: Premium DTC players competing on reusability, finish quality and lifestyle positioning. Their challenge is converting strong customer advocacy into repeatable, efficient acquisition economics.
- Red Aspen and similar social‑selling models: Highly customizable product offerings and social commerce distribution strategies that command higher ASPs but require sophisticated fulfillment and returns management.
- Makartt and professional suppliers: Occupy the pro and hybrid consumer/pro segments—important strategic partners for retail and training channel expansion.
- iPolish: An emergent technology disruptor. Early 2026 activity demonstrated the potential for app‑integrated, color‑changing press‑ons that redefine product lifecycle and price architecture—an innovation that could compress replacement cycles while commanding a premium.
- Xianxing Beauty, Senboma and major OEM/ODM manufacturers: Critical to scale and private label strategies. Their manufacturing depth enables fast SKU production and private‑label programs, but reliance on petrochemical inputs creates shared exposure to raw‑material volatility.
Regulatory and safety environment — essentials for risk management
Press‑on nails are regulated as cosmetics in several key markets. Compliance is largely retrospective (label accuracy, ingredient safety, truthful claims), but enforcement can be material—especially where adhesives, coatings or additive chemistries raise safety flags. The report provides a compliance playbook mapping common failure modes (mislabeling, banned additives, allergenic adhesives) to mitigation actions and quality assurance checkpoints. We also discuss public‑health considerations—moisture trapping and infection risk—so product teams can design removal systems and aftercare solutions that reduce liability and increase consumer trust.
Raw materials and supply‑chain priorities
Production depends on ABS and acrylic resins, soft‑gel chemistries and cyanoacrylate adhesives—inputs tied to petrochemical markets. Our cost‑model and scenario tests illuminate how feedstock price swings propagate to COGS, margin and breakeven pricing. The report evaluates strategic responses: hedging supplier contracts, qualifying bio‑based alternatives, localized stocking strategies and dual‑sourcing to maintain fill rates during disruptions.
Strategic playbook for 2026 — recommended moves
Based on our modeling and competitor benchmarking, we recommend executives prioritize a small set of coordinated moves in 2026:
- Segmented product architecture: maintain competitive SKUs across value, premium reusable and tech‑enabled tiers—but manage SKU complexity through a platform approach that reuses tooling and adhesives.
- Channel orchestration: aggressively optimize DTC economics (LTV/CAC), while protecting retail relationships via exclusive assortments and co‑funded marketing programs.
- Manufacturing strategy: pursue a hybrid model—partner with established OEMs for scale SKUs while retaining in‑house capability for fast‑turn, premium collections and IP‑sensitive products.
- Innovation investment: allocate a portion of R&D to digitization and product experiences (e.g., app integration, color‑changing tech, AR try‑on) where premiumization lifts margins materially.
- Regulatory and QA: operationalize a cosmetics compliance program with ingredient audits, adhesive testing protocols and packaging controls to preempt market recalls or enforcement action.
- Sustainability & brand risk: pilot recyclable or bio‑based formulations in limited markets to test commercial viability and anticipate investor/retailer ESG requirements.
- M&A & partnerships: prioritize targets that deliver either channel access, proprietary technology, or step‑change manufacturing capacity; use our due‑diligence templates to fast‑track bid models.
Scenario planning and KPIs to monitor
Executives should track a concise set of forward‑looking indicators we model in the report:
- ASP trajectory across tiers and its correlation with repeat purchase rates;
- Inventory turn and lead time from major OEM partners;
- Adhesive failure/return rates and post‑purchase customer support costs;
- COGS sensitivity to resin price swings and the impact on margin at scale;
- Regulatory inquiry incidence and time‑to‑remediation costs.
We provide three ready‑to‑use scenarios—base, upside (accelerated premium adoption), and downside (raw‑material shock/regulatory tightening)—with profit‑and‑loss runs and balance‑sheet implications for each strategic archetype.
Methodology and data confidence
The study integrates proprietary consumer surveys, point‑of‑sale data, primary interviews with manufacturers and retailers, and ingredient supply‑chain analysis. Our forecast blends top‑down macro assumptions with bottoms‑up SKU economics and will‑be updated annually. Key deliverables include modifiable Excel models and executive dashboards tailored for investment committees, product teams and supply‑chain leaders.
How to use this study — advisory and deliverables
PW Consulting offers the report as both a stand‑alone market intelligence product and as the foundation for advisory engagements. Typical next steps for executive teams include:
- Executive briefing and scenario walkthrough with the authors;
- Customized valuation or M&A diligence tailored to a specific buyer/seller universe;
- Rapid supply‑chain risk assessment and supplier remediation roadmap;
- Co‑developed product roadmaps and pilot programs for tech‑enabled or sustainable SKUs.
Note: this release intentionally highlights the study’s analytical thrust and strategic conclusions while gating the granular, commercially sensitive segmentation matrices and company‑level revenue breakouts that underpin our valuations. Those tables and downloadable model files are available via PW Consulting’s research portal and through licensed report access.
Conclusion & next steps
The press‑on nails market in 2026 is a pragmatic growth story: resilient consumer demand, diverse strategic entry points, and notable upside from product innovation. For incumbents and new entrants, the imperative is to pair disciplined operational execution with targeted innovation bets—particularly in reusability and digital experiences—while shoring up supply‑chain resilience and compliance. PW Consulting’s Worldwide Press‑on Nails Market report is designed to convert those insights into executable plans that boards and executive teams can apply immediately.
To request an executive briefing, sample pages or a tailored engagement, please contact PW Consulting’s Consumer Beauty practice through our corporate channels. Our team will provide a concise roadmap for translating the report’s scenarios into your company’s 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Worldwide Press on Nails Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Engineering Hydraulic Piling Hammer Market to Expand at 5.3% CAGR, Forecast to Reach USD 257M by 2032 as Asia‑Pacific Leads with USD 82.6M
By pmarketresearch, 2026-07-13
Marine Engineering Hydraulic Piling Hammer Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present an executive briefing drawn from our latest Marine Engineering Hydraulic Piling Hammer Market study. The research consolidates five years of historical performance (2020–2025) and delivers an actionable forecast through 2032. This briefing highlights the strategic implications that matter for 2026 capital planning, procurement, and technology road‑mapping — while reserving the full, granular segmentation and vendor scorecards for the report itself.
Marine Engineering Hydraulic Piling Hammer Market
Executive snapshot
- Market scale: The global market for hydraulic piling hammers reached approximately USD 191.0 Million in the base year (2025).
- Growth trajectory: Our forecast anticipates a compound annual growth rate (CAGR) of about 5.3% over the 2026–2032 horizon, with the market trending toward the upper‑end of the USD 200–260 Million range by the end of the period under standard scenarios.
- Demand drivers: Rapid offshore wind capacity additions, sizeable port and coastal infrastructure programs, and renewed bridge/harbour investment cycles are the dominant structural drivers shaping purchase patterns and fleet composition.
Why this report matters for 2026 decisions
2026 will be a pivotal year for firms managing heavy marine foundation works. Developers, EPC contractors, port authorities, and equipment lessors face a converging set of pressures: larger monopile sizes, stricter underwater‑noise regulation, constrained supply chains for specialized steel and hydraulic systems, and the economics of owning versus renting high‑value units. Our study translates market-level dynamics into concrete decision levers for procurement, operations, and R&D investment so organizations can avoid cost overruns and secure project timelines.
Marine Engineering Hydraulic Piling Hammer Market
Market outlook — what to expect in 2026 and beyond
The mid‑decade profile is one of steady expansion rather than explosive growth. With a 5.3% CAGR baked into our forecast, the market is large enough to support multiple global OEMs and rental providers, while still encouraging differentiation through technology, service and niche specialization.
Marine Engineering Hydraulic Piling Hammer Market
- Scale and timing: Projected yearly market flows support a predictable cadence of new unit deliveries and aftermarket support contracts. That predictability helps procurement teams align CAPEX and rental strategies to avoid both under‑capacity and over‑investment.
- Price and input pressures: High‑capacity hammer systems are capital‑intensive. Specialized materials and hydraulics mean individual units carry multi‑million dollar capital price tags; this remains a primary source of cost volatility and a lever for negotiating long‑lead supplier agreements.
- Regulatory drag: Stringent underwater noise mitigation regimes in sensitive habitats are not marginal — they typically add measurable schedule and cost increments to piling campaigns. Our field synthesis indicates mitigation measures can extend timelines and reshape operational windows, necessitating earlier engagement between engineering, environmental and procurement teams.
Strategic implications for 2026 planning
Below are focused actions that should be considered immediately by organizations that commission or deliver marine foundation works:
- Adopt a hybrid ownership model. Given capital intensity and sporadic project pipelines, a mix of owned and rented hammers reduces balance‑sheet exposure while preserving rapid deployment capability for peak periods.
- Integrate noise mitigation into early tendering. Plan for mitigation systems (e.g., bubble curtains, attenuation arrays) and schedule buffers at RFP stage: otherwise bids will be non‑competitive or project timelines will slip.
- Lock long‑lead supplier agreements. Early framework agreements with steel fabricators, hydraulic component vendors and OEMs yield price stability and delivery predictability in 2026–2027 windows.
- Prioritize modularity and retrofitability. Choose systems with upgrade paths for control electronics, hammer energy envelopes and noise‑reduction add‑ons to extend service life as monopile dimensions and regulatory standards evolve.
- Build scenario financial models. Use scenario analyses (base, upside, policy/constraint) to stress test fleet sizing and rental needs over 3–5 year horizons — our report includes templated cashflow and TCO models to accelerate that work.
Competitive landscape — who matters and why
The hammer market is concentrated around a set of globally capable OEMs and a growing tier of regional suppliers. This creates a competitive dynamic where technological leadership, service networks and track record of large‑monopile performance determine tender outcomes more than price alone.
- MENCK GmbH (Acteon) (Kaltenkirchen, Germany) — A benchmark name in high‑capacity, double‑acting hydraulic impact hammers. Their product portfolio targets monopiles and deepwater foundations and benefits from significant reference exposure in large offshore wind programs. MENCK’s recent control‑system upgrades reflect a maturation toward integrated automation and drive efficiency gains in monopile installation campaigns. (See: https://www.acteon.com)
- IQIP (Sliedrecht, Netherlands) — Known for the Hydrohammer S‑series and IQ‑series, IQIP continues to push capacity boundaries, including water‑driven variants engineered for ultra‑deep applications. A notable 2025 product introduction signals IQIP’s intent to capture next‑generation monopile works by offering high‑capacity, digitally controlled systems. (See: https://iqip.com)
- BRUCE Piling Equipment (Siheung, South Korea) — Focused on energy‑efficient designs compatible with crane‑suspended and leader‑mounted operations, Bruce’s equipment appeals to port and bridge contractors where versatility and on‑site adaptability are decisive.
- Junttan Oy (Kuopio, Finland) — A specialist in leader‑mounted hammers with a strong footprint in marine terminal and coastal projects. Junttan’s emphasis on noise and vibration reduction aligns with regulatory trends and community acceptance considerations. (See: https://junttan.com)
- Chinese OEMs and research institutes — A cohort of manufacturers and research bodies has rapidly matured domestic capabilities, deploying very large single‑acting systems in regional offshore wind programs and advancing noise reduction features. These players are shaping competitive pricing and local supply dynamics.
Collectively, top OEMs control a substantial portion of high‑capacity project awards, though opportunities remain for niche innovators and service‑oriented competitors who can demonstrate compliance, uptime and integrated noise solutions.
Technology and operational priorities
The next wave of differentiation will be technical and operational rather than purely mechanical. Our fieldwork and supplier interviews identify three priority vectors:
- Control systems and automation — higher precision energy delivery and digital monitoring reduce re‑drives and improve pile integrity outcomes.
- Acoustic mitigation integration — OEMs that can supply hammer‑level noise attenuation packages or seamless third‑party integration will win tenders in noise‑sensitive jurisdictions.
- Service and logistics networks — proven global service footprints and rapid parts delivery are decisive for contractors operating on tight installation windows.
Report contents — what you will find inside
The PW Consulting report is structured as a tactical playbook for 2026. Highlights include:
- Market sizing and forward scenarios with discrete CAPEX/OPEX modeling templates for purchase vs rental decisions.
- Vendor benchmarking and procurement scorecards focusing on technical fit, lifecycle cost, delivery lead time and noise‑mitigation capability.
- Project playbooks for offshore wind and port/bridge works covering logistics, scheduling buffers driven by noise mitigation, and contractor/OEM coordination checklists.
- Supply‑chain risk maps with mitigation strategies for critical inputs (steel, high‑pressure hydraulics) and recommended contracting approaches for price and delivery protection.
- Regulatory impact assessments showing how operational windows and mitigation measures affect schedule and cost across representative project archetypes.
Practical next steps for 2026
- Commission a rapid portfolio review: align current fleet capabilities to 2026 pipeline and identify capability gaps where rental or partnership is prudent.
- Engage OEMs early on noise‑mitigation and delivery milestones to lock windows and accelerate permitting.
- Run a pilot retrofit for noise reduction on at least one unit to validate CAPEX payback and operational impacts before wider roll‑out.
- Adopt the report’s procurement scorecard for upcoming RFPs to standardise evaluation across technical, commercial and environmental dimensions.
Conclusion — the strategic payoff
For organizations that move decisively in 2026, the payoff is twofold: fewer schedule and compliance surprises, and materially better unit‑economics across your pile‑driving fleet. The market’s steady growth and technological evolution reward those who combine disciplined procurement, early noise‑mitigation planning, and vendor alliances that guarantee upgrades and service. PW Consulting’s full report packages the analytics, templates and vendor intelligence required to convert the market’s growth into project success — while protecting margins and reputations in noise‑sensitive environments.
To access the complete dataset, vendor scorecards, and bespoke modelling tools referenced here, please consult the PW Consulting Marine Engineering Hydraulic Piling Hammer Market report webpage — where the full, actionable intelligence is available to support your 2026 strategy and tender teams.
For detailed analysis of this topic, please visit the official page: Marine Engineering Hydraulic Piling Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Neckband Headphones Market to Hit USD 3,553.7 Million by 2032 as Wireless Segment Dominates at USD 2,352.6M with 3.2% CAGR
By pmarketresearch, 2026-07-13
Worldwide Neckband Headphones Market — 2026 Strategic Preview
Executive Summary
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Neckband Headphones Market report, calibrated for decision-making in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, our top-line model indicates a broadly resilient category with a compound annual growth rate (CAGR) of 3.2%. In revenue terms (USD Million), the industry sits in the mid‑single‑billion range today and is projected to expand into the low‑billions by the end of the forecast window under our baseline scenario. This is a market where product-level innovation, channel reconfiguration and regulatory shifts will matter more to margins and market share than raw unit growth alone.
Worldwide Neckband Headphones Market
Why this report matters for 2026 corporate strategy
-
Timing: 2026 is a pivot year — new EMC and materials regulations, tariff adjustments and component cost inflections converge to change product economics and go‑to‑market risk profiles.
Worldwide Neckband Headphones Market -
Precision: Our models translate macro trends into SKU‑level margin scenarios so product, procurement and pricing teams can simulate outcomes under competing assumptions.
Worldwide Neckband Headphones Market -
Priorities: The next 12–18 months will determine who captures profitable share as the category bifurcates between premium ANC/immersive experiences and high‑value fitness/utility propositions.
Key industry dynamics shaping 2026 decisions
-
Component commoditization and input cost displacement: Bluetooth chipset prices have continued to decline at scale — Counterpoint Research cites a circa‑15% year‑on‑year reduction to roughly $2.50 per unit for Bluetooth 5.3 packages used in neckband products. This compresses per‑unit bill‑of‑materials but increases emphasis on differentiation through firmware, ANC tuning and services.
-
Battery and logistics normalization: Lithium‑polymer battery lead times have stabilized in the 8–10 week band after 2024–2025 capacity adjustments in China, improving production predictability but not eliminating schedule risk for high‑volume launches.
-
Regulatory and materials mandates: The EU’s updated chemicals framework requires increased recycled content in magnet materials (e.g., a 20% recycled neodymium threshold beginning in 2026), forcing design and supplier qualification workstreams to accelerate now.
-
Trade and tariff pressures: Tariff actions on electronics components have raised landed costs for certain China‑sourced inputs; in one material change, US Section 301 adjustments lifted effective duties on some imports to 25% in 2025, altering sourcing economics and justifying nearshoring analysis for many OEMs.
-
Electromagnetic compatibility (EMC) compliance: FCC Part 15 updates effective Q1 2026 establish tighter EMI limits under 1 GHz, which will change certification timelines and rework risk for designs that previously relied on legacy compliance baselines.
What’s inside the PW Consulting report (practical deliverables)
-
Proprietary market sizing and validated topline forecasts (base year 2025; forecast 2026–2032) with scenario toggles for price, warranty cost, and regulatory impact.
-
SKU economics models: configurable Excel models that map BOM, freight, duty, and channel fees to target retail price and gross margin by archetype (premium ANC, fitness‑centric, value).
-
Go‑to‑market playbooks: specific channel, promotion and bundle strategies for direct, retail and telco distribution that preserve margin while maximizing attach and retention.
-
Supply chain decision matrix: supplier scorecards, qualification timelines to meet recycled material mandates, and risk‑weighted nearshore vs. offshore scenarios.
-
M&A and partnership screening: a short list of strategic targets and capability gaps, plus an integration checklist to capture synergies within 12 months.
-
Regulatory readiness toolkit: compliance timelines for FCC and EU updates, testing priorities and contingency budgets for re‑engineering or retesting.
-
Competitive landscaping and R&D trend maps: innovation hotspots across ANC, battery chemistry, coatings and fitness sensors — plus patent filing heatmaps and licensing vectors.
Competitive landscape: who to watch and why
The neckband segment remains meaningfully concentrated — our market concentration metrics indicate that the top three firms account for roughly 38.5% of market revenue, while the top five control just over half (52.1%). This structure supports scale advantages (marketing, distribution, R&D) while leaving space for fast‑moving challengers and regional specialists to capture tactical share.
-
Sony Corporation (Tokyo, Japan) — continued focus on noise cancellation and premium audio tuning. Recent product activities include late‑2025 introductions that enhance ANC performance for neckband‑compatible designs, strengthening Sony’s premium halo.
-
Bose Corporation (Framingham, MA, USA) — leverages brand equity in ANC with sportable neckband variants and user experience consistency across form factors; their emphasis remains on comfort and sound signature continuity.
-
Jabra / GN Audio (Ballerup, Denmark) — plays to fitness and enterprise use cases, integrating tracking features and spatial audio updates in mid‑2025 SKU refreshes to maintain differentiation.
-
Sennheiser (Wedemark, Germany) — targets durability and IP ratings for sports‑oriented neckbands, retaining a strong position in audio enthusiast segments through mechanical and acoustic design.
-
Anker / Soundcore (Shenzhen, China) — competes on battery life and value innovation, expanding open‑ear and fitness catalogues in 2025 to pressure mid‑tier margins.
-
Samsung Electronics (Suwon, South Korea) — uses ecosystem integration and accessories strategy to anchor users to broader device portfolios; neckband lines complement the Galaxy wearable experience.
-
OnePlus (Shenzhen, China) — focuses on aggressive battery claims and pricing, with updated 2025 SKUs targeting longer playtimes and ingress protection for active users.
-
Boat Lifestyle (New Delhi, India) — rapid‑SKU cadence in value segments and regional distribution strength, leveraging ASAP charging and aggressive promotions to grow household penetration.
-
JBL / Harman (Northridge, CA, USA) — emphasizes sport and lifestyle aesthetics with durable neckband SKUs optimized for active use.
-
Philips (Amsterdam, Netherlands) — focuses on signature bass enhancement and ergonomics, addressing mainstream consumers through retail channels.
Notable recent moves that change the competitive calculus: Sony’s late‑2025 ANC introductions, Jabra’s mid‑2025 Dolby Spatial updates, and several 2025 catalog expansions from OnePlus, Anker and Boat that increase SKU overlap at the value and active‑wear layers. These product moves, combined with ongoing component cost declines, suggest that 2026 will favor firms that can rapidly monetize software and services on top of hardware while protecting hardware margin through scale and supply agility.
Strategic implications and recommended plays for 2026
-
For OEMs and brand owners: prioritize modular architectures that separate radio/ANC modules from cosmetic shells; accelerate supplier qualification for recycled magnet content; and incorporate EMC headroom into early prototypes to avoid late‑stage rework under the new FCC limits.
-
For procurement and supply chain teams: renegotiate long‑lead battery contracts with staged volumes to capture price improvements while maintaining fill rates; evaluate local assembly or bonded warehouse strategies to blunt tariff exposure and shorten certification cycles.
-
For R&D and product managers: shift investment toward perceptual audio software (ANC tuning, spatial audio) and feature differentiators (secure multipoint, fast charge) that increase secondary monetization potential — software upgrades can extend SKU lifecycles as hardware margins compress.
-
For retail and channel partners: reconfigure bundles and warranty offerings emphasizing experience (customization, ANC profiles, sports telemetry) rather than competing solely on headline battery or SKU price.
-
For investors and strategic buyers: prioritize targets with defensible service layers (apps, firmware ecosystems), robust QA/certification track records, and footprint diversification to hedge tariff and regulatory risk.
Risks and watchlist for 2026
-
Tariff escalations and export restrictions that reprice established BOMs and require supply reallocation.
-
Regulatory non‑compliance exposure (EMC and recycled materials) which can delay launches or force recalls.
-
Commoditization accelerating to a point where only scale or software distinguishes winners — raising the importance of post‑purchase engagement economics.
-
Component supply shocks (battery chemistries, magnet availability) that disproportionately affect premium designs with tight acoustic tolerances.
Why PW Consulting’s market intelligence is the right tool for 2026
Our report combines proprietary BOM models, supplier price indexes, and scenario‑driven revenue models calibrated to the 2025 base year and extended through 2032. We deliver both the quantitative outputs (forecast dashboards, margin scenarios, sensitivity matrices) and the practical playbooks (channel strategies, regulatory checklists, M&A screens) required to make defensible strategic choices in the coming 12–24 months.
As a “trailer” to our full report, this release surfaces the critical market dynamics and competitive movements you need to consider now while intentionally withholding segment‑level breakdowns and SKU‑specific figures to preserve the executive value of the full dataset. Companies that act early on supplier qualification, EMC readiness and service‑layer monetization will enter 2027 with asymmetric advantage.
Next steps and how to access the full study
Executives seeking the complete dataset — including interactive regional and application splits, SKU economics, channel forecasts and the full suite of scenarios and worksheets — can visit the PW Consulting report page. The full report is designed as an operational decision tool for product, procurement, finance and corporate development teams preparing for the regulatory and commercial inflection points of 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Neckband Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com