

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Public Address & Voice Alarm (PAVA) Market Set to Expand at 6.5% CAGR Through 2032

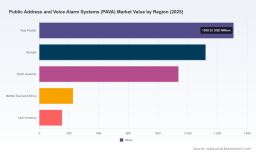
Worldwide Public Address and Voice Alarm (PAVA) Systems: Strategic Imperatives for 2026
As organizations prepare strategic technology and safety investments for 2026, the PAVA (Public Address and Voice Alarm) systems market is presenting both predictable growth and disruptive inflection points. PW Consulting’s latest Worldwide PAVA Market report synthesizes market-sizing, regulatory shifts, technology trajectories, and vendor dynamics to equip executives with decision-grade insight. This briefing pulls forward the report’s strategic value—while preserving the granular subsegment data we reserve for the full report—so leaders can prioritize near-term actions and governance checkpoints for 2026.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Market Trajectory: A Solid Growth Engine
The global PAVA market has demonstrated steady expansion over the past half-decade, moving from an estimated USD 2,814.22 Million in 2020 to USD 3,748.80 Million in 2025. Our base-year analysis and forward projection show continued momentum, with 2026 positioned as a transition year into a multi-year growth phase. Over the 2026–2032 forecast horizon, we model a compound annual growth rate (CAGR) of 6.5%, reflecting sustained investment in safety-critical audio systems across built environments and transport nodes.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
What this means for 2026 planning: organizations should treat PAVA procurement and modernization not as discretionary refreshes but as strategic, funded programs tied to compliance, continuity, and occupant experience. The macro growth supports vendor investment in product lines (notably, IP-native and cloud-managed architectures), while also creating opportunity for differentiated service offerings from integrators and security-as-a-service providers.
Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Why This Report Matters to 2026 Decision-Makers
-
Actionable market sizing and scenario planning: We provide validated topline market estimates and scenario-driven forecasts that illuminate upside and downside pathways for budget cycles that start in H2 2025 and will be executed in 2026.
-
Regulatory and standards alignment: With EN 54-16, NFPA 72, and regionally relevant standards shaping procurement specifications, the report translates compliance obligations into product and vendor selection checklists—reducing specification risk during tender design.
-
Technology adoption and TCO playbooks: Our modeling contrasts centralized analog, distributed/hybrid, and IP-based deployments to illustrate total cost of ownership dynamics across lifecycle, maintenance, and upgrade pathways—this is essential for capital planning for 2026–2028.
-
Vendor and supplier execution maps: We synthesize vendor strengths, recent product developments, and route-to-market channel dynamics—helping procurement teams prioritize vendor panels and risk-mitigation clauses for 2026 contracts.
What’s Inside the Full Report (Practical Tools)
- Validated market sizing by year and high-level growth drivers (macro numerics and trend analysis are included; granular subsegment shares are available only in the full report).
- Scenario-based demand forecasts and sensitivity analysis tied to three adoption pathways: retrofit-led, new-build integration, and cloud-managed migration.
- Procurement-ready templates: RFP language mapped to EN and NFPA compliance, scoring rubrics, and installation cost drivers to reduce ambiguity in bids.
- Vendor scorecards and technology risk matrices focused on certification status, interoperability, cybersecurity posture, and service coverage.
- Deployment playbooks for high-risk environments: transportation hubs, healthcare, education, and industrial sites—covering design redundancies, intelligibility testing, and maintenance regimes.
- CapEx vs. OpEx modeling for cloud-managed vs. on-prem PAVA deployments, including lifecycle replacement scheduling and expected maintenance consumption points.
Competitive Landscape — Players to Watch
The PAVA vendor ecosystem blends established systems integrators and manufacturers with specialized vendors that target vertical niches. Among the firms we profile in detail are global engineering brands and specialist audio-safety vendors whose product portfolios and recent moves reveal the priorities for 2026 procurement:
- Bosch Security Systems (Germany) — Notable for its Plena and Praesensa IP-native platforms, with recent firmware updates that enhance integration into smart-building ecosystems.
- TOA Corporation (Japan) — Strong IP-Network product lines positioned for large venues and transport hubs, and recent certification wins that reduce procurement friction.
- Honeywell International (USA) — Integrates PAVA into broader building and fire safety suites, advancing cloud-managed voice evacuation capabilities.
- Zenitel / Vingtor-Stentofon (Norway) — Specializes in high-reliability IP intercom and PAVA solutions for maritime and public-safety use cases.
- Biamp, RCF, AtlasIED, TOA, Baldwin Boxall, and other specialists — Each provides differentiated strengths across IP paging, evacuation, voice intelligibility, and certification footprints suitable for targeted verticals.
Notably, recent product and certification activities—from firmware refreshes to EN 54 certifications and maritime feature showcases—underscore vendor investment in interoperability and compliance. These developments accelerate procurement velocity in markets where certification is a gating criterion for deployment.
Regulation and Standards: Market Shapers
Compliance remains a primary driver of PAVA demand. EN 54-16 continues to define performance for voice alarm control in parts of Europe, while NFPA 72 is materially influencing specification requirements in North America—particularly intelligibility metrics for large assembly occupancies. Complementary standards, such as the BS 5839 family for VoIP-based emergency communications, create regional nuances organizations must reconcile in multi-jurisdiction deployments. Additionally, changes in UL standards for mass notification have shifted how suppliers frame compliance and certification narratives.
For procurement teams, the practical implication is two-fold: include standards verification as mandatory pass/fail criteria in tenders and insist on documented verification processes (e.g., speech intelligibility testing under occupied conditions) as contract deliverables.
Cost and Operational Dynamics
Installation economics continue to be a significant factor. Our analysis confirms that cabling and connectivity remain a material portion of installation cost—copper runs in large venues can constitute a notable share of on-site spend. That reality drives interest in strategies that reduce cabling intensity: fiber backbone designs, localized amplification, power-over-Ethernet approaches, and selective wireless links for non-critical ancillary systems.
Lifecycle service and remote management are emerging as competitive differentiators. Vendors offering cloud-managed monitoring, remote diagnostics, and software update pipelines reduce mean time to repair and can shift parts of maintenance spend from capex to predictable opex—an attractive shift for many facility management organizations budgeting in 2026.
Strategic Priorities for 2026
-
Embed compliance-first procurement: Require explicit EN/NFPA/BS conformance evidence and include speech intelligibility as a contractual KPI. For multi-site operators, mandate third-party verification of standards compliance at a representative sample of sites.
-
Prioritize IP-native architectures where lifecycle and integration benefits outweigh near-term capex increases. IP systems improve remote manageability and can converge with building management and security networks, but must be evaluated for cybersecurity and latency.
-
Pursue staged modernization: For owners of legacy analog systems, adopt a phased upgrade approach that targets critical zones first (e.g., assembly points and control rooms) and preserves investment through interoperable gateways.
-
Reduce cabling risk exposure: Re-evaluate specs that presuppose long copper runs; design appendices for fiber, amplifier distribution strategies, and loop-based architectures that reduce installation cost and schedule risk.
-
Engage vendors on lifecycle SLAs: Negotiate software-update cadences, cybersecurity responsibilities, and spares provisioning up-front to avoid unbudgeted refresh cycles during 2026–2028.
-
Test cloud-managed service economics: Run pilot projects that quantify the operational savings from remote monitoring, reduced site visits, and subscription-based management—these pilots should feed 2027 budget cycles.
How to Use the Report in Your 2026 Planning Cycle
- IT and Security Heads: Use the vendor scorecards and cybersecurity checklists to validate network segmentation and patching obligations before signing multi-site agreements.
- Procurement and FM Leaders: Adopt the RFP templates and cost-model worksheets to align CAPEX approvals with ongoing OPEX commitments tied to cloud services.
- CEOs and CFOs: Leverage the scenario forecasts and ROI matrices to prioritize projects that deliver compliance and continuity benefits while optimizing capital deployment.
Final Note — A Strategic Teaser
PW Consulting’s Worldwide PAVA Market report offers the granular dashboards, subsegment forecasts, and vendor scorecards that executive teams need to make defensible 2026 investments. In keeping with our “trailer” approach, this release highlights the market’s direction, regulatory inflection points, vendor moves, and recommended strategic plays—while detailed subsegment tables, regional splits and the complete vendor benchmarking matrix are reserved for the full report. For teams ready to convert market insight into procurement action plans, the full dataset and downloadable decision tools are available on our website.
2026 will be a pivotal year for organizations balancing safety compliance, networked systems strategy, and total cost of ownership. The choices made now—on architecture, standards compliance, and vendor governance—will set a 5–7 year trajectory for resilience and occupant safety. PW Consulting’s report is designed to make those choices clear, measurable, and executable.
For detailed analysis of this topic, please visit the official page: Worldwide Public Address and Voice Alarm Systems (PAVA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com