

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cryogenic Lasers Market Poised for Robust 9.0% CAGR

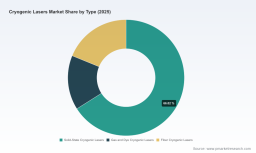
Worldwide Cryogenic Lasers Market — Strategic Outlook for 2026: Navigating Opportunity, Supply Volatility, and Competitive Consolidation
PW Consulting’s latest market study, Worldwide Cryogenic Lasers Market (base year 2025; historical window 2020–2025; forecast 2026–2032), delivers the strategic intelligence executives need to make high‑stakes decisions in 2026. Our analysis synthesizes historical momentum, technology inflection points and supplier economics to produce a forward-looking playbook: the market is entering a phase of accelerated commercialisation, with macro demand growing at a projected compound annual growth rate (CAGR) of 9.0% across the 2026–2032 forecast horizon.
Worldwide Cryogenic Lasers Market
High-level market trajectory
From a base market size of USD 279.22 Million in 2025, our model anticipates measurable expansion in 2026 and across the forecast period, with the total market expected to rise to roughly USD 510.41 Million by 2032 under the central case. That trajectory reflects a combination of steady capital expenditure in research institutions, increased industrial adoption for precision material processing, and nascent but rapidly maturing demand from quantum technology and specialized medical applications.
Worldwide Cryogenic Lasers Market
Why 2026 is a strategic inflection point
- Commercial readiness meets macro tailwinds. The past five years (2020–2025) saw prototype performance breakthroughs and demonstrable reliability improvements. Entering 2026, several system architectures cross the threshold from lab validation to repeatable factory production runs, enabling OEMs and integrators to plan two- to three‑year product roadmaps with realistic launch timelines.
- Capital availability for deep-tech deployment. Investment appetite for enabling technologies—particularly those that underpin quantum computing and advanced micro‑machining—has strengthened. Our scenario work shows that even conservative capital deployment rates materially affect addressable market size over the forecast.
- Regulatory and safety framing that supports adoption. U.S. and international safety frameworks—specifically OSHA guidelines on laser hazard assessment and FDA/ CDRH Federal Laser Product Performance Standard (FLPPS) requirements for emission classification and labeling—are increasingly integrated into procurement checkpoints, shortening qualification cycles for compliant products.
Supply-side dynamics and near-term risks
- Cryogens and raw material volatility. The cryogenic lasers ecosystem is sensitive to input markets. In Q1 2025 helium reached record high spot levels (reported in the sector around USD 97,200–117,660 per metric ton) before a correction in H2 2025 following new production ramps in South Africa, the United States and Russia. That episode exposed procurement concentration risks and the lead‑time sensitivity of long‑term helium contracts.
- Pressure on component and fabrication costs. Cryogenic systems rely on stainless steels and specialized alloys; swings in metal prices and spot shortages can erode margins. We observed increased gray‑market activity for components during 2024–2025, highlighting the need for validated supplier networks and tighter procurement governance.
- Regulatory compliance as a gating factor. Compliance with OSHA and FDA/ CDRH expectations—particularly for Class IV systems and non‑beam hazards arising from cryogens or cooling infrastructure—is a material gating factor for market access in major geographies. Early investment in compliance documentation shortens sales cycles and supports premium positioning.
Competitive landscape — consolidation, specialization, and new entrants
The market is moderately concentrated: the top three players account for approximately 42.5% of market share (CR3), while the top five represent roughly 58.8% (CR5). This concentration underpins two strategic realities—technology leadership is a differentiator, and there remains room for specialist vendors and partnerships that target narrow high‑value applications.
Worldwide Cryogenic Lasers Market
- Advanced Photonic Sciences (APS Lasers) — United States. APS has established reputational leadership through sustained performance records in cryogenic laser benchmarks, including high average continuous‑wave powers and picosecond pulse energies. Their strengths lie in deep physics competency, module‑level productisation and a track record of moving lab‑grade capabilities into repeatable product lines—qualities that favor strategic customers seeking best‑in‑class performance for scientific and quantum workloads.
- Coherent Inc. — United States. As a global photonics incumbent, Coherent brings scale, channel reach and systems integration expertise. Its broad portfolio and established relationships across industrial, scientific and medical buyers make it a pivotal partner (or competitor) for platform playbooks that integrate cryogenic cooling with broader laser subsystems.
Across the vendor ecosystem we observed three business models gaining traction: (1) high‑performance niche providers that compete on physics and bench performance; (2) systems integrators that prioritise turnkey capability and regulatory compliance; and (3) component suppliers that enable cost reduction through modularisation and scale manufacturing.
What the PW Consulting report delivers (practical, executable content)
Our report is designed as an operational toolkit—structured to support procurement directors, R&D leaders, BD and corporate development teams as they build 12–36 month plans. Key deliverables include:
- Actionable market sizing and validated demand scenarios (base, upside, downside) for 2026–2032, with sensitivity analyses tied to helium availability, metal price trajectories and regulatory adoption rates.
- Technology radar and readiness matrix that compares architectures (solid‑state, fiber, gas/dye and hybrid cryogenic approaches) against KPIs meaningful to buyers: beam quality, average power, pulse energy, system MTBF and total cost of ownership.
- Vendor profiles and commercial scorecards (including financial robustness proxies, IP positioning and integration capabilities) to support short‑lists and due‑diligence prioritisation.
- Procurement playbooks—contract structures, hedging strategies for cryogen supply, and validated vendor risk assessment templates—that reduce single‑sourced exposure.
- Regulatory compliance checklist and certification timelines by jurisdiction to accelerate product approvals and procurement clearances.
- M&A and partnership opportunity maps identifying pockets of consolidation, tuck‑in targets and strategic OEM partners across the value chain.
- Scenario‑based pricing and ROI calculators enabling buyers to compare cryogenic solutions against conventional laser options on productivity, yield, and lifecycle cost metrics.
Strategic imperatives for 2026 decision‑makers
- Hedge supply; institutionalise procurement resilience. Negotiate multi‑year cryogen contracts with staggered delivery windows, qualify alternative cryogens where feasible, and maintain dual or triple sourcing for critical components. Short episode shocks (like the 2025 helium spike and later correction) can materially affect production economics; prudent hedging reduces revenue volatility.
- Prioritise regulatory readiness early. Build compliance activities into development sprints. For customers targeting regulated markets (medical devices, some industrial safety domains), certification timelines must be front‑loaded to avoid go‑to‑market delays that erode first‑mover advantage.
- Choose product strategy by use‑case economics. Where floor‑area adoption is driven by throughput and yield (advanced material processing), total cost of ownership and productivity uplift should guide architecture selection. For quantum and research customers, performance and stability are the primary purchase criteria even at higher unit costs.
- Pursue modularisation and manufacturability. Vendors that package cryogenic sub‑systems into repeatable, serviceable modules unlock faster deployments at lower field‑service cost. Investors should favour companies demonstrating clear roadmaps to scalable manufacturing and component standardisation.
- Explore targeted M&A and strategic partnerships. Given the mid‑level concentration of the market, strategic acquisitions or collaboration agreements—especially between component specialists and systems integrators—create rapid capability lifts and route‑to‑market synergies.
- Invest selectively in IP and talent. Physics‑heavy domains demand specialist R&D teams. Locking in IP around cooling architectures, hermetic packaging and beam management yields durable protective moats.
How to use this intelligence in 2026 planning cycles
Procurement planners should use our scenario outputs to stress‑test annual sourcing budgets. R&D leaders can prioritise projects using the technology readiness and ROI matrices included in the report. Corporate development teams should map M&A targets against the opportunity maps and concentration analytics to determine whether to pursue bolt‑on acquisitions or platform investments. Finally, operations and supply‑chain leaders must run the included supply‑stress simulations to quantify inventory buffering needs and supplier diversification thresholds.
Conclusion — the decision window is now
The cryogenic lasers market stands at a commercial pivot: technical progress, rising application demand and clearer regulatory frameworks create tangible opportunities for companies that prepare strategically in 2026. The choices made this year—about supplier risk, product architecture, regulatory investments and inorganic moves—will determine which players capture the premium segments of a market projected to approximately double in size by 2032 under our central forecast.
PW Consulting’s Worldwide Cryogenic Lasers Market report provides the empirical foundation and tactical instruments for those choices. For full segmented data, vendor scorecards, scenario models and downloadable decision tools, visit our report page or contact our industry team to request the comprehensive dataset and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Cryogenic Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com