

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Neckband Headphones Market to Hit USD 3,553.7 Million by 2032 as Wireless Segment Dominates at USD 2,352.6M with 3.2% CAGR

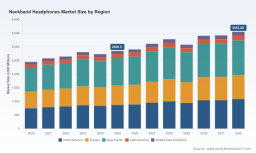
Worldwide Neckband Headphones Market — 2026 Strategic Preview
Executive Summary
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Neckband Headphones Market report, calibrated for decision-making in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, our top-line model indicates a broadly resilient category with a compound annual growth rate (CAGR) of 3.2%. In revenue terms (USD Million), the industry sits in the mid‑single‑billion range today and is projected to expand into the low‑billions by the end of the forecast window under our baseline scenario. This is a market where product-level innovation, channel reconfiguration and regulatory shifts will matter more to margins and market share than raw unit growth alone.
Worldwide Neckband Headphones Market
Why this report matters for 2026 corporate strategy
-
Timing: 2026 is a pivot year — new EMC and materials regulations, tariff adjustments and component cost inflections converge to change product economics and go‑to‑market risk profiles.
Worldwide Neckband Headphones Market -
Precision: Our models translate macro trends into SKU‑level margin scenarios so product, procurement and pricing teams can simulate outcomes under competing assumptions.
Worldwide Neckband Headphones Market -
Priorities: The next 12–18 months will determine who captures profitable share as the category bifurcates between premium ANC/immersive experiences and high‑value fitness/utility propositions.
Key industry dynamics shaping 2026 decisions
-
Component commoditization and input cost displacement: Bluetooth chipset prices have continued to decline at scale — Counterpoint Research cites a circa‑15% year‑on‑year reduction to roughly $2.50 per unit for Bluetooth 5.3 packages used in neckband products. This compresses per‑unit bill‑of‑materials but increases emphasis on differentiation through firmware, ANC tuning and services.
-
Battery and logistics normalization: Lithium‑polymer battery lead times have stabilized in the 8–10 week band after 2024–2025 capacity adjustments in China, improving production predictability but not eliminating schedule risk for high‑volume launches.
-
Regulatory and materials mandates: The EU’s updated chemicals framework requires increased recycled content in magnet materials (e.g., a 20% recycled neodymium threshold beginning in 2026), forcing design and supplier qualification workstreams to accelerate now.
-
Trade and tariff pressures: Tariff actions on electronics components have raised landed costs for certain China‑sourced inputs; in one material change, US Section 301 adjustments lifted effective duties on some imports to 25% in 2025, altering sourcing economics and justifying nearshoring analysis for many OEMs.
-
Electromagnetic compatibility (EMC) compliance: FCC Part 15 updates effective Q1 2026 establish tighter EMI limits under 1 GHz, which will change certification timelines and rework risk for designs that previously relied on legacy compliance baselines.
What’s inside the PW Consulting report (practical deliverables)
-
Proprietary market sizing and validated topline forecasts (base year 2025; forecast 2026–2032) with scenario toggles for price, warranty cost, and regulatory impact.
-
SKU economics models: configurable Excel models that map BOM, freight, duty, and channel fees to target retail price and gross margin by archetype (premium ANC, fitness‑centric, value).
-
Go‑to‑market playbooks: specific channel, promotion and bundle strategies for direct, retail and telco distribution that preserve margin while maximizing attach and retention.
-
Supply chain decision matrix: supplier scorecards, qualification timelines to meet recycled material mandates, and risk‑weighted nearshore vs. offshore scenarios.
-
M&A and partnership screening: a short list of strategic targets and capability gaps, plus an integration checklist to capture synergies within 12 months.
-
Regulatory readiness toolkit: compliance timelines for FCC and EU updates, testing priorities and contingency budgets for re‑engineering or retesting.
-
Competitive landscaping and R&D trend maps: innovation hotspots across ANC, battery chemistry, coatings and fitness sensors — plus patent filing heatmaps and licensing vectors.
Competitive landscape: who to watch and why
The neckband segment remains meaningfully concentrated — our market concentration metrics indicate that the top three firms account for roughly 38.5% of market revenue, while the top five control just over half (52.1%). This structure supports scale advantages (marketing, distribution, R&D) while leaving space for fast‑moving challengers and regional specialists to capture tactical share.
-
Sony Corporation (Tokyo, Japan) — continued focus on noise cancellation and premium audio tuning. Recent product activities include late‑2025 introductions that enhance ANC performance for neckband‑compatible designs, strengthening Sony’s premium halo.
-
Bose Corporation (Framingham, MA, USA) — leverages brand equity in ANC with sportable neckband variants and user experience consistency across form factors; their emphasis remains on comfort and sound signature continuity.
-
Jabra / GN Audio (Ballerup, Denmark) — plays to fitness and enterprise use cases, integrating tracking features and spatial audio updates in mid‑2025 SKU refreshes to maintain differentiation.
-
Sennheiser (Wedemark, Germany) — targets durability and IP ratings for sports‑oriented neckbands, retaining a strong position in audio enthusiast segments through mechanical and acoustic design.
-
Anker / Soundcore (Shenzhen, China) — competes on battery life and value innovation, expanding open‑ear and fitness catalogues in 2025 to pressure mid‑tier margins.
-
Samsung Electronics (Suwon, South Korea) — uses ecosystem integration and accessories strategy to anchor users to broader device portfolios; neckband lines complement the Galaxy wearable experience.
-
OnePlus (Shenzhen, China) — focuses on aggressive battery claims and pricing, with updated 2025 SKUs targeting longer playtimes and ingress protection for active users.
-
Boat Lifestyle (New Delhi, India) — rapid‑SKU cadence in value segments and regional distribution strength, leveraging ASAP charging and aggressive promotions to grow household penetration.
-
JBL / Harman (Northridge, CA, USA) — emphasizes sport and lifestyle aesthetics with durable neckband SKUs optimized for active use.
-
Philips (Amsterdam, Netherlands) — focuses on signature bass enhancement and ergonomics, addressing mainstream consumers through retail channels.
Notable recent moves that change the competitive calculus: Sony’s late‑2025 ANC introductions, Jabra’s mid‑2025 Dolby Spatial updates, and several 2025 catalog expansions from OnePlus, Anker and Boat that increase SKU overlap at the value and active‑wear layers. These product moves, combined with ongoing component cost declines, suggest that 2026 will favor firms that can rapidly monetize software and services on top of hardware while protecting hardware margin through scale and supply agility.
Strategic implications and recommended plays for 2026
-
For OEMs and brand owners: prioritize modular architectures that separate radio/ANC modules from cosmetic shells; accelerate supplier qualification for recycled magnet content; and incorporate EMC headroom into early prototypes to avoid late‑stage rework under the new FCC limits.
-
For procurement and supply chain teams: renegotiate long‑lead battery contracts with staged volumes to capture price improvements while maintaining fill rates; evaluate local assembly or bonded warehouse strategies to blunt tariff exposure and shorten certification cycles.
-
For R&D and product managers: shift investment toward perceptual audio software (ANC tuning, spatial audio) and feature differentiators (secure multipoint, fast charge) that increase secondary monetization potential — software upgrades can extend SKU lifecycles as hardware margins compress.
-
For retail and channel partners: reconfigure bundles and warranty offerings emphasizing experience (customization, ANC profiles, sports telemetry) rather than competing solely on headline battery or SKU price.
-
For investors and strategic buyers: prioritize targets with defensible service layers (apps, firmware ecosystems), robust QA/certification track records, and footprint diversification to hedge tariff and regulatory risk.
Risks and watchlist for 2026
-
Tariff escalations and export restrictions that reprice established BOMs and require supply reallocation.
-
Regulatory non‑compliance exposure (EMC and recycled materials) which can delay launches or force recalls.
-
Commoditization accelerating to a point where only scale or software distinguishes winners — raising the importance of post‑purchase engagement economics.
-
Component supply shocks (battery chemistries, magnet availability) that disproportionately affect premium designs with tight acoustic tolerances.
Why PW Consulting’s market intelligence is the right tool for 2026
Our report combines proprietary BOM models, supplier price indexes, and scenario‑driven revenue models calibrated to the 2025 base year and extended through 2032. We deliver both the quantitative outputs (forecast dashboards, margin scenarios, sensitivity matrices) and the practical playbooks (channel strategies, regulatory checklists, M&A screens) required to make defensible strategic choices in the coming 12–24 months.
As a “trailer” to our full report, this release surfaces the critical market dynamics and competitive movements you need to consider now while intentionally withholding segment‑level breakdowns and SKU‑specific figures to preserve the executive value of the full dataset. Companies that act early on supplier qualification, EMC readiness and service‑layer monetization will enter 2027 with asymmetric advantage.
Next steps and how to access the full study
Executives seeking the complete dataset — including interactive regional and application splits, SKU economics, channel forecasts and the full suite of scenarios and worksheets — can visit the PW Consulting report page. The full report is designed as an operational decision tool for product, procurement, finance and corporate development teams preparing for the regulatory and commercial inflection points of 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Neckband Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com