

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Rising Stem Ball Valve Market Poised to Expand at a 5.86% CAGR Through 2032

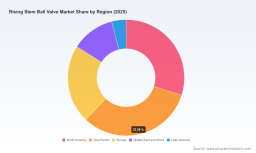
Worldwide Rising Stem Ball Valve Market: Strategic Primer for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Rising Stem Ball Valve market provides a decision-grade, practice-oriented intelligence package designed to influence capital, product, and commercial strategies in 2026. Built on a 2020–2025 historical base and projecting through 2032, the report benchmarks the market using a 2025 base year and quantifies an expected mid-single-digit compound annual growth rate (CAGR) of 5.86% across the forecast window. From an addressable-market perspective, the research synthesizes firm-level positioning, supply chain risk, standards compliance, and aftermarket economics to translate macro growth into executable choices for C-suite and business unit leaders.
Worldwide Rising Stem Ball Valve Market
Why 2026 Is a Pivotal Year
-
Transition from maintenance-driven to performance-driven purchasing: Operators in severe-service industries are increasingly valuing lifecycle cost, zero-leakage assurance, and high-cycle durability over lowest initial price—creating room for differentiated product and service strategies.
Worldwide Rising Stem Ball Valve Market -
Supply chain and raw-material volatility remain central: Recent price and availability swings for carbon, stainless, and exotic alloys mean procurement and design decisions made in 2026 will materially affect margins and delivery capability across the medium term.
Worldwide Rising Stem Ball Valve Market -
Regulatory and standards convergence: Adoption of stringent specifications—especially for critical onshore and offshore oil and gas applications—continues to favour manufacturers who can demonstrate compliance with API and ASME frameworks while minimizing operational risk for end users.
-
Consolidation and competitive clustering: The market’s top tier exhibits meaningful concentration, leaving mid-market suppliers and specialists opportunities to capture niche stacks if they deploy clear technical differentiation and service models.
What the Report Contains — Practical, Executable Components
-
Market sizing and scenario forecasts: A base-year assessment with conservative, central, and upside demand scenarios through 2032, translated into revenue impacts and capacity requirements in USD (Million).
-
Demand-driver heat maps: Industry-by-industry intelligence that maps use-cases for rising stem designs (high-cycle, zero-leakage, particle-tolerant environments), including adoption velocity indicators.
-
Supply chain and raw-material stress-testing: Supplier tier maps, cost-sensitivity models, and hedging playbooks to mitigate price and lead-time risk for key alloys and components.
-
Competitive benchmarks and capability matrices: Side-by-side technical and commercial comparisons of global suppliers, with a focus on design attributes, serviceability, certification, and aftermarket revenue potential.
-
Commercial playbooks: Packaging of product, aftermarket, and field-service propositions with pricing ladders, ROI calculators for customers, and bid/no-bid decision trees for project suppliers.
-
M&A and partnership screening: A prioritised list of asset types and company profiles aligned to three different corporate strategies—scale, capability, and geographic expansion—supported by valuation sensitivity models.
-
Implementation templates: RFP and technical-specification templates, test-plan outlines, and KPI dashboards for procurement and operations teams to shorten decision cycles.
Market Dynamics and Strategic Implications
-
Performance requirements are intensifying. Rising stem ball valves are being specified more frequently where zero leakage and frequent actuation are mandatory. Mechanically energized seats and designs that reduce seal rubbing are becoming standard expectations for critical-service valves.
-
Materials selection is both a cost and reliability lever. The total cost of ownership analysis in the report shows that choices between carbon, stainless, and higher-grade alloys materially shift lifecycle economics—particularly when factoring repair frequency, down-time cost, and parts lead time.
-
Standards matter and act as market gates. Compliance with API 6D, ASME B16.34, and equivalent regional standards is not only a technical requirement but a commercial filter in supplier shortlists for major projects; manufacturers who proactively demonstrate rigorous test protocols capture specification leadership.
-
Aftermarket services are a multiplier. Field-proven designs that minimize friction and particle ingress reduce maintenance calls and enable premium aftermarket contracts; our modelling projects aftermarket attach rates as a key margin driver for suppliers who invest in service delivery.
-
Concentration creates both risk and opportunity. The market shows meaningful clustering among a small number of global players while leaving pockets of specialist demand accessible to challengers; corporate strategy should therefore balance defence in core verticals with targeted penetrations in underserved niches.
Competitive Landscape — Who’s Shaping Technology and Commercial Trends
Our competitive analysis profiles global manufacturers and identifies where technical innovations and go-to-market moves are reshaping the field. Highlights:
-
Flowserve Corporation (Irving, Texas, USA) — Emphasises mechanically energized solutions and product lines engineered to prevent leakage and contamination in oil and gas environments; a go-to name for project-spec heavy applications.
-
Orbit Valves (SLB) (Tulsa, Oklahoma, USA) — Known for tilt-and-turn designs that reduce seal rubbing and deliver reliable zero-leakage performance across multiple pressure classes.
-
Trillium Flow Technologies (Red Point) (Netherlands) — Pioneering non-contact rising stem concepts aimed at extending service life and lowering maintenance in dirty-service oil and gas applications; recently launched a weld-free, friction-reducing design that illustrates the direction of innovation.
-
DHV Industries (USA) — Focused on heavy-duty, trunnion-mounted designs and broad pressure/size coverage; recent catalogue updates reflect ongoing alignment with ASME design requirements.
-
SCV Valve, Maverick Valves, SchuF, ARFLU, ATV SpA — Each vendor brings distinct mechanical architectures (offset cams, top-entry servicing, bottom trunnions) and niche service propositions suitable for specific process scenarios.
Market concentration metrics in the report quantify that the three largest suppliers control a meaningful share of revenue, with the top five commanding a clear majority—an arrangement that reinforces opportunities for strategic partnerships, specialized differentiation, and selective M&A.
Recent Industry Moves You Should Track
-
Trillium Flow Technologies (June 2025) introduced a new non-contact rising stem valve under the Red Point brand designed for dirty-service oil and gas applications. Its weld-free, bottom-trunnion architecture addresses particle ingress and friction—features that shorten downtime and improve lifecycle cost.
-
DHV Industries (February 2025) updated product literature covering expanded ASME B16.34-compliant offerings across a wide range of sizes and pressure classes—an indication of continuing demand for certified, project-grade hardware.
-
Raw-material and regulatory dynamics remain active: price volatility for steels and alloys, plus rising specification stringency for zero-leakage performance, are shaping procurement and product strategies across the board.
Strategic Playbook for 2026 — Concrete Actions
-
Prioritise product architectures that lower lifecycle cost: Invest in designs that reduce friction and ingress (non-contact or mechanical cam systems) and validate those benefits with field trials tied to explicit outage-cost metrics.
-
Lock in materials and components through blended procurement: Combine long-term agreements for critical alloys with dual-sourcing strategies for castings and trim to reduce lead-time exposure.
-
Raise the aftermarket profile: Bundle predictive maintenance, spares agreements, and rapid-response service to convert one-off sales into high-margin annuity streams.
-
Use standards compliance as a commercial weapon: Create simplified compliance dossiers that procurement teams can drop into contract negotiations to accelerate shortlisting.
-
Pursue targeted M&A and JV moves: Look for assets that bolster capability (e.g., top-entry servicing, weld-free trunnions) rather than size alone; our valuation templates help you assess medium-term earnings accretion.
-
Embed scenario-based capital planning: Adopt the report’s stress-tested demand scenarios to size capacity additions, working capital needs, and pricing strategies for 2026–2028.
How PW Consulting Can Help
-
Decision-ready datasets and dashboards calibrated to your product and geographic footprint.
-
Risk-adjusted financial models for procurement, capex, and M&A decisions.
-
Supplier due diligence and technical validation workshops to accelerate buy-side confidence.
-
Commercial playbook execution support: RFP drafting, bid coaching, and aftermarket launch plans.
Our full report provides the granular segmentation, supplier scorecards, and downloadable models that business leaders and investors need to operationalize these recommendations. This executive primer outlines the strategic choices 2026 will demand; the complete study contains the market-detail and supporting tools you’ll reference across budgeting cycles and board decisions. For access to the full dataset, vendor matrices, and scenario models, visit the PW Consulting research page to request the comprehensive Worldwide Rising Stem Ball Valve Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Rising Stem Ball Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com