

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Porcelain Enamel Market Reaches USD 2,030 Million in 2025 — Poised for Further Growth into 2026–2032

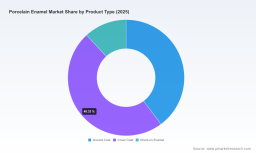
Worldwide Porcelain Enamel Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s forthcoming Worldwide Porcelain Enamel Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) frames an actionable commercial roadmap for executives planning capital allocation, product roadmaps, and supply‑chain redesign through 2026 and beyond. The market reached approximately USD 2,030 Million in 2025 and is forecast to expand at a steady compound annual growth rate (CAGR) of 4.12% across the 2026–2032 horizon, reaching an estimated USD 2,693 Million by 2032. This preview highlights the strategic implications of those trends, synthesizes competitive movements and regulatory headwinds, and outlines the tactical priorities companies should consider as they set budgets and M&A agendas for 2026. For full segment-level tables, granular regional and application shares, and transaction‑level valuation detail, see the full report at the PW Consulting portal.
Worldwide Porcelain Enamel Market
Why this report matters for 2026 planning
-
Decision timing — Porcelain enamel is capital‑intensive and energy‑dependent; capacity investments and line upgrades typically require 12–24 months lead time. The 2026 planning cycle is therefore the pivot point to operationalize insights from 2025 outcomes and to secure supply and talent before cost or regulatory compression materializes.
Worldwide Porcelain Enamel Market -
Profitability levers — Margins in enamel value chains are increasingly tied to formulation innovation (lead‑free, nickel‑free, low‑quartz), energy utilization in firing, and vertical coupling with substrate providers. The report isolates which levers deliver the fastest payback across common business models.
Worldwide Porcelain Enamel Market -
Risk mitigation — Suppliers face volatile feedstock pricing and tightening compliance regimes; the analysis prioritizes hedging and sourcing strategies that reduce exposure while preserving product performance specifications.
Market trajectory and inflection points
Historical data from 2020–2025 shows a market that absorbed pandemic distortion and rebalanced around appliance replacement cycles, construction activity, and industrial refurbishment projects. The 2026–2032 forecast reflects a return to secular demand for durable, corrosion‑resistant enamel solutions across appliances, water heating, cookware, sanitaryware and architectural uses, balanced by efficiency gains and the gradual introduction of higher‑performance premium formulations.
Key inflection drivers identified in the report include regulatory compliance demands in potable water applications, the push to low‑hazard food‑contact enamels, and targeted product innovation that emphasizes heat‑resistance and colour stability. We expect steady expansion rather than explosive growth, with opportunities concentrated in higher‑margin specialty coatings and service‑enabled enamelling.
Cost, supply‑chain and raw material dynamics
-
Feedstock sensitivity — Primary raw materials such as silica (reported Q4 2025 U.S. price roughly USD 53/MT), borates and feldspars remain the dominant input cost drivers. Price volatility in these commodities, combined with the energy intensity of high‑temperature firing, constrains margin expansion unless offset by formulation or process innovation.
-
Energy and process efficiency — Firing kilns and coating lines are significant energy consumers. The report quantifies energy cost contribution to finished enamel pricing and identifies retrofit and process control investments with 2–5 year paybacks under typical regional electricity and gas tariffs.
-
Vertical integration tradeoffs — Players that combine frit manufacture with enamelling services or tie into appliance producer supply chains can realize scale and quality advantages, but must manage capital intensity and operational complexity.
Regulatory landscape and standards impact
Regulatory requirements are an increasingly active determinant of product strategy. European potable water directives and food‑contact standards (e.g., directives and standards comparable to DIN 4753‑3 and ISO 4531) are accelerating demand for nickel‑ and lead‑free enamels and for formulations with controlled quartz content. Conversely, select regional exemptions and legislative nuances—such as the 2025 Minnesota HF‑4 adjustments—create short‑term windows for legacy product lines in some jurisdictions.
For 2026 planning, the critical implication is that compliance‑driven product reengineering is not optional for companies seeking to sell into regulated appliance or potable water markets. The report includes a regulatory matrix that ranks geographies by adoption timelines and compliance cost impact to support prioritization of certification and reformulation spends.
Competitive landscape — who matters and why
The industry shows a moderate level of concentration: top‑3 players account for roughly 38% of market share, while the top‑5 reach about 52%—indicative of strong national champions alongside a fragmented long tail of regional specialists and service providers. Our competitive profiles emphasize capabilities, channel positions, and strategic intent rather than only static share figures, enabling executives to map alliance and acquisition targets against capability gaps.
-
Vibrantz Technologies (incorporating Ferro and Prince Minerals) — A global leader with broad formulation capabilities across powder, paste and ready‑to‑use frits. Vibrantz’s recent product launches (heat‑resistant coatings for industrial ovens and cooktops, April 2025) and an innovation award in 2025 underscore its R&D momentum. Expect continued investment in engineered colourants and performance enamels.
-
A.O. Smith Corporation — A major integrated user and producer, especially in water‑heating systems. A.O. Smith represents the archetype of a downstream OEM that controls portions of the enamelling chain to secure performance and regulatory compliance for potable applications.
-
Regional specialists and service providers — Firms such as AkCoat, Tomatec, Hunan Noli (Nolifrit), Keskin Kimya, Cherokee Porcelain Enamel, Capron, Bootz Industries, Al‑Khudair, Independence Porcelain Enamel and Lovink Technocast play critical roles supplying niche formulations, enamelling services, or finished enameled components. These players often compete on turnaround, customization and local certifications.
-
M&A and capacity moves — Mergers and acquisitions continue to reshape supply footprints: notable activity includes CMF Group’s acquisition of a porcelain enamel frit division (2025) and multi‑year supply contracts awarded to regional producers (e.g., Hindusthan National Glass & Industries contract in 2025), which collectively indicate selective consolidation and capacity rationalization in strategic corridors.
Strategic implications — five actions for 2026
-
Prioritize compliance‑led product investment: Fast‑track low‑hazard, nickel‑free and low‑quartz reformulations for potable and food‑contact endpoints to avoid losing access to premium channels.
-
Invest in thermal efficiency and process controls: Target kiln and line upgrades that reduce energy intensity and improve yield — these projects generally pay back under typical 2026 cost assumptions and protect margins against feedstock cycles.
-
Hedge raw material and logistics exposure: Implement multi‑sourcing and structured purchase contracts for silica and borates; consider strategic inventory buffering where economically justified.
-
Pursue targeted M&A or partnerships: Seek bolt‑on acquisitions that add specialty frits, local certification capabilities, or enamelling services to reduce customer friction and shorten lead times.
-
Differentiate through service and lifecycle economics: Build commercial models that emphasize total cost of ownership (durability, energy savings, lifecycle recovers) for appliance OEMs and specifiers, rather than competing solely on unit price.
What the full PW Consulting report contains (operational highlights)
-
Detailed annual market sizing (2020–2032) and scenario-based forecasts, with sensitivity analysis around energy and raw material prices.
-
Granular segmentation by region, product family and end‑use application, alongside demand‑pull narratives for each channel. (Note: granular segment tables are included only in the full report.)
-
Comprehensive competitive profiles and capability maps, including technical competencies, plant footprints, and partnership pipelines.
-
Cost stacks and margin waterfall diagnostics for representative product lines, with suggested levers to capture margin uplift.
-
Regulatory matrix covering potable water, food contact and hazardous substance controls, plus certification timelines to guide product rollout sequencing.
-
M&A playbook and valuation benchmarks, focused on frit manufacturers, enamelling service providers and integrated OEMs.
-
Primary research appendices (supplier interviews, buyer surveys) and a reproducible methodology section for financial modelling and forecasting assumptions.
Concluding perspective
For 2026, executives in porcelain enamel value chains face a choice: implement defensive measures now (compliance reengineering, energy retrofits, hedging) and accept incremental returns, or invest in differentiated, high‑performance formulations and service offerings that can capture premium end markets. Our analysis shows the market is growing at a measured pace (CAGR ~4.12% to 2032) with meaningful pockets of higher margin opportunity tied to product innovation and regulatory compliance. Moderate industry concentration leaves room for focused scale plays and targeted acquisitions, while regional specialists will continue to command value where agility and certification matter.
PW Consulting has structured the full report to support that strategic decision process — providing the granular, actionable intelligence necessary to convert 2026 planning into funded projects and executable timelines. For the complete dataset, segmented tables, proprietary vendor scorecards and the downloadable executive playbook, visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Porcelain Enamel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com