

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
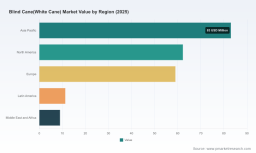
PW Consulting: Worldwide White Cane Market to Expand at 5.5% CAGR—Revenue Forecasted to Reach USD 326.59 Million by 2032, Asia Pacific Leading with USD 83M

Worldwide Blind Cane (White Cane) Market — Strategic Preview for 2026 Decisions
PW Consulting’s new market intelligence briefing frames how mobility-aid manufacturers, assistive-technology integrators, health procurement teams and impact investors should position themselves as the white cane market transitions from a mature assistive product into a hybrid category that blends mechanical design with sensing, connectivity and regulatory complexity. Our analysts forecast a continuation of steady growth — underpinned by demographic demand, product innovation and nascent smart-cane adoption — with a compound annual growth rate (CAGR) of approximately 5.5% over the 2026–2032 horizon. On a macro level, the market is projected to expand from a 2025 baseline (USD 224.5 Million) to roughly USD 245.3 Million in 2026 and to about USD 326.6 Million by 2032 (million USD, reporting in our base currency).
Worldwide Blind Cane(White Cane) Market
Why this preview matters for 2026 strategic planning
- Timing of investment and product launches: 2026 will be the inflection year when several smart-cane second-generation devices and advanced mechanical tips move from prototype/demos to broader pre-orders and limited commercial distribution. The window for securing early OEM partnerships, sensor-sourcing contracts and pilot public procurement slots is narrow; delayed moves will mean competing for smaller shares of incremental growth.
- Channel and procurement complexity: Buyers include public blindness federations, rehabilitation centers, online retail, and medical suppliers — each with different purchasing cycles, quality standards and certification expectations. In 2026 firms must align regulatory and reimbursement positioning in parallel with distribution planning.
- Technology convergence: The pairing of lightweight materials and low-power sensing/AI stacks is creating new value propositions (safety, navigation augmentation, and data-enabled services). Strategic choices now determine whether a company is a component supplier, a licensed product brand, or a platform owner of user data and services.
Market dynamics: drivers, constraints and near-term signals
Demand drivers remain familiar but are being reshaped by three concurrent trends. First, demographic growth and higher diagnosis rates in several markets sustain baseline demand for conventional canes. Second, a wave of design-led products (carbon-fiber lightweight canes, improved folding mechanisms, and novel rolling tips) is expanding use-cases — encouraging activity and adoption among younger blind and partially sighted users. Third, the emergence of smart-cane adapters and fully integrated electronic canes is creating an adjacent market for sensors, haptics, and cloud services.
Worldwide Blind Cane(White Cane) Market
Constraints that will influence 2026 outcomes include regulatory classification and reimbursement policy. National and regional rules remain a determining factor for procurement: for example, in the United States, white canes are typically classified as identifying/self-help devices and therefore fall outside routine Medicare coverage under existing NCD language. Conversely, certain walking canes can meet Durable Medical Equipment criteria when medical necessity is demonstrated, creating nuanced reimbursement pathways that specialized entrants can exploit via clinical evidence and procurement strategy. In Europe, manufacturers seeking to market advanced mobility aids must navigate medical device certification frameworks for product quality and safety — a gating item for many smart-cane players.
Worldwide Blind Cane(White Cane) Market
Technology and product evolution
- Mechanical refinement: Materials science — lighter carbon and engineered composites — continues to reduce weight while improving durability. Design improvements in tips and folding mechanisms will continue to drive user comfort and outdoor usage.
- Smart integration: Second-generation smart canes focus on reliable upper-body obstacle detection, refined voice/navigation integration, and lower false-positive rates in crowded environments. Edge AI and sensor fusion are the key value levers.
- Accessory ecosystems: Rolling tips, interchangeable heads, IoT adapters and app platforms create recurring-revenue and aftermarket opportunities. Companies that control accessory ecosystems can capture higher lifetime value from each user.
Competitive landscape — who matters and what they bring
The market remains moderately fragmented: the top three and top five suppliers do not dominate to the extent seen in many other assistive-device sectors, leaving room for regional leaders, specialty manufacturers and fast-following smart entrants. A strategic read on notable players illustrates current positioning and competitive moves:
- Ambutech Inc. (Winnipeg, Canada) — A global manufacturer with a broad physical product portfolio (rigid, folding, and composite canes) and deep distribution channels in many countries. Their scale in classic mechanical products makes them a preferred procurement partner for institutions and NGOs seeking proven, certified hardware.
- Ossenberg GmbH (Rheine, Germany) — European specialist known for product variety and engineering of ergonomic handles and adjustable systems. Strong in markets where regional standards and localized fit matter.
- whitecane. (IO White Cane, Duderstadt, Germany) — Focused on lightweight carbon solutions and medical-device compliant products. Their certification posture and ergonomic focus make them a key reference for clinical procurement and premium segments.
- WeWALK (Istanbul area) — One of the most recognizable smart-cane brands; its Smart Cane 2 (launched to market in 2025) combines upper-body sensing, AI voice assistant and navigation integration. WeWALK is a bellwether for how well users will accept and pay for integrated electronics.
- Mizuno Corporation (Japan) — Brings sports-grade composites and brand cachet to a lightweight carbon fiber cane aimed at more active users and markets that value design-led products.
- BAWA Tech (Malaysia) — Developer of IoT-enabled adapters that retrofit traditional canes, representing an attractive route for incumbents to add "smart" features without redesigning core mechanical platforms.
- Regional manufacturers and federations — Established manufacturers across Asia and institutional suppliers (including federations distributing free or subsidized canes) remain vital channels and influence standards, training and adoption.
Recent industry signals underscore the bifurcation of the market: WeWALK’s Smart Cane 2 roll-out (2025) confirms commercial appetite for integrated solutions, while product innovations such as advanced rolling tips presented at trade fairs in 2026 show mechanical refinement remains a powerful differentiator.
Actionable strategic recommendations for 2026
- Prioritize one of three strategic plays: (a) Core-mechanical excellence — double down on materials, ergonomics and low-cost manufacturing for institutional tenders; (b) Hybridization — partner with sensor/AI suppliers to offer retrofit kits or co-branded smart canes; (c) Platform play — develop a software and services layer (navigation, remote monitoring, training) to capture recurring revenue.
- Develop certification-first roadmaps: For any product entering regulated markets, align design and clinical-evidence generation with the relevant medical device certification pathways from concept stage to avoid time-to-market delays.
- Segment go-to-market by buying center: Institutional tenders require lifecycle cost models and proof of durability; consumer channels prioritize design, user experience and app ecosystems. Tailor GTM and pricing accordingly.
- Secure supply resilience: Materials (carbon fiber, engineered composites) and specialized rolling tips are bottlenecks. Build second-source agreements and evaluate nearshoring to reduce lead-time risk for 2026 launches.
- Match evidence to reimbursement levers: Where possible, generate limited clinical or usability studies that demonstrate reduced fall risk or increased mobility hours — this assists in local reimbursement arguments and institutional procurement bids.
- Make acquisition and partnership scouting disciplined: M&A targets to watch include sensor-stack developers, rolling-tip innovators, and regional distributors with institutional contracts. Use staged earn-outs tied to certification and sales milestones.
What the full PW Consulting report delivers (practical, operational content)
- Detailed market sizing and forecast models (2020–2032) with scenario sensitivity analyses — including baseline, accelerated smart-adoption and downside-demand scenarios.
- Go-to-market playbooks for producers, distributors and software-platform entrants — with tender templates, pricing levers, and channel-split considerations by buyer type.
- Regulatory and reimbursement navigators — checklists for US, EU and key APAC markets that map certification pathways, clinical evidence thresholds and procurement rules.
- Component and supplier maps — bill-of-material cost drivers, preferred sensor suppliers, and manufacturing cost curves for major materials.
- Competitive dossiers on leading companies and 20+ regional manufacturers — strategic profiles, capability matrices and deal trackers.
- Investment and M&A playbook — valuation benchmarks, integration risk checklists, and sample term structures for bolt-on acquisitions.
- Field research and user-journey case studies — behavioral insights from users across mobility-training centers and consumer pilots to guide product design and service features.
How to use this briefing to set priorities in 2026
If you are preparing a 2026 product roadmap, target a tightened launch window for either a mechanical improvement or a certified smart variant — not both. If you are a distributor or NGO, prioritize supplier relationships with certified manufacturers and specify evidence requirements in RFQs. For investors, favor companies with defensible platforms (software, accessory ecosystems) and clear pathways to certification and institutional procurement.
PW Consulting’s analysis shows that while headline growth is moderate and predictable, value capture is shifting: premiumization through materials and margins on accessories, plus recurring revenue from connected features, will drive outsized returns for firms that execute quickly and manage regulatory pathways effectively.
Next steps and access to the complete intelligence
This release is a strategic preview designed to help leaders prioritize resources for 2026. The full Worldwide Blind Cane (White Cane) Market report contains the complete data tables, region- and product-level forecasts, supplier scorecards and tender-ready appendices that operational teams need to execute. For access to the full dataset and a customized briefing from our industry practice, please visit the PW Consulting report page and schedule a consultation with our audit-ready analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Blind Cane(White Cane) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com