

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Foot Traffic and Customer Location Intelligence Market Hits USD 8,620.5 Million in 2025, Poised for 15.65% CAGR
By pmarketresearch, 2026-07-15
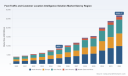
PW Consulting: Strategic Brief — Worldwide Foot Traffic and Customer Location Intelligence Solution Market (2026 Outlook)
Executive summary
PW Consulting is pleased to announce the release of our latest market intelligence brief, Worldwide Foot Traffic and Customer Location Intelligence Solution Market. Drawing on a rigorous historical analysis (2020–2025) and a forward-looking forecast (2026–2032), this study synthesizes commercial telemetry, anonymized mobility datasets, sensor deployments and platform economics to quantify an industry that has matured from niche analytics to strategic operating capability.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
In aggregate terms, the global market expanded from roughly USD 4.02 billion in 2020 to USD 8.62 billion in 2025 and is projected to accelerate through the forecast period—reaching approximately USD 10.24 billion in 2026 and ultimately approaching USD 26.90 billion by 2032. This trajectory represents a compound annual growth rate (CAGR) of approximately 15.65% across the forecast window, underscoring how foot traffic and customer location intelligence are transitioning from point solutions to enterprise-grade decision engines.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Why this report matters for 2026 corporate decision-makers
-
Strategic timing: 2026 is a pivot year. Early adopters who scaled pilots into enterprise deployments during 2023–2025 are now seeking measurable ROI and integration playbooks to govern multi-site operations, omnichannel attribution and revenue uplift modeling.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market -
Economic inflection: The market’s sustained double-digit growth implies that technology selection, data governance and procurement decisions made in 2026 will materially determine multi-year competitive positioning. Implementation choices now will magnify or constrain the potential value that location intelligence delivers at scale.
-
Operationalization challenge: Moving from descriptive footfall metrics to predictive, prescriptive use cases—site selection, cannibalization modeling, workforce scheduling, dynamic pricing and targeted OOH attribution—demands a repeatable, auditable methodology. Our report provides that methodology without substituting for bespoke advisory engagement.
What’s inside the report — practical, execution-oriented content
-
Data architecture blueprints: Recommended pipelines for blending anonymized mobile-derived signals, sensor-based counts (camera/sensor fusion), POI reference data and transaction datasets while maintaining privacy-first processing and compliance constraints.
-
Deployment playbooks: Staged adoption paths for retailers, landlords, transit authorities and venue operators—from proof-of-concept KPIs to enterprise rollouts—aligned to resource profiles (capex vs. opex), integration complexity and expected time-to-value.
-
Vendor selection framework: A decision matrix that weighs product capabilities, data pedigree, integration APIs, professional services depth and contractual constructs (data licensing, SLAs, indemnities). The framework is paired with a reproducible scoring model that procurement teams can apply to their RFP shortlists.
-
Use-case ROI templates: Standardized calculators for estimating incremental revenue, cost avoidance and efficiency gains across common use cases—e.g., site optimization, trade-area analysis, in-store conversion, and out-of-home campaign attribution. Each template highlights critical sensitivity factors and data levers that drive value.
-
Privacy & compliance playbook: Practical controls and process flows to address data sovereignty, localization requirements and cross-border processing considerations, linked to recent legislative and enforcement trends.
-
Scenario-based forecasts: Three executable adoption pathways (conservative, market-parity, accelerated) to stress-test investment decisions under differing macroeconomic and regulatory regimes.
Competitive landscape — positioning the market participants
The market exhibits a classic technology consolidation arc: a relatively fragmented supplier ecosystem where a group of specialist and platform vendors have started to assume leadership roles. Our cr3 and cr5 metrics reflect a market that is consolidating but still leaves substantial opportunity for mid-market and regional players—the top three firms do not yet dominate the majority of market value, and the top five together account for slightly over forty percent of the market.
Key vendor archetypes we observe:
-
Data-first analytics platforms: Providers that build on large anonymized mobility datasets and deliver standardized APIs and dashboards for visitation trends and trade-area analysis.
-
Sensor and on-premise analytics specialists: Companies offering hardware, edge computing and computer-vision-based footfall measurement for indoor accuracy and real-time operations.
-
Enterprise GIS and integration platforms: Established geospatial platforms that act as system-of-records for spatial analytics, enabling large-scale mapping, routing and contextualization of location signals.
Representative companies in these archetypes include established location-intelligence specialists, mobility data aggregators, and sensor manufacturers. Each brings differing strengths: some excel at visit attribution and trade-area modeling, others at in-store conversion analytics and sensor accuracy, while platform incumbents contribute scale and integration breadth. Recent commercial activity illustrates the dynamic interplay between these groups:
-
Placer.ai (Webinar, March 2026) positioned its analytics as central to economic development and retail strategy, speaking to the practical needs of site selection and consumer behavior segmentation in a bifurcated retail environment.
-
Partnerships that embed foot traffic intelligence directly into commercial real estate platforms (e.g., a March 2026 integration announced between a mobility analytics provider and a major RE analytics firm) demonstrate demand for seamless asset-level insights at REIT and portfolio management layers.
-
Product enhancements from specialist vendors continue to push depth in site selection modeling, cannibalization analysis and trade-area overlap: these improvements shrink time-to-insight for customers running competitive-location analyses.
Regulatory, technical and market dynamics that will shape 2026
-
Data sovereignty and cross-border data handling: Several jurisdictions are tightening requirements for storage and processing of personal and derived location signals. Enterprises must architect for local processing where required or select vendors with compliant, localized infrastructures.
-
Law and access regimes: Extraterritorial law enforcement access frameworks have implications for vendors headquartered in certain jurisdictions. Legal exposure can influence vendor selection and contract negotiations, particularly for multinational customers.
-
Spectrum and wireless ecosystem changes: Ongoing regulatory attention to dynamic spectrum management and improved sharing frameworks opens new technical pathways for sensor networks and reduces some constraints on wireless-based sensing—but also introduces new compliance and interoperability requirements for device makers and network operators.
-
Technology evolution: Advances in AI-powered video analytics and sensor fusion increase the accuracy and utility of indoor and storefront measurement, while anonymized mobile tracing continues to excel at macro-level mobility flows. The best outcomes for enterprises come from combining modalities and validating against ground-truth sources.
Strategic implications and recommended executive actions for 2026
-
Plan for a hybrid data architecture: Combine edge-enabled sensors for in-store accuracy with anonymized mobility and POI datasets for market-level context. Design for modularity so you can swap suppliers without re-architecting core systems.
-
Prioritize governance and privacy-by-design: Adopt contractual and technical controls that can flex to regional data sovereignty requirements and withstand legal scrutiny across jurisdictions.
-
Operationalize use cases with value gates: Deploy in iterative sprints tied to explicit KPIs (e.g., lift in conversion, reduction in vacancy days, improvement in campaign ROI). Avoid broad “capture everything” pilots that fail to translate into measurable outcomes.
-
Embed vendor evaluation into procurement: Use a scoring matrix that measures not just feature fit but also data lineage, legal exposure, professional services capability and roadmap alignment with your enterprise stack.
-
Invest in internal capabilities: Build small, cross-functional teams (data, ops, legal, commercial) to own the lifecycle of location intelligence from data ingestion to business outcome.
How to use this briefing — and what we’re intentionally withholding
This briefing is intended to orient senior leaders and procurement teams to the levers and risks that will determine the value of location intelligence investments made in 2026. It highlights the market scale, growth trajectory and practical content we provide. In keeping with PW Consulting’s “teaser” approach, we have deliberately not included the detailed segmentation tables, regional and application-level percentage breakdowns, or vendor scorecard scorecards in this public summary. These granular datasets and company-level assessments are available in the full report and through our advisory engagements, where we tailor insights to client-specific geographies, verticals and tech stacks.
Next steps
-
For procurement teams: Request our vendor selection template and a short-list workshop tailored to your procurement cadence.
-
For business leaders: Use our ROI templates to stress-test near-term investments and quantify expected uplift in 12–24 months.
-
For investors and private equity: Consult our scenario forecasts and market concentration analysis to assess acquisition and partnership targets aligned to your portfolio thesis.
PW Consulting’s Worldwide Foot Traffic and Customer Location Intelligence Solution Market report is designed as an actionable resource for leaders who must convert location-derived signals into defensible business advantage. For access to the full dataset, regional and application-level segmentation, vendor scorecards and bespoke benchmarking services, please visit our report page or contact our advisory team to arrange a tailored briefing.
— PW Consulting, Global Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Isononyl Acrylate Market Poised for 5.45% CAGR in 2026–2032, Unlocking Global Growth
By pmarketresearch, 2026-07-15
Worldwide Isononyl Acrylate Market: Strategic Intelligence for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market brief on Worldwide Isononyl Acrylate (INA) delivers forward-looking strategic intelligence tailored for executives making capital allocation, procurement, and M&A decisions in 2026. Our analysis synthesizes primary interviews, proprietary shipment and pricing models, and a detailed supply-demand baseline that values the global INA market at USD 218.45 Million in 2025 and projects growth to USD 316.72 Million by 2032, reflecting a 5.45% compound annual growth rate (CAGR) across the 2026–2032 forecast window. We have calibrated this outlook to current feedstock dynamics, regulatory developments, and evolving end-use markets—highlighting where value will emerge and where risk concentrations are likely to compress margins or trigger strategic responses.
Worldwide Isononyl Acrylate Market
Why INA matters in 2026
Isononyl Acrylate plays a pivotal role in formulations for pressure-sensitive adhesives, UV-curable resins, industrial coatings, and specialty elastomers. Its technical profile—combining flexibility, low volatility, and compatibility with radiation-curable systems—keeps the molecule at the intersection of performance-led product innovation and cost-sensitivity. That intersection is where procurement teams, product strategists, and investors must make trade-offs in 2026: secure reliable, low-carbon supply; defend margin against feedstock inflation; and extract value from formulation-led differentiation.
Worldwide Isononyl Acrylate Market
Market dynamics and macro drivers
Three macro forces are shaping INA strategy in 2026:
Worldwide Isononyl Acrylate Market
- Feedstock and upstream cost volatility: Short-term swings in isobutene and acrylic acid markets have direct pass-through effects on INA production economics. Recent spot observations show isobutene trading dynamics tightening and acrylic acid experiencing upward pressure, both of which matter to manufacturers who either vertically integrate or source monomers on the merchant market.
- Regulatory and carbon cost exposures: REACH updates through 2025 confirm INA’s current compliance status in the EU, removing a near-term regulatory overhang. However, new trade instruments like the EU Carbon Border Adjustment Mechanism (CBAM), effective from January 2026 for qualifying imports, introduce a cost dimension tied to embedded emissions—an input that will change supplier economics and buyer sourcing strategies for non-EU producers.
- Consolidation and concentration: The sector exhibits moderate concentration among the top participants. Market concentration metrics indicate meaningful market power resides with a handful of players, which affects pricing dynamics, contract terms, and the strategic calculus for new entrants or capacity expansions.
Supply chain pressure points
INA’s upstream feedstocks—principally isononyl alcohol (linked to isobutene availability) and acrylic acid—are subject to wider petrochemical cycles. In early 2026, isobutene spot levels reflected tighter petrochemical balances; acrylic acid showed month-on-month increases in Asia driven by propylene tightness. Producers with backward integration into monomer production or long-term off-take agreements are better positioned to manage short-cycle price shocks; merchant-dependent processors face margin squeeze unless they implement dynamic pass-through or hedge strategies.
Regulatory overlay: compliance and carbon pricing
The regulatory landscape is bifurcating commercial risk. On one hand, INA’s REACH registration status is stable with no new Annex XVII restrictions as of the 2025 update, simplifying market access for compliant producers. On the other hand, carbon-related trade measures (notably EU CBAM) create a new cost vector for non-EU exporters whose embedded emissions exceed defined thresholds. Strategically, this means buyers in regulated jurisdictions will increasingly value low-carbon provenance and traceability—factors that influence long-term contracts, supplier qualification, and the premium paid for certified low-emission volumes.
Competitive landscape: who matters and why
The INA supplier set is populated by established specialty chemical groups and regional manufacturers. Key players we profile in the full report include:
- Sartomer (Arkema): A global specialty acrylates platform with deep technical capabilities in UV/EB-curable chemistries and a broad commercial footprint. Sartomer’s strength lies in formulation expertise, global customer relationships, and the ability to bundle product and application support—advantages that translate into differentiated value beyond spot pricing.
- Miwon Specialty Chemical: A South Korea–based producer with targeted product positioning in radiation-curable systems. Their strengths include regional cost competitiveness and established ties with Asia-based formulators, which make them an important supplier for companies optimizing regional supply chains.
- Sanfer Noury: An Italian specialty producer focused on European markets, leveraging proximity to end users in adhesives and coatings. Their value proposition centers on service responsiveness, regulatory familiarity, and local quality certainties.
- KOHC (Kumho Oil Chemical Industrial): Part of a broader industrial portfolio, KOHC supplies INA as a complement to its acrylic monomer offerings. Its industrial scale and integration can be an advantage for large-volume customers seeking stable throughput and single-vendor simplicity.
Collectively, the top three to five firms exert a measurable influence on pricing and availability, underscored by the market concentration ratios included in our analysis. That dynamic creates winners and losers depending on a buyer’s negotiation leverage, geographic exposure, and willingness to pay for ancillary services (technical support, low-carbon certificates, guaranteed delivery windows).
Strategic implications for manufacturers and buyers in 2026
- For producers: Prioritize feedstock security and decarbonization pathways. Options include long-term upstream contracts, selective backward integration, or investment in lower-emission production technologies. Consider strategic partnerships with formulators to co-develop low-carbon product grades that command a premium in regulated markets.
- For buyers (formulators, adhesive and coatings OEMs): Reassess supplier qualification criteria to incorporate embedded emissions and supply resilience. Move beyond price-only sourcing by introducing a two-track procurement strategy—spot coverage for flexibility and contracted volumes for security and traceability.
- For investors and M&A teams: Target assets that combine technical IP, regional logistical advantages, and decarbonization credentials. Given the moderate-to-high concentration in the industry, bolt-on acquisitions that expand technical capabilities or market access are likely to deliver higher value than purely capacity-driven plays.
Scenario planning: three plausible 2026–2028 trajectories
Our scenario framework—detailed in the full report—helps executives stress-test investments and contracts across three pathways: Baseline (gradual recovery and 5–6% CAGR), Feedstock Shock (sustained upstream tightness with margin pressure), and Low-Carbon Premium (policy-driven demand for certified low-emission volumes). Each scenario is mapped to actionable operational responses, pricing frameworks, and suggested contract structures to protect margin and market share.
What PW Consulting’s report delivers (practical contents)
The published study is designed as an operational toolkit for the 2026 planning cycle. Key deliverables include:
- Bottom-up market model with historical shipment series and a transparent forecasting engine (2020–2032) that supports sensitivity testing against feedstock and demand shocks.
- Supply-side database detailing producer footprints, capacity typologies, and qualitative capacity-addition timelines.
- Competitive profiles and capability matrices for leading and challenger suppliers, emphasizing formulation support, geographic reach, and decarbonization readiness.
- Procurement playbooks and sample contract clauses for volume security, pass-through mechanisms, and carbon attribution.
- Risk and opportunities matrix, including regulatory exposure mapping (CBAM implications) and feedstock vulnerability scoring based on recent market observations.
- Actionable M&A screening criteria with hypothetical deal scenarios, valuation sensitivities, and integration risk checklists.
- Appendices with primary research transcripts, methodology notes, and data tables—designed for executive and operational use.
How leading firms should use this intelligence in 2026
We recommend three immediate steps for senior executives:
- Initiate a supplier carbon audit and include carbon-cost forecast scenarios in budget planning to model CBAM impacts on supply economics.
- Lock in a portion of 2026–2027 volumes under dual-track agreements: fixed-price collars with an embedded carbon reconciliation clause and a flexible tranche priced to market, enabling tactical arbitrage during dislocations.
- Prioritize R&D and customer co-development on low-emission or differentiated INA-based formulations to capture margin upside as buyers pay a premium for sustainability and performance.
Conclusion — how this report creates strategic value
For decision-makers planning resource allocation, contractual commitments, or M&A activity in 2026, our INA market intelligence turns complexity into a structured set of choices. By quantifying the market trajectory (USD 218.45 Million in 2025 to USD 316.72 Million in 2032 at a 5.45% CAGR) and overlaying the latest supply, feedstock, and regulatory signals, PW Consulting gives you a defensible basis for negotiating supply, prioritizing investments, and designing risk-mitigating commercial terms. The full report elaborates the data, scenario outputs, and executable playbooks that operational teams can implement immediately.
Next steps
To access the complete dataset, granular segmentation tables, and our primary-source interview extracts that underpin these conclusions, visit the PW Consulting report page for the Worldwide Isononyl Acrylate Market. The full analysis is purpose-built to support 2026 planning cycles and will equip your team to convert market intelligence into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Isononyl Acrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Network Telemetry Market to Explode from USD 1.05B in 2025 to USD 6.06B by 2032 — 28.45% CAGR
By pmarketresearch, 2026-07-15
Worldwide Network Telemetry Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises and service providers accelerate digital transformation, network telemetry has moved from a niche operational tool to a strategic capability. PW Consulting’s latest market research — the Worldwide Network Telemetry Market report (base year 2025, forecast 2026–2032) — synthesizes five years of historical data and presents an action-oriented roadmap for 2026 decisions. This preview highlights the report’s strategic value, major market dynamics, vendor positioning, and the practical guidance executives need to align investments with intent-driven networking, observability, and AI-driven operations.
Worldwide Network Telemetry Market
Why network telemetry matters for 2026 strategy
-
Telemetry is the data fabric that enables AI/ML-driven network operations. Modern observability pipelines turn high-frequency state and flow information into predictive insights for assurance, anomaly detection, and automated remediation. For 2026, telemetry strategy is equivalent to a platform strategy: it determines which analytics, security, and automation capabilities an organization can unlock.
Worldwide Network Telemetry Market -
Economic and operational constraints are changing investment priorities. With sustained capital discipline across industries, telemetry programs must demonstrate measurable ROI in the first 12–24 months through reduced incident MTTR, network capacity optimization, and automation-driven operational efficiency.
Worldwide Network Telemetry Market -
Regulation and standards are narrowing viable design choices. From data minimization requirements in the EU to protocol standardization efforts, enterprises must architect observability pipelines that are privacy-compliant, interoperable, and resilient to supply-chain constraints.
Market trajectory in one look
Between 2020 and 2025 the network telemetry market experienced rapid expansion: the report documents a multi-year climb from early adoption to broad commercial deployment. The market size crossed the billion-dollar milestone in our 2025 base year and is forecast to continue expanding quickly in 2026 and beyond. PW Consulting projects a compound annual growth rate (CAGR) of 28.45% over the 2026–2032 forecast horizon, reflecting accelerating demand for streaming telemetry architectures, in-band network telemetry, and analytics platforms. By 2032 the market trajectory points to several-fold growth relative to the early-2020s baseline, driven by cloud-scale observability and the operationalization of network telemetry into security, capacity planning, and SRE workflows.
Note: this preview intentionally omits granular regional and segment breakdowns — the full report provides the detailed segmentation and financials required for budgeting and vendor shortlists.
Report deliverables: what you get from PW Consulting
-
Executive summary and investment thesis: Clear articulation of the market opportunity, risk factors, and strategic playbooks for technology and procurement leaders.
-
Market sizing and forecast model (2020–2032): Transparent methodology, scenario analyses (base, accelerated, constrained), and sensitivity tables for unit-cost, bandwidth, and energy assumptions.
-
Operational playbooks: Deployment checklists for cloud, edge, and on-premises telemetry pipelines; data retention and minimization templates aligned to privacy rules; and integration patterns for SIEM, AIOps, and observability stacks.
-
Vendor scorecards and go-to-market maps: Comparative assessments across product capabilities, ecosystem integrations, professional services, and partner channels — enabling fast shortlists for RFPs.
-
Financial impact tools: TCO/ROI calculators, energy-and-capacity cost models, and phased investment roadmaps designed for CIO/CFO alignment.
-
Case studies and reference architectures: Real-world examples of telemetry-driven automation and incident reduction across cloud providers, telcos, and large enterprise networks.
Competitive landscape — who leads, who follows, and what to watch
The market is commercially competitive but concentrated: a limited set of incumbent network vendors and cloud-native analytics providers command significant influence over standards, telemetry protocols, and platform integrations. Our competitive analysis focuses on capability vectors that matter for 2026: protocol support (gNMI/gNOI, gRPC, IPFIX), silicon and NOS telemetry integration, cloud-native ingestion, and security/processing pipelines.
-
Cisco Systems (San Jose, CA, USA) — Continues to be a major market force with Model-Driven Telemetry (MDT) implementations across IOS XR, NX-OS, and Catalyst platforms. Cisco’s recent software updates have improved gRPC performance and support for AI-driven analytics, positioning it as a default choice for large enterprises seeking end-to-end vendor continuity. Cisco’s ecosystem strength and wide field footprint make it central to many migration roadmaps.
-
Juniper Networks (Sunnyvale, CA, USA) — Juniper’s Junos Telemetry Interface (JTI) and recent addition of gNOI support broaden its streaming and configuration telemetry capabilities. Juniper is favored in environments requiring high-frequency operational state streaming with a strong affinity in service provider and cloud edge deployments.
-
Arista Networks (Santa Clara, CA, USA) — With EOS eAPI, gNMI telemetry, and CloudVision, Arista targets cloud-scale data centers where programmability and developer tooling (e.g., AVA) matter. Expect Arista to lead in use cases that prioritize telemetry extensibility and low-latency pipeline integration.
-
Nokia (Espoo, Finland) and Broadcom (San Jose, CA, USA) — Nokia’s SR OS telemetry and Broadcom’s ASIC-level telemetry export capabilities are influential for carrier and hyperscaler architectures where hardware-level visibility matters.
-
Huawei (Shenzhen, China) — Continues to integrate native telemetry across router families and management stacks. Geopolitical restrictions, however, shape where Huawei hardware and telemetry tooling can be deployed.
-
Extreme Networks , Palo Alto Networks , F5 Networks , and cloud-native analytics providers like Kentik — Represent complementary capabilities: from fabric-wide telemetry and security-centric streaming to application-delivery telemetry and cloud-native ingestion/analytics.
Recent vendor developments underscore the pace of innovation: Cisco’s IOS XR telemetry enhancements, Juniper’s gNOI support, and Arista’s AVA tooling all reflect an industry push toward standardized, high-frequency streaming combined with developer-friendly customization.
Regulatory, standards, and geopolitical dynamics shaping 2026 decisions
-
Standards: IETF’s formalization of gNMI and related model-driven telemetry standards has reduced interoperability friction. Enterprises should prioritize vendor support for these standards to avoid vendor lock-in at the data model layer.
-
Privacy and data minimization: GDPR Article 25 and similar privacy frameworks require instrumentation to be designed with minimization and purpose limitation in mind. Telemetry collectors and pipelines must support selective sampling, field redaction, and retention controls as first-class features.
-
Regulatory access and neutrality: Recent regulatory actions around network neutrality and permissible traffic handling affect how ISPs and telcos expose telemetry. Organizations relying on transit-level telemetry should validate contractual commitments and platform neutrality clauses.
-
Geopolitics and supply chain: Export controls and entity-list restrictions impact platform selection for certain regions and use cases. Procurement teams must incorporate compliance reviews and alternate sourcing plans into 2026 purchasing cycles.
-
Operational costs: Energy and data center processing costs are non-trivial; telemetry strategy must balance sampling frequency, edge pre-aggregation, and cloud ingestion economics to stay within acceptable TCO boundaries.
Practical recommendations for enterprise leaders — a 2026 checklist
-
Define telemetry as a platform investment, not a point product. Commit to an open, standards-based data model to maximize reuse across security, SRE, and business analytics teams.
-
Prioritize streaming telemetry for real-time automation, but assess hybrid approaches where in-band telemetry and sampled flow data can reduce processing costs. Use staged rollouts with measurable KPIs (MTTR reduction, automation coverage, cost per event).
-
Embed privacy and compliance controls into ingestion and storage. Require vendors to demonstrate support for field-level redaction, retention policies, and data minimization by design.
-
Negotiate procurement terms that include protocol and data portability guarantees. Given the market’s moderate concentration, ensure exit and interoperability clauses to avoid strategic lock-in.
-
Invest in edge pre-processing and adaptive sampling to manage energy and compute costs, particularly for distributed and IoT-heavy deployments.
-
Use the PW Consulting vendor scorecards and TCO models to run three-year investment scenarios and validate budgetary allocations with the CFO and SRE leads before procurement.
How the full PW Consulting report helps you act
This preview highlights the strategic contours of the network telemetry market for 2026. The full Worldwide Network Telemetry Market report provides the operational details organizations need to act confidently: granular scenario-based financials, vendor-by-capability matrices, validated deployment reference architectures, and a step-by-step migration playbook from SNMP/flow-based approaches to streaming-first observability. For teams that must deliver measurable operational improvements in the coming 12 months, the report reduces decision friction by combining market economics, technical due diligence, and procurement-ready templates.
Conclusion — positioning for advantage in 2026
Network telemetry is no longer an optional visibility tool; it is the substrate for secure, resilient, and automated digital infrastructure. With market expansion accelerating and standards converging, 2026 will reward organizations that treat telemetry as a strategic platform: selecting standards-aligned vendors, embedding privacy and cost controls, and operationalizing telemetry data into closed-loop automation. PW Consulting’s report equips leaders with the market intelligence and executable playbooks necessary to turn telemetry investments into measurable business outcomes.
To access the full dataset, vendor comparisons, and deployment playbooks that underpin these strategic recommendations, please refer to the PW Consulting report landing page for the complete Worldwide Network Telemetry Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Network Telemetry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Automotive Clamp Market to Expand at 4.6% CAGR as Asia‑Pacific Emerges Dominant
By pmarketresearch, 2026-07-15
Worldwide Automotive Clamp Market — Strategic Outlook to 2032
Executive preview from PW Consulting
The global market for automotive clamps is on a steady, engineering-driven growth path that matters to OEM procurement teams, tier‑one suppliers, private equity investors, and manufacturing strategists planning for 2026 and beyond. Our new report — Worldwide Automotive Clamp Market (base year 2025, forecast 2026–2032) — synthesizes historical performance, supply‑chain fragilities, regulatory pressures, and competitive moves into an actionable playbook. In aggregate terms, the market has continued to expand through the mid‑2020s and is projected to grow at a mid‑single‑digit compound annual growth rate (CAGR) through 2032, elevating the total market size materially by the end of the forecast window.
Worldwide Automotive Clamp Market
Why this matters for 2026 decisions
- Procurement certainty: With steel and stainless‑steel inputs comprising the majority of production cost for clamps, raw material price volatility can materially alter supplier economics in 12–24 months. Buyers who lock in flexible cost‑pass clauses or secure hedged sourcing will preserve margin and reduce supply risk.
- Manufacturing footprint choices: Automation and capacity investments made in 2024–2025 are already shifting competitive dynamics; suppliers with recent capacity expansions are positioned to capture short‑cycle OEM awards in 2026. Our scenario modelling shows near‑term capacity readiness is a distinguishing factor in supplier selection.
- Product architecture and vehicle programs: Lightweighting and thermal performance are not peripheral: clamp choices influence vehicle mass budgets and thermal integrity across powertrain, cooling, and exhaust systems. Decisions on clamp type and material should be integrated into early vehicle architecture trade‑offs to avoid late‑stage rework.
Market trajectory — concise numbers, strategic implications
Using 2025 as our analytical base, PW Consulting’s baseline forecast anticipates continued market expansion through 2032 at roughly a 4.6% CAGR. That trajectory reflects a combination of steady OEM production volumes, incremental electrification (which redistributes but does not eliminate clamp demand), rising thermal management complexity in both ICE and EV platforms, and ongoing replacement/aftermarket activity. For 2026 specifically, the market grows modestly from the 2025 base — a near‑term continuation of recent recovery and investment cycles rather than a structural inflection.
Worldwide Automotive Clamp Market
Competitive landscape — what buyers and investors need to know
The clamp sector exhibits moderate concentration: the top three suppliers account for a significant share of global revenue, and the top five increase that share materially. This concentration profile creates both risk and opportunity for buyers and private capital. On the one hand, scale players offer reliability, engineering depth, and global footprints; on the other, mid‑tier and regional specialists provide localized agility and tailored product innovations.
Worldwide Automotive Clamp Market
- NORMA Group (Germany): A benchmark for engineered joining technologies, NORMA’s extensive portfolio across worm‑drive, V‑band, and high‑temperature profile clamps positions it strongly for OEM programs requiring integrated sealing solutions. Recent investments in automated clamp production increase scale and cost competitiveness.
- Oetiker Group (Switzerland): Known for single‑ear and multi‑ear solutions, Oetiker differentiates on low‑profile, vibration‑resistant designs favored in fast‑assembly lines and compact packaging environments.
- Ideal‑Tridon Group (US): With a century‑plus heritage, Ideal‑Tridon’s breadth across worm gear, T‑bolt, and constant‑tension clamps—and its expanded distribution network—makes it a reliable partner for both OEMs and heavy‑duty applications.
- Murray Corporation, Breeze (NORMA Americas), Clampco, Mikalor, Rotor Clip, Jolly Clamps, King Seal, Auto Clamp: This mix of global and regional players supplies differentiated strengths—custom engineering, performance exhaust clamps, high‑temperature solutions, and compliance‑focused production—that shape tender outcomes and aftermarket competition.
Recent industry movements underscore the strategic jockeying underway: examples include product launches that reduce component weight (directly supporting OEM lightweighting targets), expanded distribution footprints that shorten lead times, and capacity additions that de‑risk supplier bottlenecks. These are the operational signals procurement teams should monitor as part of supplier scorecards in 2026.
Key dynamics shaping supply and demand
- Raw material sensitivity: Steel and stainless steel represent the dominant input cost for clamps. Price volatility and supply disruptions can add a double‑digit percentage to manufacturing costs in stressed scenarios. Suppliers with diversified metal procurement, long‑term contracts, or alternative material capability (e.g., advanced alloys, coated steels) will be advantaged.
- Regulatory and specification pressures: Automotive clamps must align with industry quality standards such as IATF 16949, and specific types adhere to test protocols (for example, standards covering worm‑drive performance). Thermal and vibration resilience remains mission‑critical—particularly for exhaust and turbo systems where temperatures can exceed conventional limits.
- Design and materials innovation: Lightweighting is driving adoption of advanced materials and re‑engineered clamp geometries to shave component mass without compromising clamp torque and sealing integrity. High‑temperature profile clamps engineered for extreme exhaust environments are increasingly relevant for both high‑performance ICE vehicles and boosted combustion platforms.
- Functional complexity with electrification: EVs reconfigure fluid and thermal subsystems rather than eliminate them. Cooling loops for battery, inverter, and power electronics, plus e‑motor thermal management, create specialized clamp requirements—often favoring constant‑tension or spring-loaded designs to accommodate cyclic thermal expansion.
Practical, actionable contents of the PW Consulting report
The report is designed as a decision tool for 2026 strategy setting. It includes:
- Top‑down market sizing and time‑series growth analysis (historical 2020–2025 and detailed 2026–2032 forecast scenarios), with sensitivity modelling for raw‑material and vehicle production shocks.
- Segment‑level frameworks (by product architecture, application family, and geography) that help prioritize R&D and commercial focus — presented as decision matrices rather than raw granular disclosure in this preview.
- Supplier benchmarking, including capability maps, technology positioning, and go‑to‑market footprints for global, regional, and niche players.
- Supply‑chain stress tests that quantify the impact of metal price swings, lead‑time extensions, and tariff/regulatory shifts on cost structures and supplier viability.
- Commercial playbooks for OEMs and suppliers: sourcing strategies, near‑shoring vs. low‑cost location trade‑offs, contract structures to share raw material risk, and integration checklists for early vehicle program phases.
- Technology deep dives on lightweight materials, high‑temperature profiles, constant‑tension designs, and assembly automation — with engineering performance considerations and typical cost‑benefit timelines.
- M&A and partnership pipeline analysis highlighting value creation levers for scale consolidation, capability acquisition, and regional roll‑ups.
How executives should use this intelligence in 2026
- Supply strategy: Revise supplier scorecards to weight capacity readiness and raw‑material sourcing strategies as highly as unit price. Where possible, secure optionality through approved‑vendor lists rather than single‑source commitments.
- Product integration: Treat clamp selection as an early systems decision in vehicle architectures — especially for thermal and exhaust systems. Bring clamp engineers into vehicle program gating to avoid late cost and performance corrections.
- Investment focus: Prioritize investments in automation and high‑temperature manufacturing capability if targeting premium powertrain or performance segments. For financial sponsors, target firms with proprietary clamp geometries or materials know‑how that enable higher margin retrofit or aftermarket products.
- Risk management: Build inflationary scenarios into supplier contracts and consider collaborative hedging for critical metal inputs. Evaluate near‑term inventory strategies for high‑risk commodities without creating excess obsolescence exposure.
Where the report adds unique value
PW Consulting’s analysis combines engineering sensitivity (thermal, vibration, and material science constraints) with commercial market modelling to bridge the common gap between product engineering and procurement decision‑making. Rather than present raw segment figures upfront, our study translates those internal data into prioritized action items — enabling executives to make faster, higher‑confidence choices in 2026 while preserving the granularity for licensed subscribers who need to execute tactical moves.
Next steps — get the full dataset and supplier dossiers
This preview highlights the strategic contours and decision imperatives. For procurement teams, investors, and OEM program leads seeking the underlying segment matrices, supplier scorecards, and full scenario outputs (including the granular product and regional splits not shown here), please visit the PW Consulting report page. The full report contains the detailed figures, appendices with supplier contact maps, and editable Excel models you can integrate directly into 2026 planning workflows.
PW Consulting remains available to brief executive teams, run bespoke supplier due‑diligence projects, and co‑develop procurement strategies keyed to 2026 program calendars. In a market where small design choices cascade into program costs and thermal reliability, the right intelligence now determines competitive position tomorrow.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.35% CAGR for Worldwide Drill Stabilizer Market Through 2032
By pmarketresearch, 2026-07-15
Worldwide Drill Stabilizer Market — Strategic Outlook 2026: A PW Consulting Executive Brief
PW Consulting’s new market research release on the Worldwide Drill Stabilizer market offers a concise, decision-focused intelligence package for operators, OEMs, private equity, and procurement teams planning investments and sourcing strategies in 2026. Built from a detailed historical assessment (2020–2025) and a seven-year forecast horizon (2026–2032), this briefing distills the strategic implications of market dynamics without revealing the granular segment tables reserved for the full report.
Worldwide Drill Stabilizer Market
Executive summary — why this report matters for 2026 planning
The drill stabilizer market is transitioning from cyclical recovery toward a multi-year expansion driven by renewals in drilling programs, incremental emphasis on directional drilling efficiency, and technology-driven product differentiation. Our analysis shows the global market reached USD 932.4 Million in the base year (2025). Despite a near-term softness in early 2026, the market resumes growth at a compound annual growth rate (CAGR) of roughly 5.35% over the forecast period, arriving materially larger by 2032. For executives refining 2026 capex, supplier contracts, and M&A pipelines, this profile implies careful timing: act too early and you absorb short-term price and supply volatility; act too late and you risk losing access to differentiated products and rental capacity.
Worldwide Drill Stabilizer Market
What’s behind the numbers — demand, supply and cost drivers
-
Core technical role of stabilizers: Drill stabilizers remain indispensable components of bottom hole assemblies (BHA). They directly influence borehole trajectory control, reduce vibration, and improve bit life in both vertical and directional wells. These performance attributes translate to measurable drilling efficiencies that operators target as day rates and operational complexity increase.
Worldwide Drill Stabilizer Market -
Raw material and input-cost pressure: Stabilizers are manufactured from high-strength alloy steels (commonly AISI 4145H mod) with hardfacing used on leading surfaces. Steel market volatility through 2025 introduced upward cost pressure across the supply chain. Procurement teams should plan for continued pricing sensitivity in 2026, particularly where replenishment of rental fleets and refurbishment programs are planned.
-
Standards and compliance: API compliance (especially rotary-shouldered connection and material specifications) remains a gating factor for tier-one projects and international tenders. Quality and traceability will continue to be decisive differentiators, especially for operators working in regulated basins and deepwater programs.
Market structure and competitive dynamics
The market demonstrates a mid-level concentration: a handful of established vendors and regional specialists collectively control a dominant share of revenue and rental inventory, while a deeper long tail of regional manufacturers serves localized needs. This structure creates a dual path for strategies: partner with top-tier vendors to secure reliability and aftermarket services, or leverage regional suppliers for cost optimization and rapid lead-times where certification requirements allow.
Leading firms profiled in our research illustrate these archetypes:
-
Stabil Drill (United States) — An integrated manufacturer and rental fleet operator focused on custom-engineered stabilizers for demanding drilling programs. Their large rental base and in-house engineering create advantages for operators seeking turnkey BHA solutions and rapid deployment.
-
Drilling Tools International (United States) — A broad product portfolio including multiple stabilizer formats and engineered variants. Strengths lie in product breadth and application guidance for directional drilling challenges.
-
Vigor Drilling, Landrill, Saigao and other China-based manufacturers — These suppliers offer competitively priced engineering and manufacturing capabilities, including API-certified product lines and specialized options such as non-magnetic and hardfaced designs. Their value proposition is particularly compelling for large-volume replenishment cycles and markets where delivery speed and unit economics are decisive.
-
Gulf States Drilling Supply (United States) — Positions itself as a durable-equipment specialist, emphasizing reconditioning and rebuild services that extend useful life and reduce total cost of ownership for rental fleets.
Recent vendor activity underscores an industry investing in technical guidance and product clarity: Torrent Oil Tools updated its product information in May 2025 outlining stabilizer selection rationale; Sinodrills refreshed its guidance in March 2026; and Welong published educational product material in September 2025. These moves reflect a broader shift toward consultative selling and knowledge-based differentiation.
What the PW Consulting report contains — practical, operational chapters
Our full report is organized to support active decision-making across procurement, operations and corporate development. Key deliverables include:
- Comprehensive market sizing and seven-year scenario forecasts with sensitivity analysis to steel-price and drilling activity shocks.
- Supply-chain mapping including supplier capacity, regional manufacturing nodes, and logistics risk scoring.
- Vendor benchmarking and scorecards covering quality, certification, rental fleet capability, aftermarket support and lead-times.
- Product taxonomy and performance matrix for major stabilizer types, with guidance on selecting designs for common drilling profiles (vertical, directional, high-wear environments).
- Cost model and procurement playbook to optimize total cost of ownership (TCO) — including refurbishment strategies, hardfacing choices and rental vs. buy decision trees.
- M&A and partnership heatmap highlighting targets by strategic fit: bolt-on manufacturing, rental fleet expansion, or technology acquisition.
- Case studies and operational KPIs demonstrating realized drilling efficiency improvements from optimized stabilizer selection and fleet management.
Note: To preserve competitive value for clients and readers, core subsegment tables (detailed regional and application revenue splits, and granular price points) are available exclusively in the full report and on our website.
Strategic implications for 2026 — recommended actions
-
Procurement posture: Adopt a blended sourcing model. Secure minimum guaranteed capacity with tier-one, API-compliant suppliers for critical wells while maintaining relationships with regional manufacturers for volume flexibility and price negotiation.
-
Capex timing: Defer large-scale purchases until mid-2026 where possible; prioritize refurbishment and hardfacing programs to bridge the near-term softness and preserve cash. Use scenario triggers tied to steel-price normalization to time larger acquisitions.
-
Operational optimization: Implement field-level KPIs linking stabilizer condition and BHA configurations to measurable drilling efficiency metrics. Small gains in ROP and reduced vibration compound into meaningful cost reductions over extended campaigns.
-
Technology and product strategy: Evaluate non-magnetic and specialized designs where well trajectories or reservoir sensitivities justify premium procurement — these options command superior value in selective applications but should be justified by lifecycle ROI analysis.
-
M&A and partnership: For sponsors, prioritize targets that offer rental fleet scale or certification-heavy capabilities in established basins. For operators, consider strategic alliances with suppliers that provide integrated engineering support and rapid turnaround on custom solutions.
Risk considerations and monitoring framework
Key risks for 2026 decisions include raw material price volatility, shifts in drilling program timing by major operators, and regulatory changes affecting API compliance or local certification regimes. PW Consulting recommends a three-tier monitoring framework:
- Leading indicators: steel coil and scrap pricing, large tenders announced by national oil companies, and rental fleet utilization rates.
- Operational triggers: elevated failure rates in field returns, increased hardfacing orders, or repeated deviations in BHA performance metrics.
- Strategic events: consolidation moves among top suppliers, changes in trade policy affecting exports, or significant product catalog updates by leading vendors.
How to use this intelligence
Leaders preparing budgets, supply agreements, and M&A pipelines for 2026 should treat the PW Consulting report as the operational playbook to translate macro forecasts into executable supplier and field-level actions. The report is designed for cross-functional use — from procurement and operations to corporate development teams — offering templates and decision rules that can be adapted to specific asset portfolios and regional regulatory environments.
Next steps
PW Consulting has intentionally packaged this briefing as a high-trust primer: it communicates directionally accurate market sizing and the strategic levers that matter for 2026, while reserving the full segment tables, vendor scorecards and downloadable procurement tools for the complete report. Organizations that require immediate operational templates, supplier shortlists with scoring, or M&A target lists should access the full dataset through our website or contact a PW Consulting industry analyst for a tailored briefing.
For access to the full Worldwide Drill Stabilizer Market report, vendor benchmarking appendices, and scenario models that underlie the forecasts, please refer to the PW Consulting publications portal. Our analysts stand ready to walk clients through customized impact modeling calibrated to specific drilling programs and procurement cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Drill Stabilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aftercooler Market to Rise from USD 2,260 Million in 2025 to USD 3,353.6 Million by 2032 at 5.82% CAGR — Air‑Cooled Segment and Asia‑Pacific Lead
By pmarketresearch, 2026-07-15
Worldwide Aftercooler Market: Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest Worldwide Aftercooler Market report (base year 2025, forecast 2026–2032) crystallizes the near‑term trajectory for an essential yet often overlooked component of compressed air systems. With the global aftercooler market estimated at approximately USD 2.26 billion in 2025 and projected to expand at a compound annual growth rate of 5.82% through 2032 (reaching a multi‑billion dollar market by the end of the forecast horizon), this sector offers meaningful strategic levers for OEMs, system integrators, end users, and investors planning capital allocation and go‑to‑market moves in 2026.
Worldwide Aftercooler Market
Why this report matters now
-
Energy and quality imperatives are converging. International standards such as ISO 8573‑1 (compressed air quality classes) and ISO 11011 (energy efficiency assessments for compressed air systems) increasingly position aftercoolers not just as accessory equipment but as primary contributors to compliance and system efficiency.
Worldwide Aftercooler Market -
Immediate downstream impact. Aftercoolers typically remove the large majority of condensate formed at the compressor outlet, materially protecting downstream dryers, filters and process equipment. This immediate improvement in air quality has direct implications for uptime, maintenance schedules and overall lifecycle cost.
Worldwide Aftercooler Market -
Financial planning for 2026 must account for material and supply‑chain volatility. Aluminium—long a preferred core material for plate‑fin aftercoolers due to its heat‑transfer characteristics and weight advantages—remains central to product cost and availability; recent market developments have driven elevated price sensitivity across manufacturer and buyer P&Ls.
-
Market scale and momentum are actionable. The 2025 market base and our 5.82% CAGR projection provide a reliable envelope for sizing opportunities, prioritizing product investments, and stress‑testing procurement strategies across short‑ and mid‑cycle scenarios.
What the report delivers — practical, transaction‑ready insight
-
Robust market sizing and seven‑year forecast (2026–2032) with transparent methodology and sensitivity bands to support conservative and aggressive planning assumptions.
-
Demand‑side segmentation (by product form factor, application clusters and buyer archetypes) with buyer economics and replacement/refurbishment cycles to inform product roadmaps and aftermarket strategies.
-
Supply‑side analysis covering manufacturing footprints, core materials and sub‑tier exposures. Special emphasis is given to plate‑fin core technologies, laser‑welded assemblies and aluminium alloy choices that influence weight, thermal performance and corrosion resistance.
-
Competitive benchmarking and vendor scorecards for established OEMs and niche specialists—covering product breadth, channel models, margin profiles, and recent M&A and partnership activity—designed for quick executive comparison.
-
Commercial tools: procurement hedging playbook, raw‑material pass‑through modelling, and a capex ROI calculator that links aftercooler selection to compressor system energy and maintenance savings.
-
Scenario analyses that stress test outcomes under alternative aluminium price paths, regulatory tightening on energy use, and accelerated adoption of integrated compressed‑air solutions.
Competitive landscape — pragmatic implications for 2026 strategy
The aftercooler market is populated by a mix of integrated compressor OEMs and focused thermal‑management specialists. Our report profiles the full spectrum—established global players (for example those headquartered in Sweden, the United States, Germany, Japan and other industrial hubs) and dedicated niche suppliers that serve mobile, blasting, and industry‑specific applications. Key insights for strategists:
-
Integrated OEM advantage: Large compressor manufacturers that bundle aftercoolers into system sales retain strong control over channel economics and aftermarket capture. Integration allows these players to frame value around system efficiency, guarantee compressed air quality, and protect service revenue.
-
Niche specialists and modular players: Companies focused on stand‑alone aftercoolers, mobile units, and high‑performance core designs compete through customization, rapid lead times, and aftermarket compatibility. These vendors can be attractive targets for OEMs seeking bolt‑on capability or for private equity looking to consolidate a fragmented category.
-
Moderate concentration, meaningful opportunity: The market concentration metrics show that a handful of firms account for a meaningful, but not overwhelming, portion of market value—indicating room for consolidation, regional champions, and targeted technology plays. For 2026, acquirers and strategic partners should prioritize capability adjacencies (water‑cooled vs. air‑cooled, mobile vs. stationary) rather than pure revenue scale.
-
Material and design differentiation: Product competitiveness will increasingly hinge on core technologies—plate‑fin heat exchangers, laser‑welded cores that reduce material use while maintaining pressure integrity, and corrosion‑resistant alloys. Firms that can combine thermal performance with lower total cost‑of‑ownership will win specification battles in capital procurement cycles.
Operational playbook — six actions PW Consulting recommends for 2026
-
Embed aftercooler selection into system ROI assessments. Treat aftercoolers as levers for energy and maintenance savings rather than commodity line items—link selection to ISO 11011 energy audits when evaluating capex projects.
-
Hedge raw‑material exposure. Establish dual‑sourcing and alloy alternatives, and renegotiate contract language to include price adjustment clauses tied to clear indices. Prioritize designs that reduce material input while preserving thermal performance (e.g., improved core geometry, laser welding).
-
Prioritize retrofit and aftermarket opportunities. Many installed bases lack optimized aftercooling; retrofit kits and service contracts can deliver rapid margin capture and customer lock‑in.
-
Recalibrate channel and warranty models. OEMs that bundle aftercoolers should align warranty liabilities with service networks to limit exposure and maximize lifecycle revenue.
-
Use competitive scorecards for deal screening. When evaluating potential targets or suppliers, weigh technology portability, manufacturing footprint, and compatibility with major compressor platforms higher than headline revenue.
-
Prepare for regulatory tightening. Integrate compressed‑air quality and energy‑efficiency requirements into product roadmaps and customer education programs; early movers will benefit as buyers seek compliant, auditable solutions.
Risks, scenarios and what to watch in 2026
-
Raw‑material volatility: Aluminium remains the dominant material for aftercooler cores; material price spikes or supply constraints will compress margins for manufacturers without hedges or design alternatives.
-
Technology substitution: Advances in drying technologies or new heat‑exchanger materials could alter product portfolios. Monitor patent activity and pilot deployments around alternative alloys and manufacturing techniques.
-
Regulatory shifts: Stricter energy and emissions reporting could accelerate replacement cycles for inefficient systems—creating upside for vendors with energy‑optimised solutions but raising retrofit financing needs for end users.
-
Channel disruption: Consolidation among distributors or the rise of e‑procurement platforms could compress transaction margins and accelerate price transparency.
How PW Consulting’s report supports decision‑making in 2026
For executives planning capital investments, supplier negotiations, or M&A activity in 2026, this report translates market scale and dynamics into executable plans. Our modelling links the 2025 market base and the 5.82% CAGR projection to tariff, commodity and energy scenarios—giving boards and business unit leaders an evidence‑based foundation for setting budgets, prioritizing R&D, and structuring commercial arrangements.
We intentionally present a strategic preview here: the full report contains the granular segmentation tables, regional and application breakouts, vendor financial proxies, and downloadable decision tools that procurement teams, product managers and corporate development professionals will use to act this year. To access the complete datasets, vendor scorecards, and the executable playbook for 2026, visit the PW Consulting Worldwide Aftercooler Market report page or request an executive briefing with our senior analyst team.
For detailed analysis of this topic, please visit the official page: Worldwide Aftercooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Canoe‑Kayak Accessories Market Poised for 5.0% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Canoe‑Kayak Accessories Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s new market study on Worldwide Canoe‑Kayak Accessories provides a tightly focused playbook for commercial leaders making buy, build, price, and go‑to‑market decisions in 2026. The analysis combines multi‑year market sizing, scenario forecasting, supply‑chain diagnostics, competitor intelligence and executable growth options — all calibrated to the realities of rising raw‑material costs, shifting labor pools, and tightening regulatory regimes. This briefing summarizes the report’s strategic value while preserving the premium, segmented detail reserved for report subscribers.
Worldwide Canoe-Kayak Accessories Market
Why this report matters for decisions in 2026
-
Timing: 2026 is the pivot year in our forecast cycle. The industry moves from a post‑pandemic re‑acceleration period into a structurally higher cost and compliance environment. PW Consulting’s base year is 2025, and our multi‑scenario outlook covers 2026–2032 so executives can test tactical moves against both baseline and stress scenarios.
Worldwide Canoe-Kayak Accessories Market -
Clarity at scale: The global accessories market for canoes and kayaks has expanded materially over the 2020–2025 historical window and continues to grow. Our consolidated market sizing shows an industry that reached approximately USD 840 Million in 2025 and is projected to approach USD 1.18 Billion by 2032 under the baseline runway — a compound annual growth in the mid‑single digits. Those headline numbers are crucial for board‑level resource allocation and investor conversations.
Worldwide Canoe-Kayak Accessories Market -
Action orientation: The study is structured to convert insight into immediate actions — supplier negotiations, SKU rationalization, channel reweighting, and M&A prioritization — rather than merely cataloguing trends.
Market trajectory — what the headline numbers imply
PW Consulting’s baseline forecast embeds a 5.0% CAGR for the forecast period. That rate reflects a combination of sustained participation growth in paddle sports, product premiumization (electronics mounts, modular track systems, performance safety gear), and the rising popularity of fishing‑specific accessories. For 2026, the market expands beyond 2025’s level, reinforcing the case for incremental investment in product R&D and channel infrastructure. By 2032 the market size under baseline assumptions signals meaningful total addressable market expansion for firms that successfully execute against product, channel and supply‑chain levers.
Importantly, the market remains fragmented: the top suppliers collectively control a modest share of total revenues, leaving significant whitespace for category specialists and digitally native entrants to scale. For incumbent manufacturers and distributors, that fragmentation translates into both risk (price competition) and opportunity (consolidation and national roll‑outs of proven concepts).
Key dynamics shaping 2026 choices
-
Input cost pressure: Nylon webbing, a ubiquitous input in deck rigging and carry systems, has seen double‑digit price movement driven by petrochemical feedstock volatility. Simultaneously, injection‑molding labor costs in important offshore hubs rose materially, putting margin pressure on commodity plastic components. Companies must decide whether to absorb, pass through, or re‑engineer cost structures.
-
Regulatory tightening: Compliance is increasingly front and center. For example, safety equipment requirements for commercial rental fleets have been clarified by maritime authorities, and lead‑free component certification is mandatory in some markets. These changes raise the effective cost of entry for some SKUs and create differentiation opportunities for certified suppliers.
-
Retail and channel maturity: Online platforms continue to gain share alongside specialty retailers. Buyers are sensitive to delivery times, returns policies, and rich product content (installation videos, fitment guides). The competitive battleground is shifting toward omnichannel inventory orchestration and performance marketing for higher‑margin accessories.
-
Product modularity and add‑ons: Accessories that support electronics (mounts for fish finders and phones), modular track systems, and quick‑attach fishing solutions are driving average selling price uplift in some categories. This trend favors suppliers with IP around modularity, tooling breadth and professional‑grade fitments.
Practical contents of the PW Consulting report
The report is intentionally operational. It includes:
-
Proprietary market model (2020–2032) with scenario switches to test downside commodity shocks, accelerated regulation, and channel disruption.
-
Supplier economics playbook: cost‑to‑serve benchmarks by product family, a supplier risk heatmap, and recommended sourcing hedges (dual‑sourcing, regional tool investments, material substitutions).
-
Commercial tools: SKU rationalization matrix, go‑to‑market scorecard for direct vs distributor channels, and a digital commerce readiness assessment.
-
Regulatory and compliance checklist aligned to major export markets (certifications, labeling, material restrictions) with implementation timelines and cost estimates.
-
Deal origination pack for M&A or JV activity: target screening criteria, valuation multiples observed in recent cross‑border outdoor acquisitions, and post‑deal integration checklists focused on tooling, inventory harmonization and brand migration.
-
Executive workshops and an editable Excel model so teams can run proprietary scenarios informed by their own input assumptions.
Competitive landscape — who to watch and why
The market features a mix of specialty brands, marine hardware players, and outdoor incumbents. PW Consulting’s competitive review synthesizes product portfolios, channel footprints and recent strategic moves to highlight who will be most active in 2026 consolidation and innovation.
-
YakGear (Charleston, SC): A specialist in outriggers and stability systems that has recently commercialized enhanced outrigger pontoons. Their product focus addresses the fishing segment and signals continued investment into utility attachments that can be retrofitted across hull types.
-
Railblaza (Auckland): Focused on modular track accessories and compatible Quikmount systems, the company’s recent TracLoader launch underscores the competitive advantage of universal interface standards and accessory ecosystems.
-
Scotty (Sumas, WA): A long‑standing supplier of fishing mounts and mounting systems; product catalog updates show steady portfolio refinement toward in‑boat utility for anglers.
-
RAM Mounts (West Des Moines, IA): Their moves into vibration‑resistant mounts for electronic devices illustrate how ruggedized consumer electronics accessories are becoming a growth vector.
-
Wilderness Systems, Perception Kayaks and Old Town: These hull manufacturers continue to leverage accessories (crate systems, rigging kits, carry aids) for premiumization and cross‑sell. Expect OEM tie‑ins and co‑branded accessory bundles to increase.
-
Harmony Gear, NRS and Aquaglide: Each occupies specialized niches — from soft goods to whitewater safety to inflatable accessories — and collectively they underscore the market’s breadth and the tactical route to scale through focused category leadership.
Recent product launches and SKU renewals tracked in the report demonstrate that innovation is incremental and pragmatic: modular mounts, stability pontoons, and ruggedized electronic mounts dominate recent releases. That pattern favors players who can iterate quickly on tooling and leverage existing distribution partnerships.
Strategic playbook for 2026
-
Product and pricing: Prioritize margin recovery through premiumized SKUs (certified safety gear, electronics mounts) while rationalizing commoditized SKUs with thin margins. Introduce value packs for rental and fleet customers to lock recurring revenue.
-
Sourcing: Hedge nylon and resin exposure with multi‑sourcing and longer‑dated purchase agreements. Evaluate near‑shoring selective components to mitigate rising offshore labor costs.
-
Channel: Accelerate omnichannel fulfillment and D2C skus for high‑margin accessories; maintain specialty retailer partnerships for reach and after‑sales service.
-
Compliance as differentiation: Invest in certifications (REACH‑compliant, lead‑free weights) as go‑to‑market differentiators, particularly for EU and rental customers where regulatory adherence is a procurement criterion.
-
M&A and partnerships: Target bolt‑on acquisitions that add tooling capacity, proprietary mounting standards, or access to rental fleet channels — validated in the report’s target screen.
How PW Consulting supports execution
Subscribers receive the full dataset, editable models, and a facilitator‑led 90‑minute strategy workshop that translates report insights into a 100‑day plan. We deliberately withhold certain granular segmentation tables in public summaries to safeguard the commercial value of the underlying research; licensed clients obtain full access to regional, product and channel splits, plus our primary‑research transcripts.
Next steps for executives
For leaders planning capital deployment, channel reconfiguration, or M&A in 2026, the report provides the evidence base and practical toolset to reduce execution risk. PW Consulting recommends a short diagnostic (2–3 weeks) to calibrate the report’s model to your P&L and a subsequent transformation or transaction sprint aligned to top priorities.
To obtain the full intelligence suite (detailed segment tables, company scorecards and the editable forecasting model), please contact PW Consulting. The public briefing showcased here outlines the strategic contours; the licensed report contains the precise data and playbooks your team will need to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Canoe-Kayak Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MS Polymer Market Set to Reach USD 9,280.12 Million by 2032, Report Finds
By pmarketresearch, 2026-07-15
Worldwide MS Polymer Market — Strategic Outlook 2026: Why PW Consulting’s New Report Is Essential for Executive Decision-Making
Executive snapshot
PW Consulting today releases the Worldwide MS Polymer Market report (base year 2025, forecast 2026–2032), a practitioner-oriented study designed to convert market intelligence into executable strategy. Our model pegs the global MS polymer market at approximately USD 5.78 billion in 2025, growing to an estimated USD 6.16 billion in 2026 and projecting to exceed USD 9.28 billion by 2032 — a compound annual growth rate of roughly 7.0% across the forecast window. These headline metrics underline not only a resilient growth trajectory but also the increasingly strategic role that silyl-terminated polymers (MS polymers) play in construction, transportation, industrial assembly, and adjacent segments.
Worldwide MS Polymer Market
Why this matters for 2026 strategy
2026 is shaping up to be a decision-rich year for manufacturers, ingredient suppliers, formulators, and downstream integrators. Capital allocation, capacity siting, product roadmaps, and partnerships initiated now will determine whether organizations capture disproportionate share as the market scales. Our report translates market growth into clear, prioritized actions that are directly actionable in 2026 — from near-term capacity and procurement choices to 3–5 year R&D and M&A plays.
Worldwide MS Polymer Market
What PW Consulting delivers — practical, implementable content
- Robust market model: a bottom-up demand and revenue model (USD Million basis) covering 2020–2025 historicals and a 2026–2032 forecast with scenario sensitivity to raw-material volatility and regulatory shifts.
- Scenario playbooks: three stress-tested scenarios (Base, Upside, Supply-Constrained) that quantify impacts on price, margin, and working capital for integrated producers and formulators.
- Go-to-market and channel analytics: practical guidance on distribution, formulation partnerships, and specification strategies to accelerate adoption in construction and industrial channels.
- Regulatory and sustainability pathways: compliance checklists and reformulation roadmaps to align MS polymer product portfolios with tightening VOC and indoor air quality standards.
- Supply chain resilience toolkit: a prioritized set of sourcing alternatives, nearshoring indicators, and inventory hedging rules calibrated to real-world lead times for MS polymer precursors.
- Deal flow and competitive playbook: identification of acquisition targets, partnership archetypes, and valuation heuristics tailored to hybrid adhesive and sealant portfolios.
Market dynamics framing — drivers, constraints, and inflection points
MS polymers are benefiting from multiple secular tailwinds that together underpin the 7.0% CAGR we forecast. First, regulatory momentum: isocyanate-free, solvent-free, and low-VOC formulations increasingly satisfy stringent indoor-air and occupational-exposure rules across key construction markets. Second, end-user preference: MS polymer hybrids combine high adhesive performance with ease-of-use properties — attributes prized by both professional and DIY channels. Third, formulation improvements and hybridization are extending performance envelopes into transportation and specialty industrial applications.
Worldwide MS Polymer Market
At the same time, the market faces identifiable constraints. Feedstock and precursor price volatility — notably in polyurethane and silicone intermediates — introduces margin pressure and intermittency risk. Supply-side concentration among ingredient producers and regional logistics complexity can amplify disruptions. Our report quantifies the sensitivity of manufacturer margins to raw-material price swings and models inventory and hedging strategies that materially reduce downside exposure.
Competitive landscape — who matters and why
The MS polymer value chain features a mix of originators, integrated specialty chemical players, and formulation-focused suppliers. Market concentration is meaningful but not insurmountable: the top three global players account for roughly 38.5% of the market, while the top five control around 52.4%. This structure creates both incumbent advantages and opportunity windows for differentiated entrants.
- Kaneka Corporation — Originator of a differentiated MS Polymer technology, with an integrated footprint spanning production sites across Asia, Europe, and North America. Kaneka remains a reference supplier for high-performance STPE resins, and its capacity expansions in Europe have tightened regional supply dynamics.
- Sika AG — A major global systems supplier with deep channel presence in construction and infrastructure. Sika’s targeted capacity increases reflect a strategy to lock in regional share amid elevated construction spending.
- Henkel — With consumer and professional brands that translate formulation capability into retail and B2B reach, Henkel’s regional formulation programs demonstrate the commercial value of localized product mixes.
- Bostik (Arkema), Wacker, H.B. Fuller, 3M, Dow, Evonik and other specialty chemical firms — These players compete through differentiated hybrid formulations, channel breadth, and integrated adhesive portfolios. Their strategic moves — from product launches to capacity investments — are often calibrated to adjacent product synergies and end-market exposures.
- Smaller innovators — New entrants and start-ups focused on advanced silyl chemistries and American-made supply chains are beginning to reconfigure competitive dynamics, especially in specialty transportation and marine niches.
For 2026 decision-makers, the consequence is straightforward: incumbents can defend share through integrated scale and channel control, but well-capitalized challengers with targeted formulation advantages or supply-chain propositions can carve profitable niches. Our report maps these competitive vectors and prescribes prioritized defensive and offensive initiatives.
Recent developments that shift the 2026 horizon
- Large-scale capacity moves in Europe and Asia have reduced lead times in certain corridors, tightening spot volatility for formulators who lack long-term supply contracts.
- New product platform rollouts in 2026 have extended MS polymer applicability into composites, marine, and advanced transportation markets — expanding addressable demand beyond traditional construction and DIY segments.
- Mounting regulatory impetus toward low-VOC and solvent-free chemistries is accelerating specification changes in public procurement and commercial construction projects.
Strategic implications and recommended actions for 2026
Executives reading this report will be able to convert market projection into concrete 2026 actions. Key recommendations include:
- Prioritize upstream contracting: secure multi-year supply arrangements for critical precursors to stabilize COGS and protect margins during commodity cycles.
- Target capacity where specification drift meets logistics advantage: use our scenarios to identify geographic and product nodes where incremental capacity adds disproportionate commercial benefit.
- Invest selectively in hybrid formulation R&D: allocate a discreet portion of R&D spend to variant chemistries that reduce reliance on constrained precursors or unlock higher-value end markets.
- Pursue bolt-on M&A and strategic partnerships: focus on targets that provide formulation IP, channel access, or regional manufacturing footprints rather than standalone volumetric plays.
- Embed sustainability signals into commercial proposals: align product claims with low-VOC and indoor-air procurement standards to win public and high-spec private contracts.
Report methodology and the integrity of our projections
PW Consulting’s market model is built on a bottom-up synthesis of production capacities, historical trade and consumption patterns (2020–2025), proprietary surveys of formulators and OEM specifiers, and scenario-based adjustments for raw-material volatility and regulatory tightening. Revenue metrics are expressed in USD Million (base year 2025). We triangulate publicly reported capacity moves, company disclosures, and supply-chain interviews to ensure that our 2026–2032 forecast reflects both structural growth drivers and realistic operational constraints.
What we deliberately withhold — and why
In keeping with the “trailer” principle that guides this release, PW Consulting is showcasing the analytical depth and the actionable nature of the work while purposefully reserving granular segment tables and precise regional and application-level splits for the full report. Detailed sub-segment figures, regional breakdowns, and proprietary price curves are accessible exclusively in the paid report package and accompanying data workbook—this is where the model’s levers, assumptions, and cell-level forecasts are exposed for client-grade decision-making.
Who should read this report
- CEOs, CFOs, and strategy teams at integrated chemical manufacturers and formulators evaluating 2026 capital allocation decisions.
- Business development and M&A professionals seeking high-conviction targets and partnership archetypes in adhesives and sealants.
- Procurement and supply-chain leaders needing hedging and sourcing frameworks tailored to MS polymer precursors.
- Product managers and R&D executives plotting formulation roadmaps to meet tightening VOC and indoor-air quality standards.
Final note — how PW Consulting accelerates your 2026 outcomes
As the MS polymer market matures, the window to convert market growth into lasting advantage narrows. PW Consulting’s Worldwide MS Polymer Market report provides not only a validated market projection — including a clear 2025 baseline and a 7.0% CAGR through 2032 — but also the tactical playbooks necessary to act on that projection in 2026. For teams that must convert vision into executable plans this year, the report functions as both radar and roadmap: exposing risks early, highlighting levers for profitable growth, and prescribing the immediate moves that create optionality for 2027–2032.
To access the full dataset, granular segment tables, and the complete set of scenario spreadsheets that underpin our recommendations, please refer to the full Worldwide MS Polymer Market report available through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide MS Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com