

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aftercooler Market to Rise from USD 2,260 Million in 2025 to USD 3,353.6 Million by 2032 at 5.82% CAGR — Air‑Cooled Segment and Asia‑Pacific Lead

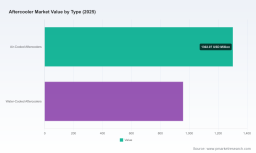
Worldwide Aftercooler Market: Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest Worldwide Aftercooler Market report (base year 2025, forecast 2026–2032) crystallizes the near‑term trajectory for an essential yet often overlooked component of compressed air systems. With the global aftercooler market estimated at approximately USD 2.26 billion in 2025 and projected to expand at a compound annual growth rate of 5.82% through 2032 (reaching a multi‑billion dollar market by the end of the forecast horizon), this sector offers meaningful strategic levers for OEMs, system integrators, end users, and investors planning capital allocation and go‑to‑market moves in 2026.
Worldwide Aftercooler Market
Why this report matters now
-
Energy and quality imperatives are converging. International standards such as ISO 8573‑1 (compressed air quality classes) and ISO 11011 (energy efficiency assessments for compressed air systems) increasingly position aftercoolers not just as accessory equipment but as primary contributors to compliance and system efficiency.
Worldwide Aftercooler Market -
Immediate downstream impact. Aftercoolers typically remove the large majority of condensate formed at the compressor outlet, materially protecting downstream dryers, filters and process equipment. This immediate improvement in air quality has direct implications for uptime, maintenance schedules and overall lifecycle cost.
Worldwide Aftercooler Market -
Financial planning for 2026 must account for material and supply‑chain volatility. Aluminium—long a preferred core material for plate‑fin aftercoolers due to its heat‑transfer characteristics and weight advantages—remains central to product cost and availability; recent market developments have driven elevated price sensitivity across manufacturer and buyer P&Ls.
-
Market scale and momentum are actionable. The 2025 market base and our 5.82% CAGR projection provide a reliable envelope for sizing opportunities, prioritizing product investments, and stress‑testing procurement strategies across short‑ and mid‑cycle scenarios.
What the report delivers — practical, transaction‑ready insight
-
Robust market sizing and seven‑year forecast (2026–2032) with transparent methodology and sensitivity bands to support conservative and aggressive planning assumptions.
-
Demand‑side segmentation (by product form factor, application clusters and buyer archetypes) with buyer economics and replacement/refurbishment cycles to inform product roadmaps and aftermarket strategies.
-
Supply‑side analysis covering manufacturing footprints, core materials and sub‑tier exposures. Special emphasis is given to plate‑fin core technologies, laser‑welded assemblies and aluminium alloy choices that influence weight, thermal performance and corrosion resistance.
-
Competitive benchmarking and vendor scorecards for established OEMs and niche specialists—covering product breadth, channel models, margin profiles, and recent M&A and partnership activity—designed for quick executive comparison.
-
Commercial tools: procurement hedging playbook, raw‑material pass‑through modelling, and a capex ROI calculator that links aftercooler selection to compressor system energy and maintenance savings.
-
Scenario analyses that stress test outcomes under alternative aluminium price paths, regulatory tightening on energy use, and accelerated adoption of integrated compressed‑air solutions.
Competitive landscape — pragmatic implications for 2026 strategy
The aftercooler market is populated by a mix of integrated compressor OEMs and focused thermal‑management specialists. Our report profiles the full spectrum—established global players (for example those headquartered in Sweden, the United States, Germany, Japan and other industrial hubs) and dedicated niche suppliers that serve mobile, blasting, and industry‑specific applications. Key insights for strategists:
-
Integrated OEM advantage: Large compressor manufacturers that bundle aftercoolers into system sales retain strong control over channel economics and aftermarket capture. Integration allows these players to frame value around system efficiency, guarantee compressed air quality, and protect service revenue.
-
Niche specialists and modular players: Companies focused on stand‑alone aftercoolers, mobile units, and high‑performance core designs compete through customization, rapid lead times, and aftermarket compatibility. These vendors can be attractive targets for OEMs seeking bolt‑on capability or for private equity looking to consolidate a fragmented category.
-
Moderate concentration, meaningful opportunity: The market concentration metrics show that a handful of firms account for a meaningful, but not overwhelming, portion of market value—indicating room for consolidation, regional champions, and targeted technology plays. For 2026, acquirers and strategic partners should prioritize capability adjacencies (water‑cooled vs. air‑cooled, mobile vs. stationary) rather than pure revenue scale.
-
Material and design differentiation: Product competitiveness will increasingly hinge on core technologies—plate‑fin heat exchangers, laser‑welded cores that reduce material use while maintaining pressure integrity, and corrosion‑resistant alloys. Firms that can combine thermal performance with lower total cost‑of‑ownership will win specification battles in capital procurement cycles.
Operational playbook — six actions PW Consulting recommends for 2026
-
Embed aftercooler selection into system ROI assessments. Treat aftercoolers as levers for energy and maintenance savings rather than commodity line items—link selection to ISO 11011 energy audits when evaluating capex projects.
-
Hedge raw‑material exposure. Establish dual‑sourcing and alloy alternatives, and renegotiate contract language to include price adjustment clauses tied to clear indices. Prioritize designs that reduce material input while preserving thermal performance (e.g., improved core geometry, laser welding).
-
Prioritize retrofit and aftermarket opportunities. Many installed bases lack optimized aftercooling; retrofit kits and service contracts can deliver rapid margin capture and customer lock‑in.
-
Recalibrate channel and warranty models. OEMs that bundle aftercoolers should align warranty liabilities with service networks to limit exposure and maximize lifecycle revenue.
-
Use competitive scorecards for deal screening. When evaluating potential targets or suppliers, weigh technology portability, manufacturing footprint, and compatibility with major compressor platforms higher than headline revenue.
-
Prepare for regulatory tightening. Integrate compressed‑air quality and energy‑efficiency requirements into product roadmaps and customer education programs; early movers will benefit as buyers seek compliant, auditable solutions.
Risks, scenarios and what to watch in 2026
-
Raw‑material volatility: Aluminium remains the dominant material for aftercooler cores; material price spikes or supply constraints will compress margins for manufacturers without hedges or design alternatives.
-
Technology substitution: Advances in drying technologies or new heat‑exchanger materials could alter product portfolios. Monitor patent activity and pilot deployments around alternative alloys and manufacturing techniques.
-
Regulatory shifts: Stricter energy and emissions reporting could accelerate replacement cycles for inefficient systems—creating upside for vendors with energy‑optimised solutions but raising retrofit financing needs for end users.
-
Channel disruption: Consolidation among distributors or the rise of e‑procurement platforms could compress transaction margins and accelerate price transparency.
How PW Consulting’s report supports decision‑making in 2026
For executives planning capital investments, supplier negotiations, or M&A activity in 2026, this report translates market scale and dynamics into executable plans. Our modelling links the 2025 market base and the 5.82% CAGR projection to tariff, commodity and energy scenarios—giving boards and business unit leaders an evidence‑based foundation for setting budgets, prioritizing R&D, and structuring commercial arrangements.
We intentionally present a strategic preview here: the full report contains the granular segmentation tables, regional and application breakouts, vendor financial proxies, and downloadable decision tools that procurement teams, product managers and corporate development professionals will use to act this year. To access the complete datasets, vendor scorecards, and the executable playbook for 2026, visit the PW Consulting Worldwide Aftercooler Market report page or request an executive briefing with our senior analyst team.
For detailed analysis of this topic, please visit the official page: Worldwide Aftercooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com