

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Network Telemetry Market to Explode from USD 1.05B in 2025 to USD 6.06B by 2032 — 28.45% CAGR

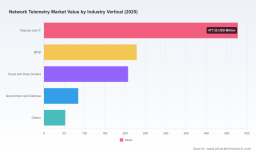
Worldwide Network Telemetry Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises and service providers accelerate digital transformation, network telemetry has moved from a niche operational tool to a strategic capability. PW Consulting’s latest market research — the Worldwide Network Telemetry Market report (base year 2025, forecast 2026–2032) — synthesizes five years of historical data and presents an action-oriented roadmap for 2026 decisions. This preview highlights the report’s strategic value, major market dynamics, vendor positioning, and the practical guidance executives need to align investments with intent-driven networking, observability, and AI-driven operations.
Worldwide Network Telemetry Market
Why network telemetry matters for 2026 strategy
-
Telemetry is the data fabric that enables AI/ML-driven network operations. Modern observability pipelines turn high-frequency state and flow information into predictive insights for assurance, anomaly detection, and automated remediation. For 2026, telemetry strategy is equivalent to a platform strategy: it determines which analytics, security, and automation capabilities an organization can unlock.
Worldwide Network Telemetry Market -
Economic and operational constraints are changing investment priorities. With sustained capital discipline across industries, telemetry programs must demonstrate measurable ROI in the first 12–24 months through reduced incident MTTR, network capacity optimization, and automation-driven operational efficiency.
Worldwide Network Telemetry Market -
Regulation and standards are narrowing viable design choices. From data minimization requirements in the EU to protocol standardization efforts, enterprises must architect observability pipelines that are privacy-compliant, interoperable, and resilient to supply-chain constraints.
Market trajectory in one look
Between 2020 and 2025 the network telemetry market experienced rapid expansion: the report documents a multi-year climb from early adoption to broad commercial deployment. The market size crossed the billion-dollar milestone in our 2025 base year and is forecast to continue expanding quickly in 2026 and beyond. PW Consulting projects a compound annual growth rate (CAGR) of 28.45% over the 2026–2032 forecast horizon, reflecting accelerating demand for streaming telemetry architectures, in-band network telemetry, and analytics platforms. By 2032 the market trajectory points to several-fold growth relative to the early-2020s baseline, driven by cloud-scale observability and the operationalization of network telemetry into security, capacity planning, and SRE workflows.
Note: this preview intentionally omits granular regional and segment breakdowns — the full report provides the detailed segmentation and financials required for budgeting and vendor shortlists.
Report deliverables: what you get from PW Consulting
-
Executive summary and investment thesis: Clear articulation of the market opportunity, risk factors, and strategic playbooks for technology and procurement leaders.
-
Market sizing and forecast model (2020–2032): Transparent methodology, scenario analyses (base, accelerated, constrained), and sensitivity tables for unit-cost, bandwidth, and energy assumptions.
-
Operational playbooks: Deployment checklists for cloud, edge, and on-premises telemetry pipelines; data retention and minimization templates aligned to privacy rules; and integration patterns for SIEM, AIOps, and observability stacks.
-
Vendor scorecards and go-to-market maps: Comparative assessments across product capabilities, ecosystem integrations, professional services, and partner channels — enabling fast shortlists for RFPs.
-
Financial impact tools: TCO/ROI calculators, energy-and-capacity cost models, and phased investment roadmaps designed for CIO/CFO alignment.
-
Case studies and reference architectures: Real-world examples of telemetry-driven automation and incident reduction across cloud providers, telcos, and large enterprise networks.
Competitive landscape — who leads, who follows, and what to watch
The market is commercially competitive but concentrated: a limited set of incumbent network vendors and cloud-native analytics providers command significant influence over standards, telemetry protocols, and platform integrations. Our competitive analysis focuses on capability vectors that matter for 2026: protocol support (gNMI/gNOI, gRPC, IPFIX), silicon and NOS telemetry integration, cloud-native ingestion, and security/processing pipelines.
-
Cisco Systems (San Jose, CA, USA) — Continues to be a major market force with Model-Driven Telemetry (MDT) implementations across IOS XR, NX-OS, and Catalyst platforms. Cisco’s recent software updates have improved gRPC performance and support for AI-driven analytics, positioning it as a default choice for large enterprises seeking end-to-end vendor continuity. Cisco’s ecosystem strength and wide field footprint make it central to many migration roadmaps.
-
Juniper Networks (Sunnyvale, CA, USA) — Juniper’s Junos Telemetry Interface (JTI) and recent addition of gNOI support broaden its streaming and configuration telemetry capabilities. Juniper is favored in environments requiring high-frequency operational state streaming with a strong affinity in service provider and cloud edge deployments.
-
Arista Networks (Santa Clara, CA, USA) — With EOS eAPI, gNMI telemetry, and CloudVision, Arista targets cloud-scale data centers where programmability and developer tooling (e.g., AVA) matter. Expect Arista to lead in use cases that prioritize telemetry extensibility and low-latency pipeline integration.
-
Nokia (Espoo, Finland) and Broadcom (San Jose, CA, USA) — Nokia’s SR OS telemetry and Broadcom’s ASIC-level telemetry export capabilities are influential for carrier and hyperscaler architectures where hardware-level visibility matters.
-
Huawei (Shenzhen, China) — Continues to integrate native telemetry across router families and management stacks. Geopolitical restrictions, however, shape where Huawei hardware and telemetry tooling can be deployed.
-
Extreme Networks , Palo Alto Networks , F5 Networks , and cloud-native analytics providers like Kentik — Represent complementary capabilities: from fabric-wide telemetry and security-centric streaming to application-delivery telemetry and cloud-native ingestion/analytics.
Recent vendor developments underscore the pace of innovation: Cisco’s IOS XR telemetry enhancements, Juniper’s gNOI support, and Arista’s AVA tooling all reflect an industry push toward standardized, high-frequency streaming combined with developer-friendly customization.
Regulatory, standards, and geopolitical dynamics shaping 2026 decisions
-
Standards: IETF’s formalization of gNMI and related model-driven telemetry standards has reduced interoperability friction. Enterprises should prioritize vendor support for these standards to avoid vendor lock-in at the data model layer.
-
Privacy and data minimization: GDPR Article 25 and similar privacy frameworks require instrumentation to be designed with minimization and purpose limitation in mind. Telemetry collectors and pipelines must support selective sampling, field redaction, and retention controls as first-class features.
-
Regulatory access and neutrality: Recent regulatory actions around network neutrality and permissible traffic handling affect how ISPs and telcos expose telemetry. Organizations relying on transit-level telemetry should validate contractual commitments and platform neutrality clauses.
-
Geopolitics and supply chain: Export controls and entity-list restrictions impact platform selection for certain regions and use cases. Procurement teams must incorporate compliance reviews and alternate sourcing plans into 2026 purchasing cycles.
-
Operational costs: Energy and data center processing costs are non-trivial; telemetry strategy must balance sampling frequency, edge pre-aggregation, and cloud ingestion economics to stay within acceptable TCO boundaries.
Practical recommendations for enterprise leaders — a 2026 checklist
-
Define telemetry as a platform investment, not a point product. Commit to an open, standards-based data model to maximize reuse across security, SRE, and business analytics teams.
-
Prioritize streaming telemetry for real-time automation, but assess hybrid approaches where in-band telemetry and sampled flow data can reduce processing costs. Use staged rollouts with measurable KPIs (MTTR reduction, automation coverage, cost per event).
-
Embed privacy and compliance controls into ingestion and storage. Require vendors to demonstrate support for field-level redaction, retention policies, and data minimization by design.
-
Negotiate procurement terms that include protocol and data portability guarantees. Given the market’s moderate concentration, ensure exit and interoperability clauses to avoid strategic lock-in.
-
Invest in edge pre-processing and adaptive sampling to manage energy and compute costs, particularly for distributed and IoT-heavy deployments.
-
Use the PW Consulting vendor scorecards and TCO models to run three-year investment scenarios and validate budgetary allocations with the CFO and SRE leads before procurement.
How the full PW Consulting report helps you act
This preview highlights the strategic contours of the network telemetry market for 2026. The full Worldwide Network Telemetry Market report provides the operational details organizations need to act confidently: granular scenario-based financials, vendor-by-capability matrices, validated deployment reference architectures, and a step-by-step migration playbook from SNMP/flow-based approaches to streaming-first observability. For teams that must deliver measurable operational improvements in the coming 12 months, the report reduces decision friction by combining market economics, technical due diligence, and procurement-ready templates.
Conclusion — positioning for advantage in 2026
Network telemetry is no longer an optional visibility tool; it is the substrate for secure, resilient, and automated digital infrastructure. With market expansion accelerating and standards converging, 2026 will reward organizations that treat telemetry as a strategic platform: selecting standards-aligned vendors, embedding privacy and cost controls, and operationalizing telemetry data into closed-loop automation. PW Consulting’s report equips leaders with the market intelligence and executable playbooks necessary to turn telemetry investments into measurable business outcomes.
To access the full dataset, vendor comparisons, and deployment playbooks that underpin these strategic recommendations, please refer to the PW Consulting report landing page for the complete Worldwide Network Telemetry Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Network Telemetry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com