

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Biometric Signature Pads Market Set for 7.15% CAGR in 2026–2032
By pmarketresearch, 2026-07-15
Biometric Signature Pads Market: Strategic Imperatives for 2026
PW Consulting’s latest market research on Biometric Signature Pads synthesizes five years of historical performance and a seven-year outlook to 2032, delivering a pragmatic, decision-ready roadmap for executives planning investments, procurement, or M&A in 2026. Our analysis combines market-size modeling, regulatory impact assessment, competitive benchmarking, and actionable playbooks — all designed to accelerate confidence while reserving detailed sub-segment matrices for the full report.
Biometric Signature Pads Market
Market snapshot: steady expansion, structural opportunity
The biometric signature pads market has shown steady expansion through the first half of the decade. Our base-year assessment (2025) places the global market at USD 480.0 million, up from USD 345.5 million in 2020, reflecting continued adoption in regulated and high-trust environments. Looking forward, we model the market growing at a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast period, reaching an estimated USD 778.3 million by 2032.
Biometric Signature Pads Market
Two structural features underpin the opportunity for 2026 decision-makers: (1) a modest-to-moderate market concentration among a handful of established hardware and solution vendors (our concentration analysis indicates the top three players account for a significant but not dominant share, with the top five increasing that share meaningfully), and (2) a persistent legal and compliance tailwind from e-signature frameworks that recognize biometric, dynamic data when implemented to applicable standards.
Biometric Signature Pads Market
Why this matters for 2026 strategy
- Revenue predictability and budgeting: A clear CAGR and model-driven forecast mean procurement and budget planners can move from pilot-phase conservatism to phased rollouts tied to measurable adoption curves.
- Regulatory certainty as a growth driver: Jurisdictions that embrace biometric graphometric evidence and device-level assurances are accelerating procurement in public sector, finance, and regulated corporate contexts.
- Competitive maneuverability: The market concentration profile leaves room for niche entrants, differentiation via security/certification, and strategic consolidation — all viable 2026 plays.
Key dynamics shaping the market
- Regulatory harmonization and legal recognition: The EU eIDAS framework and corresponding international standards (including ISO/IEC biometric protocols) continue to shape procurement specifications. Devices that can demonstrate compliance with qualified signature creation device requirements gain outsized procurement preference in public and regulated procurements.
- Security and trust as product differentiators: Buyers increasingly evaluate pads for multi-layered assurance — cryptographic key management, tamper-evident hardware, secure boot, and device-level attestation. Certifications and documented procedures now play a central role in contract awards.
- Functional convergence: Hardware vendors are converging on hybrid feature sets — color LCDs, pressure/velocity capture, fingerprint integration, NFC, and multi-touch — but differentiation remains via software ecosystems and integration toolkits that reduce deployment friction.
- Supply-chain pressures: Tariffs on electronics and component supply variability continue to affect bill-of-material costs and lead times. Buyers should expect cyclical price and availability swings driven by trade policy changes and logistics constraints.
Competitive landscape: profiles and tactical posture
Our report profiles the leading device and solution providers, assessing product roadmaps, channel strategies, integration capabilities, and target verticals. A selection of incumbent profiles:
- Topaz Systems (Simi Valley, CA): Broad product range spanning LCD and fingerprint-integrated pads; strengths in verticalized solutions for healthcare, legal, and financial services and a rich developer ecosystem.
- Scriptel Corporation (Columbus, OH): Focus on durable, high-throughput pen-based devices with deep integrations into healthcare workflows and point-of-sale environments.
- Wacom Co., Ltd. (Japan): Leverages decades of stylus and pressure-sensing expertise; positions its STU series around dynamic biometric capture and verification for high-assurance use cases.
- ePadLink (Interlink Electronics) (USA): Combines hardware with IntegriSign software to deliver legally robust e-signature workflows across enterprise stacks.
- StepOver GmbH (Germany): Focused on high-security, eIDAS-compliant devices; notable recent activity includes the December 2025 launch of a new rugged color-display model optimized for continuous, high-duty environments.
- Euronovate Group (Switzerland/Italy) and Signotec GmbH (Germany): Both emphasize European compliance (e.g., eIDAS), high-end security, and features for in-presence signing events.
Taken together, this set of vendors demonstrates two proven routes to market: scale through broad OEM/ISV partnerships and vertical specialization emphasizing compliance and reliability. For 2026, winning strategies will combine both — modular hardware platforms paired with turnkey integrations for prioritized verticals.
Strategic playbook for 2026 decision-makers
Based on scenario modeling and client engagements, PW Consulting recommends six parallel tracks for organizations evaluating biometric signature pad investments in 2026:
- Procurement optimization: Adopt a phased procurement tied to use-case prioritization. Begin with controlled pilots in high-compliance or high-volume points, instrument KPIs (throughput, error rates, user satisfaction), then scale modularly to reduce upfront capital outlay.
- Vendor selection criteria: Prioritize suppliers that demonstrate end-to-end compliance documentation, robust SDKs, and transparent security practices. Shortlist vendors that balance device resiliency with integration speed (i.e., reduced time-to-production).
- Product and R&D focus: For vendors and OEMs, the highest-return investments are in secure element integration, certified cryptographic stacks, and SDKs that lower integration cost for major enterprise platforms (EMR, core banking, ERP).
- Channel and partnership models: ISVs and system integrators that bundle software, certification assistance, and managed deployment services will command pricing power. For platform vendors, pursue OEM partnerships to embed signature capture into POS and kiosk ecosystems.
- Risk & compliance management: Implement device attestation and lifecycle controls; incorporate legal counsel during procurement to ensure firmware update policies and custody of cryptographic keys align with future-proofed signature validity.
- M&A and consolidation signals: Mid-market vendors with certified product stacks and verticalized client lists are logical tuck-in acquisitions for ISVs seeking to offer turnkey signing solutions — 2026 is likely to see opportunistic consolidation driven by buyers seeking to shortcut integration risk.
What the full PW Consulting report delivers
This briefing is a strategic preview. The complete PW Consulting Biometric Signature Pads Market report provides the operational detail that procurement teams, product leaders, and corporate development groups will use to execute in 2026, including:
- Our full market model (historical 2020–2025; forecast 2026–2032) with sensitivity scenarios and explicit assumptions.
- Comprehensive vendor dossiers with strengths/weaknesses, go-to-market routes, and integration readiness matrices.
- Regulatory impact analysis and a compliance checklist mapped to device-level features and certification pathways.
- A buyer’s implementation playbook: procurement RFIs/RFP templates, KPI frameworks, and testing protocols for legal admissibility and operational resilience.
- Strategic M&A screening criteria, including signals for attractive tuck-ins and a shortlist of targets whose capabilities accelerate time-to-market.
To preserve the value of our segmentation and to drive verifiable vendor selection, the report reserves detailed sub-segment tables and region-level revenue splits for the full document; these granular datasets are essential for transaction diligence and are available through the report portal.
Immediate actions for leaders
- CEOs & CFOs: Align capital planning to a phased rollout approach and reserve contingency for tariff-driven cost variability.
- CIOs & Heads of Procurement: Shortlist vendors based on documented compliance artifacts and demand vendor-led integration pilots with production data capture.
- Product & R&D Heads at vendors: Prioritize certified security modules and developer-friendly SDKs; document compliance for qualified signature creation to increase procurement appeal in regulated markets.
- Corporate Development: Evaluate tuck-in targets that offer certification, vertical footholds, or proprietary biometric processing algorithms — these assets materially shorten sales cycles.
PW Consulting’s analysis makes one conclusion clear: with a predictable growth trajectory and legal frameworks that increasingly favor certified biometric capture, 2026 will be a year when leaders can move from pilot curiosity to disciplined deployment — provided they pair vendor due diligence with robust compliance and supply-chain strategies. For executives ready to act, our full report supplies the data, templates, and vendor intelligence to convert opportunity into measurable outcomes.
Access the full PW Consulting Biometric Signature Pads Market report for the definitive datasets, vendor rankings, and executable playbooks to inform your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Biometric Signature Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Fuel Level Sensor Market at USD 950.0 Million in 2025, Poised to Reach USD 1,184.35 Million by 2032 on a 3.2% CAGR — Asia Pacific Leads with USD 413.08 Million
By pmarketresearch, 2026-07-15
Worldwide Automotive Fuel Level Sensor Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As OEMs rewire powertrain strategies and suppliers recalibrate technology roadmaps, reliable intelligence on the automotive fuel level sensor market is becoming a strategic necessity. PW Consulting’s forthcoming Worldwide Automotive Fuel Level Sensor Market report — anchored on a 2025 base year and a 2026–2032 forecast horizon — distills the commercial, technological, and regulatory inflection points that will govern supplier selection, R&D prioritization, and M&A activity in 2026.
Worldwide Automotive Fuel Level Sensor Market
Why this market matters for 2026 decision-makers
-
Stable but evolving demand: The global market has demonstrated steady recovery and incremental growth in the early 2020s, with PW Consulting estimating the market at approximately USD 950 Million in 2025. Our forecast models indicate a compound annual growth rate (CAGR) of 3.2% over 2026–2032, reflecting a market that is neither hyper-growth nor stagnant — rather, one undergoing structural transformation.
Worldwide Automotive Fuel Level Sensor Market -
Concentration and competitive tension: Market concentration metrics show that the sector remains led by a handful of global players. This concentrated structure creates both barriers and levers for challengers: scale delivers OEM access and integration, while targeted innovation opens pockets of opportunity for focused specialists.
Worldwide Automotive Fuel Level Sensor Market -
Strategic intersection with powertrain transition: Although electrification reduces raw demand for fuel-system components over time, fuel level sensing remains mission-critical for internal combustion engine (ICE), hybrid, and certain multi-fuel applications during the transition. Suppliers and OEMs must balance short-term revenue with long-term repositioning.
Report snapshot — what PW Consulting delivers
This report is designed as a practitioner’s playbook for 2026. Highlights include:
-
Macro trajectory and scenario analysis: Base-case and downside scenarios incorporating EV penetration rates, fuel system lifecycle dynamics, and macroeconomic scenarios to stress-test revenue and margin outcomes through 2032.
-
Supplier matrix and OEM sourcing map: A validated supplier-OEM linkage framework that ranks vendors by technical fit, program wins, geographic strength, and integration capability (note: detailed program-level tables and value-by-segment are reserved for the full report).
-
Technology roadmap and cost curves: Comparative assessment of capacitive, ultrasonic, resistive (including Hall and reed-switch alternatives), and pressure-based solutions — focusing on accuracy, manufacturability, calibration complexity, and anticipated BOM evolution.
-
Regulatory & safety impact analysis: Quantification of near-term compliance requirements and the expected engineering lift associated with emerging standards and crashworthiness mandates, with guidance on testing protocols and certification timelines.
-
Supply chain risk & resilience diagnostics: Practical mitigation options for semiconductor lead-time volatility, raw-material exposure, and tiered-sourcing trade-offs — complete with a supplier continuity scoring tool that can be deployed in procurement reviews.
-
Commercial playbook: Prioritized action items across product, go-to-market, M&A, and alliance strategies for OEMs, Tier-1 suppliers, and focused component specialists.
Competitive landscape — who matters and why
The market’s competitive topology is a mix of global integrated suppliers, Tier-1 system houses, specialized sensor manufacturers, and cross-domain electronics players. Key players profiled in the report include Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner, Visteon, Sensata Technologies, CTS Corporation, TE Connectivity, Gill Sensors & Controls, and Methode Electronics. PW Consulting’s assessment focuses on three vectors: product breadth and depth, OEM program access, and strategic intent.
-
Robert Bosch GmbH — Bosch continues to leverage its fuel system integration capability, offering capacitive and ultrasonic options embedded in OEM fuel modules. Their strength lies in system-level integration and longstanding OEM relationships.
-
Continental AG — Continental’s recent supplier nominations underline its competitiveness in platform-level programs. Expect them to press on integration of temperature sensing and diagnostics linked to vehicle ECUs.
-
Denso Corporation — Denso’s collaborations with regional OEMs and its JDA activity in capacitive sensing for hybrid models position it strongly in Asia Pacific programs and cross-platform adaptations.
-
BorgWarner & Visteon — Both firms emphasize multi-fuel compatibility and cockpit-integrated sensing respectively, creating differentiated routes to OEM value capture.
-
Sensata, CTS, TE Connectivity, Gill, Methode — These focused specialists provide technological depth (pressure-based, variable resistor, ultrasonic, Hall-effect, ruggedized modules) that enables targeted wins in heavy-duty, off-road, and performance segments.
Recent industry moves underscore the market dynamics: product launches that expand sensing envelopes; supplier nominations that lock in platform-level exposure; and validation programs that shift credibility curves. PW Consulting maps these events to program timelines to show where near-term revenue and future optionality will accrue.
Segment dynamics and technological tensions
Three structural tensions define supplier choices in 2026:
-
Accuracy vs. robustness: Capacitive and advanced non-contact solutions offer improved accuracy in modern plastic tanks, but they demand more sophisticated calibration and software compensation. Ultrasonic alternatives can be attractive for non-intrusive measurement but face field calibration challenges in foaming or turbulent fuel conditions.
-
Componentization vs. system integration: OEMs increasingly prefer integrated fuel modules that reduce assembly complexity, favoring suppliers with module-level capability. Conversely, focused sensor specialists can out-innovate on sensing performance and supply niche applications.
-
Supply-side fragility: Semiconductor supply constraints have materially extended lead times for sensor ICs and microcontrollers in recent years, driving inventory and qualification strategies that materially affect time-to-production for new programs.
Regulation and safety — immediate and medium-term impacts
Regulatory updates are accelerating engineering requirements. New emission and safety standards demand tighter fuel management and robust sensor performance to support combustion optimization, on-board diagnostics, and crashworthiness. Compliance timelines are compressing program development windows; teams that align sensor development with regulatory verification early in 2026 will avoid late-stage rework and cost overruns.
Strategic playbook for 2026
For executives building plans in 2026, PW Consulting recommends a three-track strategy:
-
Defend core revenue while funding pivot initiatives: Protect ICE and hybrid sales through improved cost-to-serve and reliability programs, while allocating a portion of R&D to sensing capabilities that are transferable to broader vehicle sensing and fluid-property detection markets.
-
Supply-chain hardening and supplier diversification: Implement a tiered sourcing model for critical ICs and validate alternate sensor chemistries or suppliers. Use our supplier continuity scoring tool (included in the full report) to prioritize dual-sourcing where program risk is highest.
-
Selective inorganic and partnership plays: Target bolt-on acquisitions that close capability gaps (e.g., non-contact sensing IP, software-based compensation, fluid-property analytics) and pursue strategic JDAs with OEMs to secure platform access early in development cycles.
Use-cases and buyer guidance
The report provides tailored guidance for three archetypal buyers:
-
OEMs: Use the report to validate supplier roadmaps against platform lifecycles, calibrate DFM/DFT requirements, and quantify trade-offs between module-level integration and component supplier flexibility.
-
Tier-1 suppliers: Identify white-space where sensor specialization can be leveraged into module supply, and use our margin-sensitivity analyses to negotiate program economics.
-
Investors and M&A teams: Deploy our scenario valuations and supplier scorecards to prioritize targets that offer cross-market IP or defensible OEM relationships.
FAQ — concise answers to the pressing operational questions
-
How material is electrification to fuel level sensor demand? Electrification reduces some volume categories, but a transition tail and diversified fuel-system applications mean demand persists for several product cycles. Planning should assume gradual attrition rather than abrupt obsolescence.
-
What are the immediate supply risks to address in 2026? Semiconductor lead-time volatility and qualification timelines remain the primary constraints. Early engagement with IC suppliers and validation of alternate silicon footprints are practical mitigations.
-
Do safety and emission regulations change technical requirements? Yes — recent standards increase the precision and resilience required of level sensing and diagnostics, and crashworthiness mandates require integrated validation workflows during module design.
How to access the full intelligence
This article is a preview of PW Consulting’s full Worldwide Automotive Fuel Level Sensor Market report. The comprehensive study contains the granular segmentation, supplier-program matrices, pricing and margin benchmarks, and downloadable tools (sensitivity model, supplier continuity scorecard, and program-timing gantt charts) that executives and procurement teams need to operationalize a 2026 plan.
To obtain the full report and supporting datasets, please visit PW Consulting’s report page or contact our industry team for a briefing. The data-driven intelligence we provide is tailored to convert uncertainty into a prioritized set of actions — enabling leaders to make decisive, defensible moves as the automotive ecosystem continues to evolve.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Fuel Level Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Conductive Fibers Market to Reach USD 2,073.81 Million by 2032, Expanding at a 7.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Conductive Fibers Market — Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s new market study on Worldwide Conductive Fibers provides an operationally focused intelligence package to guide C-suite and product leaders as they make strategic decisions in 2026. The conductive fibers market has evolved from a niche specialty material into a foundation for wearables, industrial safety, and EMI management — and it is entering a phase of steady, investment-grade growth. After tracking the market through a 2020–2025 historical window, our base-year 2025 estimate places the global industry at roughly USD 1.25 billion. Under the scenarios modelled in the report, the market expands at a compound annual growth rate (CAGR) of approximately 7.5% across a 2026–2032 forecast horizon, moving toward a low‑single‑billion market by 2032.
Worldwide Conductive Fibers Market
Why this briefing matters for 2026 strategy
- Capital allocation: Investors and procurement leaders must decide where to tilt capex and inventory bets in materials and downstream integration (smart textiles, EMI shielding, and industrial PPE).
- Product roadmaps: R&D and product teams must prioritize durability, washability, and signal integrity — the three technical thresholds now determining adoption in consumer wearables and safety-critical industrial markets.
- M&A and partnerships: Fragmentation and pockets of technical specialization create near-term opportunities to consolidate capabilities horizontally (fiber supply, metallization) and vertically (textile integration, embedded electronics).
Market trajectory and macro signals
After a period of steady expansion between 2020 and 2025, the market is forecast to continue growing at c. 7.5% CAGR through 2032. This trajectory reflects simultaneous tailwinds: rising adoption of e-textiles and wearable sensors, increasing regulatory emphasis on EMI compatibility in electronics, and continued migration of traditional safety textiles toward conductive and dissipative functionality. Importantly, the market remains commercially attractive but not tightly concentrated — our measures of concentration indicate a market structure where the top three players control only a low‑twenty percent share and the top five remain well under forty percent. That competitive breadth favors differentiated product strategies and regional specialization rather than winner-takes-most consolidation at scale.
Worldwide Conductive Fibers Market
Dynamics shaping demand
- Wearables and e-textiles: Functionality requirements beyond mere conductivity — notably washability, stretch compatibility, and comfort — have moved to the top of product specification checklists. Buyers now evaluate conductive fibers on multi-attribute performance, not just resistivity.
- Industrial safety and anti‑static: End-users continue to prioritize durability and predictable electrostatic discharge characteristics for critical environments, which sustains a consistent baseline demand regardless of consumer cycles.
- EMI/EMC shielding: The increasing density of electronics across consumer and industrial equipment lifts demand for reliable shielding materials that can be integrated into assemblies rather than added as after‑thoughts.
- Regulatory and test regimes: Standards for electrical performance, washability, and durability are evolving — compliance risk and test failure rates are now a procurement concern that influences supplier selection and product design.
Supply side and raw‑material considerations
From a supply-chain perspective, conductive fibers sit at a crossroads of commodity metals, specialty metallization and advanced polymers. Silver‑coated fibers remain a technical gold standard for conductivity, but stainless‑steel and carbon-based solutions offer a compelling cost‑performance balance that is driving adoption in many textile contexts. Our analysis highlights the practical trade-offs procurement teams must weigh: total lifecycle cost (including longevity under laundering), mechanical compatibility with textile substrates, and the operational constraints of metallization and yarn production capacity. Vendors that can guarantee batch-to-batch consistency while providing independent lab‑tested compliance certificates command a premium in purchase negotiations.
Worldwide Conductive Fibers Market
Competitive landscape — who to watch
The market roster mixes large material innovators, technical textile specialists, and agile niche players. Key incumbents and their strategic postures are summarized below to illustrate where capability clusters and competitive threats are emerging.
- Toray Industries, Inc. (Tokyo): Strong in high‑performance materials and composite integration; well positioned for smart textile projects that require rigorous engineering and supply assurances.
- Teijin Limited (Tokyo): Focused on sustainable and medical-grade conductive fibers; expect strategic moves toward integration with wearable healthcare solutions.
- Bekaert (Zwevegem): Specialist in metal-based conductive yarns (stainless steel options) with durable EMI and data transmission applications; competitive where durability and mechanical robustness are primary purchase criteria.
- 3M Company (St. Paul): Broad materials portfolio and systems approach to EMI and ESD solutions; their strength lies in global reach and cross-sector selling into industrial OEMs.
- DuPont de Nemours (Wilmington): Integrated advanced-material offerings and an R&D focus on multifunctional textiles; important partner where conductive fibers are combined with other engineered polymer systems.
- Seiren Co., Ltd. (Fukui): Focused on functional textiles for automotive and apparel; a player to monitor for commercialization of textile-integrated systems.
- Shieldex / Statex (Bremen): Strong in silver-plated yarns and antimicrobial functionalization; relevant for clients prioritizing high conductivity plus ancillary functionality.
- Specialists and niche innovators: Companies such as Shakespeare Polymers & Filaments, Syscom Advanced Materials (Agsis), Eeonyx, Swift Textile Metalizing, Kolon, and emerging Chinese filament producers are advancing discrete technical niches — from carbon‑suffused polymers to knitted conductive fabrics to metallized filaments for aerospace.
Recent industry moves — including a 2026 product‑positioning statement from a major Chinese filament producer and the 2025 launch of a novel, high‑strength conductive yarn by an advanced materials start‑up — underline how vendors are differentiating on mechanical strength, density, and resistivity simultaneously. Executives should track these product announcements as signals of where performance thresholds are shifting.
What the PW Consulting report delivers (operational, not academic)
Designed for executives and procurement teams who must act quickly, the full report provides:
- Actionable supplier scorecards that benchmark technical performance, compliance testing, capacity, and cost-to-serve (including logistics and lead‑time risk).
- Integration playbooks for embedding conductive fibers into product assemblies (smart garments, layered EMI shields, and industrial textiles), with specification checklists and test protocols.
- Supply‑chain stress tests and scenario plans covering raw-material shocks (e.g., precious-metals pricing), regional capacity constraints, and certification lead times.
- M&A and partnership mapping that identifies acquisition targets and complementary technology partners by capability cluster (metallization, polymeric conductivity, textile integration).
- IP landscaping and regulatory watchpoints — a practical guide to certification regimes and common non‑compliance pitfalls that slow commercialization.
- Scenario-based financial modelling templates and premium/commodity pricing frameworks to support procurement negotiations and new product business cases.
To respect the “trailer” approach, this briefing purposefully omits the granular regional and application splits, vendor revenue breakdowns and other sensitive line-item metrics that buyers rely on for transactional decisions. Those data-rich exhibits, along with downloadable scorecards and spreadsheet models, are included in the full research package.
Strategic recommendations for 2026
- Prioritize product qualification frameworks now: Projects initiated in 2026 that skip early-stage washability and mechanical endurance testing are at high risk of late-stage rework and cost overruns.
- Design procurement around multi‑attribute TCO: Evaluate conductive fibers on lifecycle metrics (laundry cycles, retention of conductivity, connectorization cost) not just unit price.
- Hedge raw-material exposure: Where silver-based solutions are attractive, secure mixed sourcing strategies and consider stainless‑steel or carbon-based fallbacks for scale deployments.
- Explore selective partnerships: OEMs and brand owners should consider co‑development agreements with specialized textile integrators to accelerate time-to-market for wearable and medical applications.
- Monitor certification timelines: Align product launches with anticipated updates to washability and electrical safety standards to avoid market access delays.
How to use this report
Executives should use the study as both a decision-support tool (supplier selection, capex trade-offs, and M&A screening) and an operational playbook (test protocols, integration checklists, and risk scenarios). The “data room” in the full package contains the confidential segmentation matrices, regional demand curves, vendor financials and modeled price envelopes that are essential for transaction-level decisions.
Next steps
For access to the complete Worldwide Conductive Fibers Market report, including the full dataset, supplier scorecards and downloadable scenario models, please consult the PW Consulting report page. Our advisory team is available for bespoke briefings, supplier due‑diligence exercises, and strategy workshops tailored to procurement, R&D and corporate development agendas for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Auto-Steering for Tractor Systems Market Set to Accelerate at a 12.48% CAGR, New Insights Report Finds
By pmarketresearch, 2026-07-15
Worldwide Auto Steering for Tractor System Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Auto Steering for Tractor Systems arrives at a pivotal moment for agricultural technology investors, OEMs, and farm operators. As capital allocation decisions for 2026 are being finalized, our study—grounded in five years of historical data and a seven-year forecast—provides actionable insight into the market dynamics that will shape product roadmaps, partnership strategies, and M&A activity. This press release is designed as a high-fidelity preview: deep enough to demonstrate our analytical rigor, but deliberately selective about granular segment numbers to encourage access to the full report for transaction-grade detail.
Worldwide Auto Steering for Tractor System Market
Why 2026 Is a Strategic Inflection Point
-
Market momentum: After sustained expansion in the early 2020s, the global auto-steering market for tractors crossed a major milestone in 2025. Our base-year analysis captures that trajectory and projects continued expansion into the 2030s, underpinned by productivity demands, precision agriculture adoption, and increased retrofit activity.
Worldwide Auto Steering for Tractor System Market -
High growth environment: The forecast period (2026–2032) reflects a robust compound annual growth rate of 12.48%, reflecting accelerating adoption across farm scales and geographies as GNSS accuracy, ISOBUS interoperability, and steer-by-wire technologies mature.
Worldwide Auto Steering for Tractor System Market -
Consolidation pressure: Market concentration metrics reveal a mid-to-high concentration profile among global leaders—enough to sustain incumbent advantage, yet open to specialist challengers and software-centric disruptors pursuing service monetization and fleet solutions.
What the Report Contains: Practical, Transaction-Ready Intelligence
Our report is constructed for operators and strategists who must make trade-offs in 2026. To support that, the study combines quantitative rigor with hands-on, consultative outputs:
-
Historical and forecast market modelling—covering a five-year historical window and a seven-year forecast horizon—facilitating scenario analysis for CAPEX and product investment planning.
-
Competitive landscaping with profiles of leading OEMs, precision agriculture specialists, and retrofit suppliers, including go-to-market assessments and capability matrices.
-
Technology deep dives on GNSS+IMU integration, RTK adoption curves, ISOBUS interoperability, hydraulic versus electric actuation trade-offs, and steer-by-wire implementation constraints.
-
Commercial playbooks for OEMs and Tier 1 suppliers: channel strategies, retrofit monetization, subscription models for correction services, and after-sales service network design.
-
Supply chain and component-sourcing risk analysis, with mitigation strategies for GNSS chip shortages, sensor supplier concentration, and geopolitical sourcing risks.
-
M&A and partnership assessment: valuation benchmarks, integration risk frameworks, and illustrative deal archetypes tailored to strategic acquirers and financial sponsors.
-
Regulatory and standards implications, with compliance checklists and product design implications for emerging standards and upcoming heavy-vehicle greenhouse gas regulations.
Market Snapshot (High-Level)
The global market exhibited sustained expansion through 2025, with the study anchoring 2025 as its base year. The forecast anticipates continued growth into 2026 and beyond, driven by improved GNSS correction networks, broader ISOBUS rollout, and stronger OEM–aftermarket integration. Market concentration ratios indicate that the top three and top five players hold a meaningful share of the market—enough to influence pricing and standards, but not so overwhelming as to block well-positioned entrants.
Competitive Landscape: Who Matters and Why
Industry participants include traditional agricultural OEMs, component specialists, and precision-technology firms. Our competitive analysis assesses product breadth, integration depth, channel reach, and software/service capabilities. Representative companies analyzed in depth include:
-
John Deere (Moline, Illinois, USA) — Robust factory-installed guidance (AutoTrac) and an integrated ecosystem, notable for high-precision RTK options and deep OEM channel control. Website: https://www.deere.com
-
CNH Industrial (Case IH / New Holland) (London / Basildon, UK) — Offers AFS AccuGuide and related solutions; benefits from Raven integration and a dual-path strategy of OEM integration plus dealer-led aftermarket. Website: https://www.cnhindustrial.com
-
AGCO Corporation (Fendt, Massey Ferguson, Valtra) (Duluth, Georgia, USA) — ISO-compliant interfaces, high precision across hydraulic and steer-by-wire platforms; strong brand presence in multiple farm segments. Website: https://www.agcocorp.com
-
Trimble Agriculture (Westminster, Colorado, USA) — Specialist in mixed-fleet retrofit kits and OEM integrations, with strong GNSS and software stacks for fleet management. Website: https://agriculture.trimble.com
-
Topcon Agriculture (Livermore, California, USA) — Established in automated steering systems with multi-mode steering support and compatibility focus. Website: https://www.topconpositioning.com
-
Hexagon Agriculture (Cochrane, Alberta, Canada) — Modular kits with flexible actuation options and strong integration into Hexagon guidance ecosystems. Website: https://hexagon.com
-
Raven Industries (Sioux Falls, South Dakota, USA; part of CNH Industrial) — Precision guidance specialist emphasizing operational efficiency and overlap reduction. Website: https://ravenind.com
-
CLAAS (Harsewinkel, Germany) — Integrated GPS PILOT and CEMIS auto-steering solutions in tractor lines, with strong European market access. Website: https://www.claas.com
-
CHC Navigation (CHCNAV) (Shanghai, China) — Retrofit-focused NX series offering high RTK-level accuracy and broad ISOBUS support; active product launches through 2025–2026. Website: https://agriculture.chcnav.com
-
AG Leader Technology (Ames, Iowa, USA) — Precision steering integrated with farm data platforms and decision-support displays. Website: https://www.agleader.com
Our profiles go beyond glossy product statements to evaluate installed-base economics, dealer margins, retrofit versus OEM attachment rates, and software monetization potential.
Notable Industry Developments and Standards
-
Product activity: Late-2025 and early-2026 product moves—most notably CHC Navigation’s NX612 launch and FJDynamics’ ISOBUS-focused system updates—signal intensified competition in the retrofit and mixed-fleet segments. Raven’s ongoing emphasis on efficiency reinforces the market’s productivity narrative.
-
Standards and safety: ISO 18497-1:2024 introduces clarified safety expectations for highly automated agricultural machinery, influencing product testing, compliance roadmaps, and claims about system autonomy levels. Our report maps how compliance timelines affect time-to-market and warranty exposure for 2026 product launches.
-
Technology floor: RTK GNSS combined with IMU-based terrain compensation is now an operational baseline for ±2.5 cm accuracy in many field operations. This technical bar raises the entry threshold but creates differentiation opportunities around service reliability, correction availability, and ease-of-install retrofit form factors.
-
Regulatory interplay: Emerging heavy-vehicle regulations (e.g., EPA Phase 3) create indirect levers that will influence powertrain-electronics integration and longer-term vehicle architecture decisions relevant to auto-steering system suppliers.
Strategic Imperatives for 2026
-
Prioritize software and services: With price competition on hardware intensifying, recurring revenue streams—correction services, over-the-air updates, telematics subscriptions—are key to sustaining margins. Firms should develop bundled offerings that combine guidance accuracy guarantees with uptime SLAs.
-
Choose integration vectors: OEMs must decide between deep factory integration and certified retrofit ecosystems. Each path has distinct margin, warranty, and channel-control implications; our report provides decision frameworks and sensitivity analyses for both.
-
Defend and attack around standards: Compliance with ISO 18497-1:2024 is a defensive necessity, but firms can turn conformance into a marketable credential—especially for higher-value farm segments and institutional buyers.
-
Optimize supplier portfolios: Secure long-term sourcing for high-precision GNSS modules and IMUs, and hedge via dual-sourcing strategies to mitigate supply shocks. Our sourcing playbook includes supplier scorecards and contract clauses to protect delivery and IP.
-
Plan M&A pragmatically: Mid-sized technology players with strong retrofit penetration and software platforms are attractive targets. We outline acquisition integration plans that preserve dealer relationships and accelerate route-to-market.
How PW Consulting Helps Executives in 2026
Our report is a tool to accelerate and de-risk 2026 decisions. Beyond the dataset and market model, clients receive: strategic roadmaps, negotiation support for partnership agreements, product-market fit assessments for specific farm-size tiers, and an acquisition due-diligence pack tailored to auto-steering assets. For boards and executive teams, the study offers a concise decision framework to prioritize investments that maximize IRR while controlling operational risk.
To access full segment-level data, proprietary forecasts by region and system type, and the detailed company scorecards that underpin our recommendations, please visit the report page. This preview intentionally omits the granular subsegment figures that are critical for transaction execution; the full report contains the complete datasets, model files, and Excel-ready scenarios required for capital planning and commercial negotiations.
For detailed analysis of this topic, please visit the official page: Worldwide Auto Steering for Tractor System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Insect Growth Regulators Market Poised to Grow at a 5.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Insect Growth Regulators Market — Strategic Outlook for 2026 Decisions
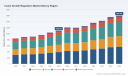
PW Consulting's latest market briefing on the Worldwide Insect Growth Regulators (IGR) market synthesizes rigorous quantitative modeling and on-the-ground commercial intelligence to inform executive decisions in 2026. Our analysis shows the market has expanded steadily from the early 2020s and, building on a multi-year momentum, reached approximately USD 1.11 billion in 2025. Under the forecast scenarios presented in this report, the market is projected to grow at a compound annual growth rate of 5.5% through the 2026–2032 horizon, with a baseline path that leads toward roughly USD 1.61 billion by 2032. These macro trends frame a set of clear strategic imperatives for manufacturers, distributors, agribusinesses, and professional pest-management services planning for the next three to seven years.
Worldwide Insect Growth Regulators Market
Why this report matters for 2026 decision-makers
- Translate macro momentum into prioritized investments: we identify which technology classes, application channels, and commercial models are most likely to deliver differentiated returns without disclosing the proprietary segment-level figures reserved for the full report.
- De-risk portfolio roadmaps: the briefing includes regulatory-scenario planning, resistance-management overlays, and raw-material supply stress-tests that directly feed product development and launch timelines.
- Enable targeted M&A and partnership screening: our competitive mapping and concentration metrics highlight structural consolidation opportunities and tactical adjacencies for bolt-on acquisitions or licensing deals.
Market dynamics shaping 2026 strategy
- Scientific innovation continues to re-shape product positioning. New chemistry classes and formulation technologies (including next-generation ketoenols and advanced chitin synthesis inhibitors) are enabling systemic behavior and lower-residue claims, altering the value proposition for both row-crop and specialty-horticulture customers.
- Regulatory complexity is intensifying. EPA and other authorities maintain product-group classifications and label constraints that affect permissible use patterns and claims; specific product labels continue to govern where and how certain granular or feed-through formulations may be applied.
- Sustainability and residue profiles are increasingly commercial requirements. Growers and retailers are elevating low-residue, integrated pest management (IPM)-compatible solutions, driving premiumization opportunities for compliant IGR formulations.
- Urban and animal-health channels show differentiated growth dynamics. Demand in professional pest control and livestock applications is driven by resistance management needs and the advantage of targeted developmental-disruption modes of action.
- Supply-chain sensitivity centers on specialized intermediates. Many IGR actives are synthesized from niche chemical intermediates, which creates concentrated upstream risk and creates windows for forward integration or hedging strategies.
Competitive landscape — what leaders are doing (and what it means)
The market features a mix of large crop-protection multinationals and specialist formulators. Leading global players have been active on multiple fronts: portfolio refreshes, new product launches, and tailored formulations for regulatory-constrained markets. PW Consulting’s competitive review profiles the strategic posture and recent moves of the primary incumbents — including major chemical and agricultural companies — to help you discern patterns without revealing proprietary market shares.
Worldwide Insect Growth Regulators Market
- Bayer AG has introduced next-generation systemic IGR chemistry designed to move both foliar and rootward, signaling a push into systemic control for sap-feeding pests and an intent to capture value in high-residue-sensitivity crops.
- Syngenta’s enhancements to urban pest-control portfolios emphasize resistance management and formulation efficacy in professional markets — an indicator of continued investment in non-agriculture channels.
- BASF and Sumitomo remain focused on agricultural staples and regional product compliance, including low-residue chitin synthesis inhibitor offerings tailored for rice and horticulture contexts.
- Specialist firms and subsidiaries (including companies focused on feed-throughs and poultry/livestock applications) are refining niche propositions that complement the broader crop-protection portfolios of larger players.
Collectively, these strategic moves underscore an important market reality: concentration is meaningful but not extreme. Our calculated concentration metrics show a market where the top three and top five players exert notable influence over price and distribution, yet significant room exists for regional specialists and innovators to capture adjacent value. The full report provides a detailed, source-backed competitive matrix and alliance map that supports screening of acquisition targets or regional partnerships.
Worldwide Insect Growth Regulators Market
What the report contains — practical, operational modules
This briefing is a preview of a comprehensive market research product designed for immediate operational use. The full report includes:
- A transparent market-sizing and forecasting methodology (historical review, 2025 base-year calibration, and scenario-based projections through 2032)
- Segment performance dashboards across types, applications, and regions (with growth drivers and risk annotations) — note: segment-level numeric detail is available in the full report
- Regulatory-impact maps and label-practice trackers that model how product-label restrictions and group classifications alter effective addressable markets
- Supply-chain and raw-material vulnerability assessment, including vendor concentration, lead-time exposure, and cost pass-through modeling
- Commercial playbooks for channel-specific GTM (agriculture, greenhouse/horticulture, residential & commercial pest control, and livestock/animal-health)
- Product development and pricing frameworks for low-residue and systemic IGR launches
- Opportunity matrices for M&A, licensing, and co-development, with shortlist templates for target screening
- Resistance-management intelligence and stewardship guidelines to preserve product life-cycle value
How to apply these insights in 2026
- Allocate R&D and regulatory capital toward chemistries and formulations that align with both residue-concerns and IPM adoption — prioritize projects with clear regulatory pathways in key export markets.
- Recalibrate commercial segmentation: differentiate go-to-market approaches between urban/professional channels and agricultural/greenhouse clients; channel economics and adoption curves differ materially.
- Hedge raw-material exposure: evaluate forward contracts, dual-sourcing of specialized intermediates, or select upstream investments to stabilize margin volatility.
- Use scenario-planning to stress-test product launch timelines against probable regulatory tightening and potential resistance-acceleration outcomes; build contingency in launch budgets and timelines.
- Target bolt-on acquisitions and licensing deals that fill either geographic distribution gaps or accelerate time-to-market for differentiated, low-residue assets.
Scenario lens and principal risks
PW Consulting’s forecast framework uses a baseline scenario consistent with the 5.5% CAGR pathway, augmented by upside and downside cases that factor in faster adoption of systemic and low-residue technologies or, conversely, accelerated regulatory restrictions or upstream raw-material shocks. Principal risks we model include the evolution of insect resistance, localized label-based use restrictions (including product exclusions for specific crop uses), and supply-chain disruptions to niche intermediates. Each scenario in the full report includes quantified impacts and recommended mitigation actions.
What you can expect from the full report (and why to request it)
Consider this briefing a strategic trailer: it demonstrates PW Consulting’s data-driven approach, market modeling rigor, and operationally focused recommendations while reserving the granular segment, regional, and channel-level numbers for subscribers and purchasers of the complete study. The full report unlocks proprietary datasets, downloadable models, and an actionable list of targets and priorities tailored to corporate strategy planning for 2026.
About PW Consulting’s approach
PW Consulting combines primary interviews with manufacturers, distributors, regulatory specialists, and end-users with secondary data verification and proprietary forecasting algorithms. Our modeling triangulates historical shipment data, regulatory timelines, pricing dynamics, and technological adoption curves to produce forecasts you can operationalize. Where appropriate, we annotate regulatory and labeling constraints, synthesize chemical-intermediate supply-chain exposure, and map competitive intent based on recent product launches and portfolio moves.
For senior leaders preparing budgets, M&A roadmaps, or product-launch playbooks for 2026, this market briefing clarifies where to accelerate, where to hedge, and where to partner. To access the detailed segment breakout tables, country-level demand models, and the full competitive matrix — including active licensing targets, SKU-level price models, and scenario-based financial impacts — please contact PW Consulting or visit our report page to obtain the complete Worldwide Insect Growth Regulators Market study and supporting data packages.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Growth Regulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Metal Fabrication Outsourcing Services Market Set to Expand at a 5.29% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Metal Fabrication Outsourcing Services Market — Strategic Outlook for 2026
Executive summary
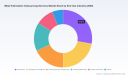
The Worldwide Metal Fabrication Outsourcing Services market is entering a pivotal phase. Our latest PW Consulting market study benchmarks the industry at an estimated USD 84,052.0 Million in 2025 and projects expansion to approximately USD 120,655.4 Million by 2032, supported by a compounded annual growth rate (CAGR) of 5.29% over the 2026–2032 forecast window. This growth is being driven by a combination of reshoring trends, demand for prefabrication in infrastructure and industrial projects, digitization of quoting and manufacturing workflows, and continued adoption of automation to offset skilled labor shortages.
Worldwide Metal Fabrication Outsourcing Services Market
This release outlines the strategic implications of those findings for corporate decision‑makers preparing plans for 2026. It intentionally showcases the report’s analytical depth and practical value while withholding granular sub‑segment figures to encourage direct engagement with the source report for procurement- and investment‑grade datasets.
Worldwide Metal Fabrication Outsourcing Services Market
Why this report matters for 2026 decision-making
- Investment prioritization: our forecast and scenario analysis converts market momentum into actionable CAPEX and capability roadmaps for operations, automation, and digital procurement.
- Sourcing strategy: the study clarifies when to insource critical metalwork versus when to leverage specialist outsourcing partners to accelerate time‑to‑market and control working capital.
- M&A and partnerships: forward-looking synergy maps and value-capture templates identify acquisition targets and JV structures that close capability gaps quickly.
- Commercial negotiation: TCO models and contract playbooks in the report translate macro pressures into practical commercial levers — indexation, pass‑through clauses, lead‑time guarantees, and warranty structures.
Market dynamics shaping 2026 strategy
Several contemporaneous forces are shaping demand, pricing, and the competitive equilibrium in metal fabrication outsourcing. Our analysis synthesizes raw material trends, labor market realities, regulatory drivers, and macro supply‑chain shifts to provide a comprehensive view of near‑term risk and opportunity.
Worldwide Metal Fabrication Outsourcing Services Market
- Material price volatility and input cost dynamics: steel benchmark prices remain a central operational factor — for context, the global steel benchmark was reported at 3,154 CNY/T as of April 30, 2026. At the same time, upstream commodity dynamics show iron ore easing from previously elevated levels and metallurgical coal prices moderating. These movements create a mixed picture: margin pressure persists in the short term for low‑mix, high‑volume work, while stable or declining iron ore/coal inputs can improve profitability for vertically integrated producers over the medium term.
- Labor scarcity and automation adoption: persistent shortages of skilled welders and fabricators are pushing both buyers and suppliers toward targeted automation — robotic welding cells, automated bending and cutting lines, and AI‑augmented quality inspection. Our fieldwork finds that automation investments are increasingly evaluated not only on unit cost reduction but on resilience, quality consistency, and labor retention metrics.
- Regulatory and ESG drivers: energy transition imperatives and decarbonization commitments are redirecting investment toward prefabrication, lightweighting, and process electrification. Meanwhile, digitalization is catalyzing M&A activity as traditional fabricators acquire software and digital quoting capabilities to remain competitive.
- Supply‑chain strategy: reshoring and diversification: geopolitical dynamics and tariff uncertainty continue to influence sourcing choices. Firms are increasingly balancing cost with strategic resilience, leading to multi‑sourcing strategies and greater use of regional outsourcing hubs.
- Market structure: the sector remains fragmented, with the top three and top five players accounting for a relatively small share of global revenue, underscoring abundant opportunities for consolidation, regional champions, and specialist niche players.
Competitive landscape — how the leading profiles are evolving
The report provides an actionable competitor matrix that assesses scale, service breadth, specialization, digital maturity, and go‑to‑market models. High-level strategic archetypes emerging from our vendor analysis include global diversified integrators, heavy‑structure specialists, precision and rapid‑turn providers, and digital marketplaces. Illustrative positioning follows:
- Global diversified integrators (scale and integration): Established industrial players with broad metalworking footprints are leveraging vertical integration and scale to supply infrastructure and heavy equipment applications. Their competitive edge is in large‑volume, long‑cycle contracts and the ability to internalize steel processing and fabrication.
- Heavy‑structure and engineering specialists: These firms focus on large welded structures, heavy machining, and complex assemblies for construction, mining, and industrial equipment. They compete on engineering capability, project management, and the ability to execute oversized and technically demanding scopes.
- Precision and rapid‑turn specialists: A distinct cohort markets speed and agility — digital quoting, quick-turn sheet metal, and low‑volume CNC work — serving prototyping, aftermarket, and high‑variety manufacturing needs.
- Marketplace and platform models: Digital marketplaces aggregate capacity across regional suppliers, providing buyers with rapid price discovery, diversified sourcing, and shorter procurement cycles — a disruptive model especially for low‑to‑mid complexity assemblies.
Company‑level observations from our competitive review:
- Mid‑sized specialists that combine design and prototyping with light gauge fabrication are winning share in electronics enclosures and industrial components by shortening development cycles.
- Heavy fabrication incumbents are defending margins through scale, integration into steel supply chains, and long‑term OEM partnerships in construction and energy sectors.
- Marketplaces and digital manufacturers are expanding service portfolios (rapid prototyping to low‑volume production) and are increasingly referenced in buyer RFPs for flexibility and speed.
- Recent corporate activity — including capability expansions via acquisition — evidences a competitive trend: established fabricators are buying design, digital quoting, or light‑gauge capabilities to broaden addressable markets and capture higher‑margin product engineering work. (For example, a capability expansion announced in late 2025 by a U.S. fabrication specialist illustrates this approach.)
What’s in the PW Consulting report — practical content for immediate action
This study is structured as an operational playbook as much as a market forecast. The deliverables were designed with procurement, operations, corporate development, and engineering leaders in mind, and include:
- Composite market forecasts and scenario analyses (base, downside, and upside) through 2032, with sensitivity to steel and alloy cost paths and reshoring assumptions.
- A regional and service‑type segmentation framework with supplier counts, capacity indicators, and risk heatmaps (note: detailed sub‑segment financials are reserved for the full report).
- Supplier scorecards and due‑diligence checklists covering capacity, certifications, quality systems, environmental performance, and digitization maturity.
- TCO and supplier comparison models incorporating material pass‑through clauses, lead‑time risk premia, and automation amortization schedules.
- Practical contract templates and negotiation playbooks, including clauses for indexation, force majeure, and quality dispute resolution.
- Automation and digitalization ROI calculators: welding robotics, CNC cell deployment, and online quoting platforms.
- M&A readiness and integration blueprints tailored to buyers seeking capability expansion in prefabrication and digital manufacturing.
Strategic recommendations for 2026
- Prioritize supplier partners that can demonstrate both digital quoting and automation maturity; speed and predictable lead times will be decisive in procurement negotiations.
- Run targeted automation pilots in high‑touch welding and finishing cells to quantify labor substitution, quality improvement, and lead‑time gains; use pilot results to build a five‑year automation roadmap.
- Reassess the make‑vs‑buy decision across product families using the report’s TCO models — particularly for assemblies where design‑for‑manufacturability can materially lower lifecycle costs.
- Pursue diversification of supplier footprints to manage geopolitical and tariff risk, but balance this with supplier consolidation where scale unlocks better material sourcing and process standardization.
- Embed raw material hedging and indexation clauses into multi‑year supply contracts to reduce margin volatility, and align pass‑through mechanisms with key customers where appropriate.
- Use digital marketplaces strategically for prototyping and low‑volume work while reserving strategic, high‑complexity assemblies for vetted specialty partners or captive production.
- Consider M&A or JVs to acquire prefabrication and light‑gauge capabilities rapidly; integration templates in the report reduce execution risk for buyers.
How to use this study
Leaders can apply the report as a decision support system across three main use cases: procurement optimization (short‑term contracting and supplier rationalization), operations planning (automation investments and capacity planning), and strategic corporate development (M&A, partnerships, and geographic expansion). Each use case is supported by downloadable tools, templates, and sensitivity models.
Next steps — where to get the full dataset
This press release highlights strategic takeaways and the practical value of PW Consulting’s Worldwide Metal Fabrication Outsourcing Services market research. Detailed sub‑segment numbers, regional breakouts, supplier‑level revenue estimates, and downloadable TCO calculators are contained exclusively in the full report. Those proprietary datasets and the accompanying Excel models are essential for transaction diligence, supplier negotiations, and capital budgeting.
To access the full report, datasets, and the suite of operational tools referenced above, please visit the PW Consulting report page. The full deliverable provides the granular insights necessary to convert the high‑level strategies outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fabrication Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Umbilical Cable Market to Reach USD 6,768.18 Million by 2032, Growing at a 7.1% CAGR
By pmarketresearch, 2026-07-15
Worldwide Umbilical Cable Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As energy portfolios and subsea infrastructure projects accelerate across regions, umbilical cable systems remain a mission‑critical enabler for offshore production, power export, and emerging renewable arrays. PW Consulting’s new Worldwide Umbilical Cable Market report (base year 2025; historical: 2020–2025; forecast: 2026–2032) provides the executive-level, decision‑ready intelligence that procurement, engineering, and corporate development teams must use to shape capital allocation and partner selection in 2026.
Worldwide Umbilical Cable Market
Executive summary — what the market picture means for 2026 decisions
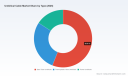
The global umbilical cable market has moved from a cyclical trough into a sustained growth phase. Aggregate market revenues expanded from approximately USD 3.15 billion in 2020 to about USD 4.19 billion in 2025, and our model forecasts continued expansion through the 2026–2032 horizon, reaching nearly USD 6.77 billion by 2032. The forecast period is underpinned by a compound annual growth rate (CAGR) of 7.1% (2026–2032).
Worldwide Umbilical Cable Market
For 2026 corporate planning cycles, three implications are immediate and actionable:
Worldwide Umbilical Cable Market
- Capital allocation should reflect a structurally larger market and longer project lifecycles—project pipelines justify earlier procurement engagement and longer lead‑time contracts.
- Supply‑chain resilience is a strategic priority—raw material supply (notably high‑grade stainless and super‑duplex tubes) and manufacturing capacity are the pinch points that will determine schedule risk and margin volatility.
- Vendor strategy must balance scale and specialization—market concentration suggests dominant suppliers will continue to influence pricing and technical roadmaps; yet niche and regional specialists will be critical for bespoke and near‑field projects.
Market trajectory and underlying dynamics
Our historical analysis shows recovery and reinvestment across subsea developments since 2021, with a sharper acceleration in contract activity and order books by 2024–2025. The forecast to 2032 incorporates ongoing deepwater/ultra‑deepwater project awards, electrification of subsea infrastructure, and the expansion of offshore renewable export arrays that require bespoke umbilical architectures.
Key demand drivers incorporated in our scenario work include:
- Scale and depth complexity of hydrocarbon developments that require longer, higher‑specification umbilicals for control, chemical injection, and power delivery.
- Growth in offshore wind and floating arrays, which create adjacent opportunities for dynamic electrical and hybrid export cables and support umbilical‑like systems for floating substation control.
- Regulatory emphasis on safety and lifecycle performance, pushing operators to prioritize higher‑specification materials and full‑lifecycle assurance contracts.
On the supply side, our analysis highlights ongoing investment in R&D and manufacturing capacity changes to accommodate longer lengths and specialized constructions. A spike in orders for umbilical tubing and associated components in early 2026 illustrates persistent demand for high‑spec materials.
Competition and concentration — what buyers must know
The marketplace is meaningfully concentrated: our competitive concentration metrics indicate that the top three suppliers capture a majority share of industry revenue, while the top five capture well over three‑quarters. This structure creates both opportunities and risks for buyers and investors:
- Opportunity: scale players offer integrated SURF (subsea, umbilicals, risers, and flowlines) solutions, global delivery footprints, and advanced engineering capabilities that reduce integration risk on large, complex projects.
- Risk: dependence on a narrow set of large vendors increases exposure to pricing power, lead‑time constraints, and strategic prioritization of larger clients—smaller operators and EPCs can face deferred deliveries or premium pricing when capacity tightens.
Profiles of core players in our vendor matrix (publicly available information and primary interviews) indicate distinct value propositions:
- TechnipFMC — world leader in engineered steel‑tube and hybrid umbilicals with global manufacturing and integrated subsea capabilities; strong in complex, bespoke umbilicals for deep and harsh environments.
- Oceaneering — deep experience in complete umbilical solutions and a diversified portfolio that includes ROV, renewable array cabling, and IWOCS (intervention) services; attractive for projects requiring strong installation and subsea service support.
- OneSubsea (SLB) — leverages patented designs and integrated production umbilicals with strong credentials in ultra‑deepwater, flow assurance, and multiphase control applications.
- Prysmian Group, JDR, and regional specialists — established cable technology and full‑lifecycle service capabilities; attractive partners for electrical power and hybrid systems as well as for long tie‑backs.
- Smaller/bespoke specialists (e.g., Fibron BX, Umbilicals International, APAR, Tratos/MFX) — offer flexibility, rapid customization, and niche manufacturing capacity that can be decisive for fast‑turn or highly specialized projects.
- Component and tube suppliers (e.g., Tubacex) — critical upstream players whose order books and capacity expansions signal medium‑term supply availability for steel tube umbilicals.
Recent market intel underscores these dynamics: major tube orders reported in early 2026, specialized testing contracts for pre‑deployment and lay‑operations in 2025, and industry conferences in 2025 that highlighted standards, testing, and lifecycle assurance—all confirming active capital deployment and intensified vendor competition.
Supply chain, raw materials and risk management
Steel and super‑duplex tubing remain the technical backbone of high‑pressure, high‑tensile steel‑tube umbilicals. Our procurement risk matrix elevates raw material availability, quality certification cycles, and fabrication capacity as the top three supply‑side risks. Tubing order wins documented in early 2026 are an early warning signal that lead times for high‑spec seamless tubes will be a negotiating lever for buyers in 2026.
Recommended mitigation actions for 2026:
- Lock in conditional purchase agreements (CPAs) for critical long‑lead items to protect schedules while preserving price flexibility.
- Qualify secondary and regional suppliers to diversify risk, especially for projects with geographic or regulatory constraints that favor local content.
- Invest in joint R&D or co‑supply agreements with tube and cable manufacturers to secure preferential capacity and alignment on technical specifications.
Practical content in the full report — what you’ll get
The PW Consulting report translates market projections into a toolkit for action. Highlights include:
- Detailed market sizing and scenario forecasts (2026–2032) with sensitivity analysis to commodity and capex cycles.
- Vendor benchmarking framework covering technical capability, manufacturing footprint, contract performance, and EHS/compliance credentials.
- Procurement playbooks for CAPEX vs OPEX contracting, preferred commercial terms, warranty and testing clauses, and risk allocation templates.
- Supply‑chain heat maps and lead‑time dashboards that identify pinch points by component and region (note: the public brief intentionally withholds granular regional and application splits—these are included in the full report).
- Investment and M&A screen with candidate profiles for bolt‑on acquisitions, forward integration, and joint venture collaboration in renewables and SURF segments.
- Case studies and cost models for typical project types (shallow, deepwater, ultra‑deepwater) showing financial impacts of specification choices and supplier selection.
These operational deliverables are designed to be directly inserted into 2026 project tendering, budgeting, and strategic planning cycles. The report’s annexes include standardized RFP templates, scope checklists for FAT and pre‑lay testing, and contract clause language optimized for long‑delivery critical items.
Strategic recommendations for 2026 — a concise action plan
- Prioritize early supplier engagement: shift from price‑only RFQs to technical‑commercial workshops with shortlisted vendors to de‑risk specification mismatches and secure capacity windows.
- Hedge raw material exposure: consider option arrangements with leading tube suppliers and index‑linked pricing mechanisms tied to stainless steel benchmarks.
- Adopt a dual‑track vendor strategy: secure one strategic global supplier for system integrity and a second, nimble specialist for customization and schedule flexibility.
- Invest in joint testing and performance assurance: co‑funded FAT, extended field trials, and lifecycle monitoring to reduce long‑tail warranty exposure and total cost of ownership.
- Evaluate vertical integration selectively: for large organizations with sustained offshore programs, securing tube supply or inshore manufacturing partnerships can yield margin and schedule advantages.
How PW Consulting’s intelligence will accelerate your 2026 decisions
This report is intended for C‑Suite decision makers, procurement leads, EPCI contractors, and corporate development teams preparing 2026 budgets and 2027–2028 execution plans. It combines rigorous market forecasting with actionable procurement and technical guidance so that teams can:
- Convert macro forecasts into quantifiable project budget contingencies;
- Design vendor selection processes that reduce schedule risk and lifecycle cost;
- Identify M&A or partnership targets for capabilities in high‑growth segments such as hybrid and power umbilicals;
- Integrate compliance, testing, and certification planning into procurement timelines to avoid late‑stage rework.
Next steps
PW Consulting invites stakeholders to review the full Worldwide Umbilical Cable Market report for the detailed segmentation, regional deployment scenarios, and supplier scorecards that underpin the recommendations summarized here. The public brief intentionally omits granular regional and application share tables to encourage direct engagement with the report, which includes downloadable tools and customizable models for internal use.
For 2026 planning cycles, teams who incorporate the report’s procurement playbooks and risk mitigation measures in Q1 will be best positioned to capture value as the market expands and competition for capacity intensifies.
Methodology and data integrity
The analysis uses a base year of 2025 with historical data covering 2020–2025 and a forward forecast through 2032. Revenue figures are expressed in USD Million. Our methodology combines bottom‑up demand modeling by project type, supplier capacity assessment, and macroeconomic scenarios, cross‑checked against supplier disclosures, industry conference findings, and primary interviews. Concentration metrics and supplier profiles draw from company public filings, press releases, and verified industry sources.
For detailed analysis of this topic, please visit the official page: Worldwide Umbilical Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reformer Unit Market Poised to Grow at a 6.95% CAGR
By pmarketresearch, 2026-07-15
Worldwide Reformer Unit Market 2026: Strategic Intelligence for Executive Decision-Making
PW Consulting’s latest market study, Worldwide Reformer Unit Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers a focused, actionable intelligence package designed for C-suite executives, project developers, technology licensors, and industrial investors planning capital and strategic moves in 2026. The study quantifies the macro trajectory of the market and pairs it with tactical playbooks—enough to inform urgent decisions while deliberately withholding detailed segment-level datapoints to encourage direct access to the full dataset and vendor matrices.
Worldwide Reformer Unit Market
Big-picture momentum: growth, scale and what it means for 2026 planning
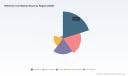
Our analysis shows the reformer unit market expanding steadily through the mid-2020s. Between 2020 and 2025 the market grew from approximately USD 620.5 Million to USD 864.5 Million (base year 2025). Looking forward, the market is forecast to continue expanding throughout the 2026–2032 horizon, reaching just under USD 1.4 Billion by 2032 under the central scenario. The consolidated compound annual growth rate for the forecast window is 6.95%—a pace that signals reliable demand growth but also underlines the need for disciplined capital allocation and technology selection.
Worldwide Reformer Unit Market
For 2026 decision-makers this trajectory matters for three practical reasons: (1) it supports multi-year project sanctioning on a foundation of volume growth, (2) it highlights the viability of modular and small-site solutions that target faster deployment cycles, and (3) it creates a premium for technologies and suppliers that can demonstrate lifecycle cost advantages under evolving regulatory regimes.
Worldwide Reformer Unit Market
What the report contains: practical deliverables for executives and project teams
- Concise market sizing and time-series revenue forecasts (2020–2032) presented in USD Million with scenario variants that stress-test fuel price, carbon price, and CAPEX assumptions.
- Technology and product roadmaps for steam methane reformers, catalytic reformers, autothermal reformers and emerging electrified reformer architectures—each assessed on metrics that matter to buyers (efficiency, retrofit fit, modularization potential, OPEX drivers, emissions profile).
- Detailed vendor assessment framework—qualitative scoring and procurement playbooks that reveal strengths, supply risks, and aftermarket revenue potential for licensors, EPCs and equipment manufacturers.
- Unit economics templates and Excel-based models proprietary to PW Consulting for quick scenario runs (CAPEX/OPEX, levelized hydrogen/ammonia/methanol cost curves, and abatement cost curves integrating CCS and electrification options).
- Retrofit and greenfield investment playbooks—step-by-step operational checklists, capex phasing guidance, and contracting structures that optimize permits, heat integration and emissions compliance.
- Supply-chain risk register and procurement strategy tied to commodity cycles (notably high-temperature steel and specialty alloys) and lead-time sensitivities for long-lead components.
- Regulatory and incentives tracker aligned to major carbon-pricing regimes and energy-efficiency mandates—useful for project finance and grant capture strategies.
Competitive dynamics: how to read the vendor landscape without being distracted by noise
The market is served by an ecosystem of licensors, EPCs, catalyst producers and specialty component manufacturers. Our vendor analysis focuses less on headline market shares and more on capabilities that determine project outcomes:
- Linde Engineering: Proven strength in steam reformers for hydrogen and ammonia projects, with modular HYDROPRIME® offerings and a strong record of small on-site deployments. Their recent run of on-site project wins underscores demand for fast-to-deploy, decarbonization-aligned packages.
- Honeywell UOP and Axens: Both are established for catalytic reforming applications in refining contexts, offering licensors, catalyst suites and services—critical partners for refiners pursuing high-value liquid product optimization.
- KBR and Technip Energies: Position themselves as integrated technology and EPC pathway providers for both steam and autothermal reforming, well-suited to large-scale hydrogen and syngas projects where single-source responsibility reduces execution risk.
- Johnson Matthey: A go-to supplier for high-performance reforming catalysts and pre-reforming technologies—important when catalyst lifecycle and activity drive operating economics.
- MetalTek, Kubota and other specialty component vendors: These firms supply high-temperature reformer tubes and manifolds. Their metallurgy, casting methods and proven creep resistance materially extend asset life and influence life-cycle cost models.
- Regional EPCs and integrators (e.g., Wood plc, Larsen & Toubro): Provide locally embedded execution capability—valuable in markets where content rules, local permits and labor practices drive schedule risk.
Recent industry developments reinforce strategic signals in the vendor landscape. Presentations and R&D pushes around electrified reformers and other low-carbon pathways indicate escalating technology competition: from conference disclosures on electrification as a decarbonization route to record wins for on-site hydrogen plants and long-term supply agreements tied to low-carbon ammonia projects. Together, these moves suggest an industry in the midst of capability-driven differentiation rather than pure price competition.
Regulatory and commodity dynamics that will shape procurement and financing in 2026
Two external forces deserve prime attention when setting 2026 priorities. First, regulatory pressure—especially stricter greenhouse gas limits and the spread of carbon pricing—will increasingly penalize conventional fuel-fired reformer designs that lack CCS or electrification-ready architecture. Independent analyses show that electrified reformer configurations can reduce direct flue-gas CO2 emissions by very large margins and improve thermal efficiency—metrics that materially affect project IRR when carbon is priced.
Second, input-material cycles matter. High-temperature steels and specialty alloy pricing and availability are key determinants of lead times and capex. Industry data indicate that steel prices are at or near the bottom of the current cycle in early 2026, with a moderate recovery expected in 2027. Procurement strategies that lock favorable suppliers, include alloy flexibility and use long-lead hedging clauses will yield lower program risk and improved schedule certainty.
Strategic implications and recommended actions for 2026
- Prioritize modularization for near-term growth: Given the market’s steady expansion and demand for fast, decarbonized on-site solutions, deploy capital first into modular or skid-mounted packages that shorten time-to-operation and limit balance-of-plant complexity.
- Pilot electrification and CCS integration now: Run targeted pilots to validate heat integration and control strategies for electrified reformers and retrofit-ready designs that make CCS addition straightforward. Early technical learning will pay off as carbon costs rise.
- Lock metallurgy supply lines: Negotiate framework agreements with reputable tube and manifold manufacturers and include alloy substitution options to protect schedule and cost in the face of commodity swings.
- Use lifecycle-based procurement criteria: Shift evaluation from lowest-capex toward LCO (levelized cost of operation) that integrates catalyst replacement cycles, energy sourcing scenarios, and carbon compliance costs. This changes vendor selection and financing terms.
- Structure commercial contracts to de-risk execution: Favor EPC or design-build models with clear performance guarantees, milestone-based payments, and penalties aligned to schedule slippage—particularly for projects with tight offtake windows.
- Prepare M&A and JV playbooks: Use the 2026 growth window to acquire niche capabilities (e.g., electrified heat integration, pre-reforming catalysts, modular fabrication yards) or to partner with regional EPCs to capture local content and execution advantage.
Why PW Consulting’s report matters to executives this year
Our report is not an academic exercise. It provides the decision-support tools that convert market signals into executable strategies: calibrated forecasts, vendor evaluations, unit-economics models, retrofit playbooks, and a regulatory tracker. For boards and investment committees, the study supplies evidence-based scenarios needed to justify capex, align procurement, and set realistic timelines for emissions reduction targets.
Importantly, the report purposefully conceals granular segment-level tables and certain regional/application splits from free previews. This “trailer” approach enables readers to verify the high-quality analytical scaffolding we present here while guiding them to the full dataset and interactive models available through PW Consulting’s report portal—resources that contain the detailed segmentation, regional forecasts, supplier scoring matrices, and downloadable Excel models necessary to finalize project-level investment cases.
Next steps
For executives preparing 2026 budgets and sanction packages: treat this study as the basis for three immediate actions—(1) run the PW Consulting unit-economics model under your feedstock and carbon-price assumptions, (2) issue RFPs that embed lifecycle performance metrics and alloy flexibility, and (3) scope at least one electrification or CCS pilot to lock early learning and optionality.
To access the complete dataset, detailed segmentation, vendor rankings and the interactive financial models that underpin our conclusions, please consult the PW Consulting report page. The full deliverable contains the granular tables and appendices required for due diligence, procurement negotiation, and final investment decisions.
PW Consulting remains available to support customized scenario runs, bidder shortlists, and transaction support for reformer unit projects worldwide. Our team combines sectoral engineering depth with macroeconomic and policy insight to convert market forecasts into executable corporate decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com