

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Biometric Signature Pads Market Set for 7.15% CAGR in 2026–2032

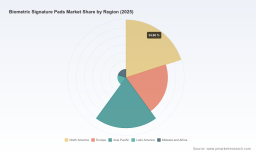
Biometric Signature Pads Market: Strategic Imperatives for 2026
PW Consulting’s latest market research on Biometric Signature Pads synthesizes five years of historical performance and a seven-year outlook to 2032, delivering a pragmatic, decision-ready roadmap for executives planning investments, procurement, or M&A in 2026. Our analysis combines market-size modeling, regulatory impact assessment, competitive benchmarking, and actionable playbooks — all designed to accelerate confidence while reserving detailed sub-segment matrices for the full report.
Biometric Signature Pads Market
Market snapshot: steady expansion, structural opportunity
The biometric signature pads market has shown steady expansion through the first half of the decade. Our base-year assessment (2025) places the global market at USD 480.0 million, up from USD 345.5 million in 2020, reflecting continued adoption in regulated and high-trust environments. Looking forward, we model the market growing at a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast period, reaching an estimated USD 778.3 million by 2032.
Biometric Signature Pads Market
Two structural features underpin the opportunity for 2026 decision-makers: (1) a modest-to-moderate market concentration among a handful of established hardware and solution vendors (our concentration analysis indicates the top three players account for a significant but not dominant share, with the top five increasing that share meaningfully), and (2) a persistent legal and compliance tailwind from e-signature frameworks that recognize biometric, dynamic data when implemented to applicable standards.
Biometric Signature Pads Market
Why this matters for 2026 strategy
- Revenue predictability and budgeting: A clear CAGR and model-driven forecast mean procurement and budget planners can move from pilot-phase conservatism to phased rollouts tied to measurable adoption curves.
- Regulatory certainty as a growth driver: Jurisdictions that embrace biometric graphometric evidence and device-level assurances are accelerating procurement in public sector, finance, and regulated corporate contexts.
- Competitive maneuverability: The market concentration profile leaves room for niche entrants, differentiation via security/certification, and strategic consolidation — all viable 2026 plays.
Key dynamics shaping the market
- Regulatory harmonization and legal recognition: The EU eIDAS framework and corresponding international standards (including ISO/IEC biometric protocols) continue to shape procurement specifications. Devices that can demonstrate compliance with qualified signature creation device requirements gain outsized procurement preference in public and regulated procurements.
- Security and trust as product differentiators: Buyers increasingly evaluate pads for multi-layered assurance — cryptographic key management, tamper-evident hardware, secure boot, and device-level attestation. Certifications and documented procedures now play a central role in contract awards.
- Functional convergence: Hardware vendors are converging on hybrid feature sets — color LCDs, pressure/velocity capture, fingerprint integration, NFC, and multi-touch — but differentiation remains via software ecosystems and integration toolkits that reduce deployment friction.
- Supply-chain pressures: Tariffs on electronics and component supply variability continue to affect bill-of-material costs and lead times. Buyers should expect cyclical price and availability swings driven by trade policy changes and logistics constraints.
Competitive landscape: profiles and tactical posture
Our report profiles the leading device and solution providers, assessing product roadmaps, channel strategies, integration capabilities, and target verticals. A selection of incumbent profiles:
- Topaz Systems (Simi Valley, CA): Broad product range spanning LCD and fingerprint-integrated pads; strengths in verticalized solutions for healthcare, legal, and financial services and a rich developer ecosystem.
- Scriptel Corporation (Columbus, OH): Focus on durable, high-throughput pen-based devices with deep integrations into healthcare workflows and point-of-sale environments.
- Wacom Co., Ltd. (Japan): Leverages decades of stylus and pressure-sensing expertise; positions its STU series around dynamic biometric capture and verification for high-assurance use cases.
- ePadLink (Interlink Electronics) (USA): Combines hardware with IntegriSign software to deliver legally robust e-signature workflows across enterprise stacks.
- StepOver GmbH (Germany): Focused on high-security, eIDAS-compliant devices; notable recent activity includes the December 2025 launch of a new rugged color-display model optimized for continuous, high-duty environments.
- Euronovate Group (Switzerland/Italy) and Signotec GmbH (Germany): Both emphasize European compliance (e.g., eIDAS), high-end security, and features for in-presence signing events.
Taken together, this set of vendors demonstrates two proven routes to market: scale through broad OEM/ISV partnerships and vertical specialization emphasizing compliance and reliability. For 2026, winning strategies will combine both — modular hardware platforms paired with turnkey integrations for prioritized verticals.
Strategic playbook for 2026 decision-makers
Based on scenario modeling and client engagements, PW Consulting recommends six parallel tracks for organizations evaluating biometric signature pad investments in 2026:
- Procurement optimization: Adopt a phased procurement tied to use-case prioritization. Begin with controlled pilots in high-compliance or high-volume points, instrument KPIs (throughput, error rates, user satisfaction), then scale modularly to reduce upfront capital outlay.
- Vendor selection criteria: Prioritize suppliers that demonstrate end-to-end compliance documentation, robust SDKs, and transparent security practices. Shortlist vendors that balance device resiliency with integration speed (i.e., reduced time-to-production).
- Product and R&D focus: For vendors and OEMs, the highest-return investments are in secure element integration, certified cryptographic stacks, and SDKs that lower integration cost for major enterprise platforms (EMR, core banking, ERP).
- Channel and partnership models: ISVs and system integrators that bundle software, certification assistance, and managed deployment services will command pricing power. For platform vendors, pursue OEM partnerships to embed signature capture into POS and kiosk ecosystems.
- Risk & compliance management: Implement device attestation and lifecycle controls; incorporate legal counsel during procurement to ensure firmware update policies and custody of cryptographic keys align with future-proofed signature validity.
- M&A and consolidation signals: Mid-market vendors with certified product stacks and verticalized client lists are logical tuck-in acquisitions for ISVs seeking to offer turnkey signing solutions — 2026 is likely to see opportunistic consolidation driven by buyers seeking to shortcut integration risk.
What the full PW Consulting report delivers
This briefing is a strategic preview. The complete PW Consulting Biometric Signature Pads Market report provides the operational detail that procurement teams, product leaders, and corporate development groups will use to execute in 2026, including:
- Our full market model (historical 2020–2025; forecast 2026–2032) with sensitivity scenarios and explicit assumptions.
- Comprehensive vendor dossiers with strengths/weaknesses, go-to-market routes, and integration readiness matrices.
- Regulatory impact analysis and a compliance checklist mapped to device-level features and certification pathways.
- A buyer’s implementation playbook: procurement RFIs/RFP templates, KPI frameworks, and testing protocols for legal admissibility and operational resilience.
- Strategic M&A screening criteria, including signals for attractive tuck-ins and a shortlist of targets whose capabilities accelerate time-to-market.
To preserve the value of our segmentation and to drive verifiable vendor selection, the report reserves detailed sub-segment tables and region-level revenue splits for the full document; these granular datasets are essential for transaction diligence and are available through the report portal.
Immediate actions for leaders
- CEOs & CFOs: Align capital planning to a phased rollout approach and reserve contingency for tariff-driven cost variability.
- CIOs & Heads of Procurement: Shortlist vendors based on documented compliance artifacts and demand vendor-led integration pilots with production data capture.
- Product & R&D Heads at vendors: Prioritize certified security modules and developer-friendly SDKs; document compliance for qualified signature creation to increase procurement appeal in regulated markets.
- Corporate Development: Evaluate tuck-in targets that offer certification, vertical footholds, or proprietary biometric processing algorithms — these assets materially shorten sales cycles.
PW Consulting’s analysis makes one conclusion clear: with a predictable growth trajectory and legal frameworks that increasingly favor certified biometric capture, 2026 will be a year when leaders can move from pilot curiosity to disciplined deployment — provided they pair vendor due diligence with robust compliance and supply-chain strategies. For executives ready to act, our full report supplies the data, templates, and vendor intelligence to convert opportunity into measurable outcomes.
Access the full PW Consulting Biometric Signature Pads Market report for the definitive datasets, vendor rankings, and executable playbooks to inform your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Biometric Signature Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com