

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Fuel Level Sensor Market at USD 950.0 Million in 2025, Poised to Reach USD 1,184.35 Million by 2032 on a 3.2% CAGR — Asia Pacific Leads with USD 413.08 Million

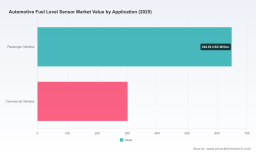
Worldwide Automotive Fuel Level Sensor Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As OEMs rewire powertrain strategies and suppliers recalibrate technology roadmaps, reliable intelligence on the automotive fuel level sensor market is becoming a strategic necessity. PW Consulting’s forthcoming Worldwide Automotive Fuel Level Sensor Market report — anchored on a 2025 base year and a 2026–2032 forecast horizon — distills the commercial, technological, and regulatory inflection points that will govern supplier selection, R&D prioritization, and M&A activity in 2026.
Worldwide Automotive Fuel Level Sensor Market
Why this market matters for 2026 decision-makers
-
Stable but evolving demand: The global market has demonstrated steady recovery and incremental growth in the early 2020s, with PW Consulting estimating the market at approximately USD 950 Million in 2025. Our forecast models indicate a compound annual growth rate (CAGR) of 3.2% over 2026–2032, reflecting a market that is neither hyper-growth nor stagnant — rather, one undergoing structural transformation.
Worldwide Automotive Fuel Level Sensor Market -
Concentration and competitive tension: Market concentration metrics show that the sector remains led by a handful of global players. This concentrated structure creates both barriers and levers for challengers: scale delivers OEM access and integration, while targeted innovation opens pockets of opportunity for focused specialists.
Worldwide Automotive Fuel Level Sensor Market -
Strategic intersection with powertrain transition: Although electrification reduces raw demand for fuel-system components over time, fuel level sensing remains mission-critical for internal combustion engine (ICE), hybrid, and certain multi-fuel applications during the transition. Suppliers and OEMs must balance short-term revenue with long-term repositioning.
Report snapshot — what PW Consulting delivers
This report is designed as a practitioner’s playbook for 2026. Highlights include:
-
Macro trajectory and scenario analysis: Base-case and downside scenarios incorporating EV penetration rates, fuel system lifecycle dynamics, and macroeconomic scenarios to stress-test revenue and margin outcomes through 2032.
-
Supplier matrix and OEM sourcing map: A validated supplier-OEM linkage framework that ranks vendors by technical fit, program wins, geographic strength, and integration capability (note: detailed program-level tables and value-by-segment are reserved for the full report).
-
Technology roadmap and cost curves: Comparative assessment of capacitive, ultrasonic, resistive (including Hall and reed-switch alternatives), and pressure-based solutions — focusing on accuracy, manufacturability, calibration complexity, and anticipated BOM evolution.
-
Regulatory & safety impact analysis: Quantification of near-term compliance requirements and the expected engineering lift associated with emerging standards and crashworthiness mandates, with guidance on testing protocols and certification timelines.
-
Supply chain risk & resilience diagnostics: Practical mitigation options for semiconductor lead-time volatility, raw-material exposure, and tiered-sourcing trade-offs — complete with a supplier continuity scoring tool that can be deployed in procurement reviews.
-
Commercial playbook: Prioritized action items across product, go-to-market, M&A, and alliance strategies for OEMs, Tier-1 suppliers, and focused component specialists.
Competitive landscape — who matters and why
The market’s competitive topology is a mix of global integrated suppliers, Tier-1 system houses, specialized sensor manufacturers, and cross-domain electronics players. Key players profiled in the report include Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner, Visteon, Sensata Technologies, CTS Corporation, TE Connectivity, Gill Sensors & Controls, and Methode Electronics. PW Consulting’s assessment focuses on three vectors: product breadth and depth, OEM program access, and strategic intent.
-
Robert Bosch GmbH — Bosch continues to leverage its fuel system integration capability, offering capacitive and ultrasonic options embedded in OEM fuel modules. Their strength lies in system-level integration and longstanding OEM relationships.
-
Continental AG — Continental’s recent supplier nominations underline its competitiveness in platform-level programs. Expect them to press on integration of temperature sensing and diagnostics linked to vehicle ECUs.
-
Denso Corporation — Denso’s collaborations with regional OEMs and its JDA activity in capacitive sensing for hybrid models position it strongly in Asia Pacific programs and cross-platform adaptations.
-
BorgWarner & Visteon — Both firms emphasize multi-fuel compatibility and cockpit-integrated sensing respectively, creating differentiated routes to OEM value capture.
-
Sensata, CTS, TE Connectivity, Gill, Methode — These focused specialists provide technological depth (pressure-based, variable resistor, ultrasonic, Hall-effect, ruggedized modules) that enables targeted wins in heavy-duty, off-road, and performance segments.
Recent industry moves underscore the market dynamics: product launches that expand sensing envelopes; supplier nominations that lock in platform-level exposure; and validation programs that shift credibility curves. PW Consulting maps these events to program timelines to show where near-term revenue and future optionality will accrue.
Segment dynamics and technological tensions
Three structural tensions define supplier choices in 2026:
-
Accuracy vs. robustness: Capacitive and advanced non-contact solutions offer improved accuracy in modern plastic tanks, but they demand more sophisticated calibration and software compensation. Ultrasonic alternatives can be attractive for non-intrusive measurement but face field calibration challenges in foaming or turbulent fuel conditions.
-
Componentization vs. system integration: OEMs increasingly prefer integrated fuel modules that reduce assembly complexity, favoring suppliers with module-level capability. Conversely, focused sensor specialists can out-innovate on sensing performance and supply niche applications.
-
Supply-side fragility: Semiconductor supply constraints have materially extended lead times for sensor ICs and microcontrollers in recent years, driving inventory and qualification strategies that materially affect time-to-production for new programs.
Regulation and safety — immediate and medium-term impacts
Regulatory updates are accelerating engineering requirements. New emission and safety standards demand tighter fuel management and robust sensor performance to support combustion optimization, on-board diagnostics, and crashworthiness. Compliance timelines are compressing program development windows; teams that align sensor development with regulatory verification early in 2026 will avoid late-stage rework and cost overruns.
Strategic playbook for 2026
For executives building plans in 2026, PW Consulting recommends a three-track strategy:
-
Defend core revenue while funding pivot initiatives: Protect ICE and hybrid sales through improved cost-to-serve and reliability programs, while allocating a portion of R&D to sensing capabilities that are transferable to broader vehicle sensing and fluid-property detection markets.
-
Supply-chain hardening and supplier diversification: Implement a tiered sourcing model for critical ICs and validate alternate sensor chemistries or suppliers. Use our supplier continuity scoring tool (included in the full report) to prioritize dual-sourcing where program risk is highest.
-
Selective inorganic and partnership plays: Target bolt-on acquisitions that close capability gaps (e.g., non-contact sensing IP, software-based compensation, fluid-property analytics) and pursue strategic JDAs with OEMs to secure platform access early in development cycles.
Use-cases and buyer guidance
The report provides tailored guidance for three archetypal buyers:
-
OEMs: Use the report to validate supplier roadmaps against platform lifecycles, calibrate DFM/DFT requirements, and quantify trade-offs between module-level integration and component supplier flexibility.
-
Tier-1 suppliers: Identify white-space where sensor specialization can be leveraged into module supply, and use our margin-sensitivity analyses to negotiate program economics.
-
Investors and M&A teams: Deploy our scenario valuations and supplier scorecards to prioritize targets that offer cross-market IP or defensible OEM relationships.
FAQ — concise answers to the pressing operational questions
-
How material is electrification to fuel level sensor demand? Electrification reduces some volume categories, but a transition tail and diversified fuel-system applications mean demand persists for several product cycles. Planning should assume gradual attrition rather than abrupt obsolescence.
-
What are the immediate supply risks to address in 2026? Semiconductor lead-time volatility and qualification timelines remain the primary constraints. Early engagement with IC suppliers and validation of alternate silicon footprints are practical mitigations.
-
Do safety and emission regulations change technical requirements? Yes — recent standards increase the precision and resilience required of level sensing and diagnostics, and crashworthiness mandates require integrated validation workflows during module design.
How to access the full intelligence
This article is a preview of PW Consulting’s full Worldwide Automotive Fuel Level Sensor Market report. The comprehensive study contains the granular segmentation, supplier-program matrices, pricing and margin benchmarks, and downloadable tools (sensitivity model, supplier continuity scorecard, and program-timing gantt charts) that executives and procurement teams need to operationalize a 2026 plan.
To obtain the full report and supporting datasets, please visit PW Consulting’s report page or contact our industry team for a briefing. The data-driven intelligence we provide is tailored to convert uncertainty into a prioritized set of actions — enabling leaders to make decisive, defensible moves as the automotive ecosystem continues to evolve.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Fuel Level Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com