

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Metal Fabrication Outsourcing Services Market Set to Expand at a 5.29% CAGR During 2026–2032

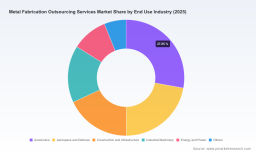
Worldwide Metal Fabrication Outsourcing Services Market — Strategic Outlook for 2026
Executive summary
The Worldwide Metal Fabrication Outsourcing Services market is entering a pivotal phase. Our latest PW Consulting market study benchmarks the industry at an estimated USD 84,052.0 Million in 2025 and projects expansion to approximately USD 120,655.4 Million by 2032, supported by a compounded annual growth rate (CAGR) of 5.29% over the 2026–2032 forecast window. This growth is being driven by a combination of reshoring trends, demand for prefabrication in infrastructure and industrial projects, digitization of quoting and manufacturing workflows, and continued adoption of automation to offset skilled labor shortages.
Worldwide Metal Fabrication Outsourcing Services Market
This release outlines the strategic implications of those findings for corporate decision‑makers preparing plans for 2026. It intentionally showcases the report’s analytical depth and practical value while withholding granular sub‑segment figures to encourage direct engagement with the source report for procurement- and investment‑grade datasets.
Worldwide Metal Fabrication Outsourcing Services Market
Why this report matters for 2026 decision-making
- Investment prioritization: our forecast and scenario analysis converts market momentum into actionable CAPEX and capability roadmaps for operations, automation, and digital procurement.
- Sourcing strategy: the study clarifies when to insource critical metalwork versus when to leverage specialist outsourcing partners to accelerate time‑to‑market and control working capital.
- M&A and partnerships: forward-looking synergy maps and value-capture templates identify acquisition targets and JV structures that close capability gaps quickly.
- Commercial negotiation: TCO models and contract playbooks in the report translate macro pressures into practical commercial levers — indexation, pass‑through clauses, lead‑time guarantees, and warranty structures.
Market dynamics shaping 2026 strategy
Several contemporaneous forces are shaping demand, pricing, and the competitive equilibrium in metal fabrication outsourcing. Our analysis synthesizes raw material trends, labor market realities, regulatory drivers, and macro supply‑chain shifts to provide a comprehensive view of near‑term risk and opportunity.
Worldwide Metal Fabrication Outsourcing Services Market
- Material price volatility and input cost dynamics: steel benchmark prices remain a central operational factor — for context, the global steel benchmark was reported at 3,154 CNY/T as of April 30, 2026. At the same time, upstream commodity dynamics show iron ore easing from previously elevated levels and metallurgical coal prices moderating. These movements create a mixed picture: margin pressure persists in the short term for low‑mix, high‑volume work, while stable or declining iron ore/coal inputs can improve profitability for vertically integrated producers over the medium term.
- Labor scarcity and automation adoption: persistent shortages of skilled welders and fabricators are pushing both buyers and suppliers toward targeted automation — robotic welding cells, automated bending and cutting lines, and AI‑augmented quality inspection. Our fieldwork finds that automation investments are increasingly evaluated not only on unit cost reduction but on resilience, quality consistency, and labor retention metrics.
- Regulatory and ESG drivers: energy transition imperatives and decarbonization commitments are redirecting investment toward prefabrication, lightweighting, and process electrification. Meanwhile, digitalization is catalyzing M&A activity as traditional fabricators acquire software and digital quoting capabilities to remain competitive.
- Supply‑chain strategy: reshoring and diversification: geopolitical dynamics and tariff uncertainty continue to influence sourcing choices. Firms are increasingly balancing cost with strategic resilience, leading to multi‑sourcing strategies and greater use of regional outsourcing hubs.
- Market structure: the sector remains fragmented, with the top three and top five players accounting for a relatively small share of global revenue, underscoring abundant opportunities for consolidation, regional champions, and specialist niche players.
Competitive landscape — how the leading profiles are evolving
The report provides an actionable competitor matrix that assesses scale, service breadth, specialization, digital maturity, and go‑to‑market models. High-level strategic archetypes emerging from our vendor analysis include global diversified integrators, heavy‑structure specialists, precision and rapid‑turn providers, and digital marketplaces. Illustrative positioning follows:
- Global diversified integrators (scale and integration): Established industrial players with broad metalworking footprints are leveraging vertical integration and scale to supply infrastructure and heavy equipment applications. Their competitive edge is in large‑volume, long‑cycle contracts and the ability to internalize steel processing and fabrication.
- Heavy‑structure and engineering specialists: These firms focus on large welded structures, heavy machining, and complex assemblies for construction, mining, and industrial equipment. They compete on engineering capability, project management, and the ability to execute oversized and technically demanding scopes.
- Precision and rapid‑turn specialists: A distinct cohort markets speed and agility — digital quoting, quick-turn sheet metal, and low‑volume CNC work — serving prototyping, aftermarket, and high‑variety manufacturing needs.
- Marketplace and platform models: Digital marketplaces aggregate capacity across regional suppliers, providing buyers with rapid price discovery, diversified sourcing, and shorter procurement cycles — a disruptive model especially for low‑to‑mid complexity assemblies.
Company‑level observations from our competitive review:
- Mid‑sized specialists that combine design and prototyping with light gauge fabrication are winning share in electronics enclosures and industrial components by shortening development cycles.
- Heavy fabrication incumbents are defending margins through scale, integration into steel supply chains, and long‑term OEM partnerships in construction and energy sectors.
- Marketplaces and digital manufacturers are expanding service portfolios (rapid prototyping to low‑volume production) and are increasingly referenced in buyer RFPs for flexibility and speed.
- Recent corporate activity — including capability expansions via acquisition — evidences a competitive trend: established fabricators are buying design, digital quoting, or light‑gauge capabilities to broaden addressable markets and capture higher‑margin product engineering work. (For example, a capability expansion announced in late 2025 by a U.S. fabrication specialist illustrates this approach.)
What’s in the PW Consulting report — practical content for immediate action
This study is structured as an operational playbook as much as a market forecast. The deliverables were designed with procurement, operations, corporate development, and engineering leaders in mind, and include:
- Composite market forecasts and scenario analyses (base, downside, and upside) through 2032, with sensitivity to steel and alloy cost paths and reshoring assumptions.
- A regional and service‑type segmentation framework with supplier counts, capacity indicators, and risk heatmaps (note: detailed sub‑segment financials are reserved for the full report).
- Supplier scorecards and due‑diligence checklists covering capacity, certifications, quality systems, environmental performance, and digitization maturity.
- TCO and supplier comparison models incorporating material pass‑through clauses, lead‑time risk premia, and automation amortization schedules.
- Practical contract templates and negotiation playbooks, including clauses for indexation, force majeure, and quality dispute resolution.
- Automation and digitalization ROI calculators: welding robotics, CNC cell deployment, and online quoting platforms.
- M&A readiness and integration blueprints tailored to buyers seeking capability expansion in prefabrication and digital manufacturing.
Strategic recommendations for 2026
- Prioritize supplier partners that can demonstrate both digital quoting and automation maturity; speed and predictable lead times will be decisive in procurement negotiations.
- Run targeted automation pilots in high‑touch welding and finishing cells to quantify labor substitution, quality improvement, and lead‑time gains; use pilot results to build a five‑year automation roadmap.
- Reassess the make‑vs‑buy decision across product families using the report’s TCO models — particularly for assemblies where design‑for‑manufacturability can materially lower lifecycle costs.
- Pursue diversification of supplier footprints to manage geopolitical and tariff risk, but balance this with supplier consolidation where scale unlocks better material sourcing and process standardization.
- Embed raw material hedging and indexation clauses into multi‑year supply contracts to reduce margin volatility, and align pass‑through mechanisms with key customers where appropriate.
- Use digital marketplaces strategically for prototyping and low‑volume work while reserving strategic, high‑complexity assemblies for vetted specialty partners or captive production.
- Consider M&A or JVs to acquire prefabrication and light‑gauge capabilities rapidly; integration templates in the report reduce execution risk for buyers.
How to use this study
Leaders can apply the report as a decision support system across three main use cases: procurement optimization (short‑term contracting and supplier rationalization), operations planning (automation investments and capacity planning), and strategic corporate development (M&A, partnerships, and geographic expansion). Each use case is supported by downloadable tools, templates, and sensitivity models.
Next steps — where to get the full dataset
This press release highlights strategic takeaways and the practical value of PW Consulting’s Worldwide Metal Fabrication Outsourcing Services market research. Detailed sub‑segment numbers, regional breakouts, supplier‑level revenue estimates, and downloadable TCO calculators are contained exclusively in the full report. Those proprietary datasets and the accompanying Excel models are essential for transaction diligence, supplier negotiations, and capital budgeting.
To access the full report, datasets, and the suite of operational tools referenced above, please visit the PW Consulting report page. The full deliverable provides the granular insights necessary to convert the high‑level strategies outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fabrication Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com