

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Umbilical Cable Market to Reach USD 6,768.18 Million by 2032, Growing at a 7.1% CAGR

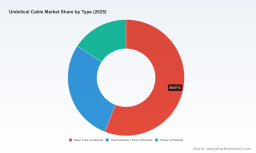
Worldwide Umbilical Cable Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As energy portfolios and subsea infrastructure projects accelerate across regions, umbilical cable systems remain a mission‑critical enabler for offshore production, power export, and emerging renewable arrays. PW Consulting’s new Worldwide Umbilical Cable Market report (base year 2025; historical: 2020–2025; forecast: 2026–2032) provides the executive-level, decision‑ready intelligence that procurement, engineering, and corporate development teams must use to shape capital allocation and partner selection in 2026.
Worldwide Umbilical Cable Market
Executive summary — what the market picture means for 2026 decisions
The global umbilical cable market has moved from a cyclical trough into a sustained growth phase. Aggregate market revenues expanded from approximately USD 3.15 billion in 2020 to about USD 4.19 billion in 2025, and our model forecasts continued expansion through the 2026–2032 horizon, reaching nearly USD 6.77 billion by 2032. The forecast period is underpinned by a compound annual growth rate (CAGR) of 7.1% (2026–2032).
Worldwide Umbilical Cable Market
For 2026 corporate planning cycles, three implications are immediate and actionable:
Worldwide Umbilical Cable Market
- Capital allocation should reflect a structurally larger market and longer project lifecycles—project pipelines justify earlier procurement engagement and longer lead‑time contracts.
- Supply‑chain resilience is a strategic priority—raw material supply (notably high‑grade stainless and super‑duplex tubes) and manufacturing capacity are the pinch points that will determine schedule risk and margin volatility.
- Vendor strategy must balance scale and specialization—market concentration suggests dominant suppliers will continue to influence pricing and technical roadmaps; yet niche and regional specialists will be critical for bespoke and near‑field projects.
Market trajectory and underlying dynamics
Our historical analysis shows recovery and reinvestment across subsea developments since 2021, with a sharper acceleration in contract activity and order books by 2024–2025. The forecast to 2032 incorporates ongoing deepwater/ultra‑deepwater project awards, electrification of subsea infrastructure, and the expansion of offshore renewable export arrays that require bespoke umbilical architectures.
Key demand drivers incorporated in our scenario work include:
- Scale and depth complexity of hydrocarbon developments that require longer, higher‑specification umbilicals for control, chemical injection, and power delivery.
- Growth in offshore wind and floating arrays, which create adjacent opportunities for dynamic electrical and hybrid export cables and support umbilical‑like systems for floating substation control.
- Regulatory emphasis on safety and lifecycle performance, pushing operators to prioritize higher‑specification materials and full‑lifecycle assurance contracts.
On the supply side, our analysis highlights ongoing investment in R&D and manufacturing capacity changes to accommodate longer lengths and specialized constructions. A spike in orders for umbilical tubing and associated components in early 2026 illustrates persistent demand for high‑spec materials.
Competition and concentration — what buyers must know
The marketplace is meaningfully concentrated: our competitive concentration metrics indicate that the top three suppliers capture a majority share of industry revenue, while the top five capture well over three‑quarters. This structure creates both opportunities and risks for buyers and investors:
- Opportunity: scale players offer integrated SURF (subsea, umbilicals, risers, and flowlines) solutions, global delivery footprints, and advanced engineering capabilities that reduce integration risk on large, complex projects.
- Risk: dependence on a narrow set of large vendors increases exposure to pricing power, lead‑time constraints, and strategic prioritization of larger clients—smaller operators and EPCs can face deferred deliveries or premium pricing when capacity tightens.
Profiles of core players in our vendor matrix (publicly available information and primary interviews) indicate distinct value propositions:
- TechnipFMC — world leader in engineered steel‑tube and hybrid umbilicals with global manufacturing and integrated subsea capabilities; strong in complex, bespoke umbilicals for deep and harsh environments.
- Oceaneering — deep experience in complete umbilical solutions and a diversified portfolio that includes ROV, renewable array cabling, and IWOCS (intervention) services; attractive for projects requiring strong installation and subsea service support.
- OneSubsea (SLB) — leverages patented designs and integrated production umbilicals with strong credentials in ultra‑deepwater, flow assurance, and multiphase control applications.
- Prysmian Group, JDR, and regional specialists — established cable technology and full‑lifecycle service capabilities; attractive partners for electrical power and hybrid systems as well as for long tie‑backs.
- Smaller/bespoke specialists (e.g., Fibron BX, Umbilicals International, APAR, Tratos/MFX) — offer flexibility, rapid customization, and niche manufacturing capacity that can be decisive for fast‑turn or highly specialized projects.
- Component and tube suppliers (e.g., Tubacex) — critical upstream players whose order books and capacity expansions signal medium‑term supply availability for steel tube umbilicals.
Recent market intel underscores these dynamics: major tube orders reported in early 2026, specialized testing contracts for pre‑deployment and lay‑operations in 2025, and industry conferences in 2025 that highlighted standards, testing, and lifecycle assurance—all confirming active capital deployment and intensified vendor competition.
Supply chain, raw materials and risk management
Steel and super‑duplex tubing remain the technical backbone of high‑pressure, high‑tensile steel‑tube umbilicals. Our procurement risk matrix elevates raw material availability, quality certification cycles, and fabrication capacity as the top three supply‑side risks. Tubing order wins documented in early 2026 are an early warning signal that lead times for high‑spec seamless tubes will be a negotiating lever for buyers in 2026.
Recommended mitigation actions for 2026:
- Lock in conditional purchase agreements (CPAs) for critical long‑lead items to protect schedules while preserving price flexibility.
- Qualify secondary and regional suppliers to diversify risk, especially for projects with geographic or regulatory constraints that favor local content.
- Invest in joint R&D or co‑supply agreements with tube and cable manufacturers to secure preferential capacity and alignment on technical specifications.
Practical content in the full report — what you’ll get
The PW Consulting report translates market projections into a toolkit for action. Highlights include:
- Detailed market sizing and scenario forecasts (2026–2032) with sensitivity analysis to commodity and capex cycles.
- Vendor benchmarking framework covering technical capability, manufacturing footprint, contract performance, and EHS/compliance credentials.
- Procurement playbooks for CAPEX vs OPEX contracting, preferred commercial terms, warranty and testing clauses, and risk allocation templates.
- Supply‑chain heat maps and lead‑time dashboards that identify pinch points by component and region (note: the public brief intentionally withholds granular regional and application splits—these are included in the full report).
- Investment and M&A screen with candidate profiles for bolt‑on acquisitions, forward integration, and joint venture collaboration in renewables and SURF segments.
- Case studies and cost models for typical project types (shallow, deepwater, ultra‑deepwater) showing financial impacts of specification choices and supplier selection.
These operational deliverables are designed to be directly inserted into 2026 project tendering, budgeting, and strategic planning cycles. The report’s annexes include standardized RFP templates, scope checklists for FAT and pre‑lay testing, and contract clause language optimized for long‑delivery critical items.
Strategic recommendations for 2026 — a concise action plan
- Prioritize early supplier engagement: shift from price‑only RFQs to technical‑commercial workshops with shortlisted vendors to de‑risk specification mismatches and secure capacity windows.
- Hedge raw material exposure: consider option arrangements with leading tube suppliers and index‑linked pricing mechanisms tied to stainless steel benchmarks.
- Adopt a dual‑track vendor strategy: secure one strategic global supplier for system integrity and a second, nimble specialist for customization and schedule flexibility.
- Invest in joint testing and performance assurance: co‑funded FAT, extended field trials, and lifecycle monitoring to reduce long‑tail warranty exposure and total cost of ownership.
- Evaluate vertical integration selectively: for large organizations with sustained offshore programs, securing tube supply or inshore manufacturing partnerships can yield margin and schedule advantages.
How PW Consulting’s intelligence will accelerate your 2026 decisions
This report is intended for C‑Suite decision makers, procurement leads, EPCI contractors, and corporate development teams preparing 2026 budgets and 2027–2028 execution plans. It combines rigorous market forecasting with actionable procurement and technical guidance so that teams can:
- Convert macro forecasts into quantifiable project budget contingencies;
- Design vendor selection processes that reduce schedule risk and lifecycle cost;
- Identify M&A or partnership targets for capabilities in high‑growth segments such as hybrid and power umbilicals;
- Integrate compliance, testing, and certification planning into procurement timelines to avoid late‑stage rework.
Next steps
PW Consulting invites stakeholders to review the full Worldwide Umbilical Cable Market report for the detailed segmentation, regional deployment scenarios, and supplier scorecards that underpin the recommendations summarized here. The public brief intentionally omits granular regional and application share tables to encourage direct engagement with the report, which includes downloadable tools and customizable models for internal use.
For 2026 planning cycles, teams who incorporate the report’s procurement playbooks and risk mitigation measures in Q1 will be best positioned to capture value as the market expands and competition for capacity intensifies.
Methodology and data integrity
The analysis uses a base year of 2025 with historical data covering 2020–2025 and a forward forecast through 2032. Revenue figures are expressed in USD Million. Our methodology combines bottom‑up demand modeling by project type, supplier capacity assessment, and macroeconomic scenarios, cross‑checked against supplier disclosures, industry conference findings, and primary interviews. Concentration metrics and supplier profiles draw from company public filings, press releases, and verified industry sources.
For detailed analysis of this topic, please visit the official page: Worldwide Umbilical Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com