

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Solar Laser Drilling Market to Expand at 13.66% CAGR, Reaching USD 1,696.53 Million by 2032 as Asia Pacific Leads with USD 498.01 Million
By pmarketresearch, 2026-07-15
Worldwide Solar Laser Drilling Market — 2026 Strategic Outlook (PW Consulting)
Executive snapshot
PW Consulting’s latest market study, "Worldwide Solar Laser Drilling Market (Base year: 2025; Forecast: 2026–2032)," synthesizes five years of historical performance (2020–2025) and provides a forward-looking, decision‑grade view for corporate strategy teams. The market showed robust expansion from roughly USD 372.4 million in 2020 to approximately USD 692.5 million in 2025. Under our baseline forecast the market is projected to continue expanding at a compound annual growth rate (CAGR) of 13.66% through 2032, reaching an estimated USD 1,696.5 million by 2032. This trajectory reflects a structural shift in photovoltaic manufacturing toward higher-efficiency cell architectures and module designs that place a premium on precision laser processing.
Worldwide Solar Laser Drilling Market
Why this report matters for 2026 decision cycles
-
Capital allocation precision: As manufacturers plan 2026–2027 capital expenditures, the report translates market dynamics into timing signals for laser equipment procurement vs. retrofit.
Worldwide Solar Laser Drilling Market -
Technology selection: We map laser source technologies to near‑term and medium‑term cell technology roadmaps so engineering leaders can align sensor-to-action decisions with R&D and production targets.
Worldwide Solar Laser Drilling Market -
Vendor and sourcing strategy: The analysis gives supply‑chain managers a fact‑based framework for vendor selection, partnership timing, and contingency planning amid rising module design complexity.
-
M&A and partnership readiness: Corporate development teams get scenario frameworks that identify attractive consolidation targets and partnership archetypes across the laser-to-module value chain.
What the study contains — practical, executable deliverables
-
Transparent market-sizing methodology and reconciled historicals (2020–2025) with forecast scenarios through 2032.
-
Demand-driver decomposition linking cell technology adoption, module architecture changes (including double‑glass trends), and downstream system economics to laser drilling requirements.
-
Technology-by-use-case mapping: comparative performance, throughput, and yield implications for nanosecond, picosecond, and femtosecond processing in solar applications.
-
Actionable CapEx playbooks: stepwise guidance for pilot, scale-up and full production, with an integrated payback and sensitivity model (Excel) that you can apply to your factory templates.
-
Vendor scorecards and negotiation playbooks that align technical KPIs (throughput, mean time between failures, maintenance cost) with commercial terms.
-
Policy and tariff scenario analysis with decision trees quantifying order‑book timing risk under alternative trade regimes.
-
Supply‑chain heatmap and risk mitigation checklist focused on critical subcomponents and service footprints for global manufacturing footprints.
Macro and adoption signals to watch in 2026
-
Post‑pandemic capacity rebalancing has given way to strategic investment—but not uniformly. Our interviews and order‑intake tracking indicate pockets of investment caution tied to policy uncertainty and technology transitions.
-
Double‑glass module adoption and cell architecture upgrades continue to push demand for high‑precision glass drilling and back‑side processing. This is a recurring demand vector that will support growth independent of short‑term tariff noise.
-
The market’s concentration profile (CR3 ≈ 42.5%; CR5 ≈ 58.2%) signals a moderately consolidated supplier environment where top vendors command material share while a set of specialized suppliers compete on niche performance dimensions.
-
Technological innovation is accelerating: advances in drilling speed, chipping control, and beam‑delivery systems are compressing unit production costs, but they also raise the bar for incumbent maintenance and upgrade strategies.
Competitive landscape — strategic positioning of key suppliers
-
3D‑Micromac AG (Germany) — Strong in high‑throughput laser micromachining for photovoltaics with product focus on laser contact opening (LCO) and Thermal Laser Separation (TLS) for cell dicing. Their systems are often evaluated where throughput and yield are primary selection criteria.
-
Han’s Laser (China) — A leading supplier of PV glass laser drilling solutions for thin double‑glass modules. Their capabilities are relevant to glass processing specialists and module makers transitioning to heavier double‑glass formats.
-
TRUMPF (Germany) — Major industrial laser systems provider with broad manufacturing credentials; typically selected where integration into large, automated lines and global service coverage are priorities.
-
Coherent Corp. (USA) and IPG Photonics (USA) — Key laser source suppliers with complementary strengths: Coherent in precision sources and system integration; IPG in fiber‑laser power and reliability for high‑throughput applications.
-
Laserax (Canada), Novanta Photonics (USA), SCANLAB (Germany), Rache Corp (USA), Laserod Technologies (USA) — A cohort of specialized providers covering laser cleaning, beam delivery, scanning systems, and ablation techniques. Each is differentiated by focus areas (recycling, scribing, micro‑structuring), and their equipment is often used in targeted optimization projects.
Recent signal events and their strategic implications
-
LPKF’s 2026 earnings and segment commentary noted order intake volatility and highlighted that tariff uncertainty and the perovskite transition are prompting buyers to defer decisions. For strategic planners this underscores the need for decision‑stage models that value optionality and phased investment.
-
BY Photonics’ late‑2025 technology announcement demonstrating sub‑3‑second drilling for thicker PV glass is a reminder that step‑change process improvements can rapidly reset operational benchmarks—pressuring competitors and creating short windows for OEMs to secure differentiated throughput gains.
Five practical strategic recommendations for 2026
-
Adopt a two‑track procurement posture: pilots now, staged rollouts later. Use pilot results to de‑risk full production investments and to validate supplier claims on throughput and yield under your specific cell/module recipes.
-
Align laser technology choices with your cell roadmap, not current production. Different laser classes bring tradeoffs in throughput, edge quality and cost of ownership; ensure your selection supports the cell technologies you plan to scale over the next 3–5 years.
-
Embed tariff and technology scenarios into your procurement contracts. Include clauses for price renegotiation and tech upgrades that reflect the probability of policy shifts or disruptive cell coating adoption.
-
Diversify supplier relationships where service footprint, spare parts availability and regional support are material to uptime. Given the market concentration profile, selective dual‑sourcing is a pragmatic hedge.
-
Monitor upstream module design trends—particularly double‑glass and advanced shingling techniques—because these structural shifts are among the strongest multipliers for laser drilling demand.
Risk scenarios — what could change the outlook
-
Adverse trade policies or protracted tariff uncertainty could delay orders and temporarily compress market growth in 2026–2027.
-
Accelerated perovskite integration would reshape equipment needs, creating both risk and opportunity for laser specialists depending on their ability to adapt processing parameters.
-
Rapid supplier innovation (e.g., dramatic improvements in drilling speed or cost) could shorten product cycles and increase replacement capex requirements for manufacturers that adopted earlier generations.
How corporate teams should use this report in 2026
-
Board and executive teams: use the report’s scenarios and financial models to stress‑test investment proposals and to set realistic timelines for ROIs tied to module price and cell‑efficiency outcomes.
-
Operations and engineering: apply the included throughput and yield models to pilot line specifications; use the vendor scorecards during RFPs to accelerate selection and commissioning.
-
Corporate development and procurement: leverage the M&A playbook and supplier benchmarking to prioritize acquisition targets or strategic supplier partnerships that accelerate capability building.
Next steps — where to get the full intelligence
This release is a strategic preview: it illustrates the direction, scale and decision implications of the solar laser drilling market without disclosing proprietary segment tables and granular regional/application splits that are contained in the full study. The complete report includes downloadable Excel models, detailed regional and application segmentation, vendor financials and contract negotiation templates designed to be used directly in board decks and CapEx proposals. For organizations evaluating manufacturing investments or supplier strategies in 2026, the full dataset and scenario models are essential to convert market insight into executable plans.
PW Consulting invites decision‑makers to review the full report and the associated toolkit to accelerate time‑to‑decision and reduce deployment risk. Contact PW Consulting to request access to the complete analysis and the embedded modeling assets.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global Medical Microscopic Hemostatic Clip Market Poised for 7.2% CAGR in 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Medical Microscopic Hemostatic Clip Market — Strategic Outlook for 2026 Decision-Makers
As healthcare providers accelerate minimally invasive and microsurgical procedures, the market for microscopic hemostatic clips is entering a phase of sustained, measurable expansion. PW Consulting’s latest research — based on a 2025 base year and a detailed historical review from 2020–2025 — projects continued growth through a seven-year forecast window (2026–2032). Our model indicates a compound annual growth rate (CAGR) of 7.2% in the forecast period, with the global market expanding materially from the 2025 baseline to a substantially larger market by 2032. For executives planning capital allocation, product development, distribution partnerships, or M&A activity in 2026, this study translates macro momentum into concrete, actionable guidance.
Worldwide Medical Microscopic Hemostatic Clip Market
Why this matters for 2026 planning
- Predictability: A mid-single-digit-plus CAGR provides a stable long-term growth envelope for investment prioritization across R&D, manufacturing scale-up, and commercial expansion.
- Timing: 2026 will be a pivotal year for companies that want to secure distribution channels and regulatory positioning before adoption curves steepen in key procedure areas.
- Value capture: As product innovation (e.g., rotation, one-step deployment, repositionability, and automated appliers) reshapes clinical workflows, first-mover advantages can translate into durable share gains in a moderately concentrated market.
Market trajectory — the headline figures
PW Consulting’s market architecture places 2025 as the analytical base year. From that baseline, our scenario analysis and deterministic forecast produce a clear growth pathway to 2032 underpinned by a 7.2% CAGR for the forecast period (2026–2032). The trajectory reflects a combination of rising procedural volumes in endoscopy and laparoscopy, device innovation that lowers procedural time and expands indications, and a regulatory/reimbursement environment that increasingly facilitates outpatient and ambulatory adoption.
Worldwide Medical Microscopic Hemostatic Clip Market
Key dynamics shaping demand
- Clinical workflow innovation: New clip designs and delivery systems that enable 360° rotation, one-step deployment, and repositionability are reducing procedure time and improving closure reliability in GI endoscopy and select microsurgical interventions.
- Device-format debate: The market is evolving along a disposables-versus-reusable axis. Single-use, preloaded appliers simplify logistics but increase unit cost; reusable appliers reduce per-procedure cost but demand sterilization and lifecycle management — commercial strategies must reconcile clinical preference with institutional procurement priorities.
- Regulatory clarity and reimbursements: Titanium hemostatic microclips fall under established regulatory frameworks (Class II implantable clips under 21 CFR 878.4300 in the U.S., product code FZP) and increasingly explicit reimbursement pathways in outpatient settings. These factors lower adoption friction for next-generation clips that meet GMP and labeling standards.
- Material and manufacturing constraints: Titanium Grade 1 is the material standard due to its biocompatibility, malleability, MRI compatibility, and radiolucency. This creates both a supply-chain dependency and a high bar for manufacturing quality control, favoring established suppliers with precision metalworking and sterilization capabilities.
Competitive landscape — tactical takeaways
The market exhibits meaningful concentration among a small group of specialized players and surgical-instrument incumbents. Our competitive assessment synthesizes product-level differentiation, regulatory position, route-to-market, and recent strategic moves:
Worldwide Medical Microscopic Hemostatic Clip Market
- Synovis Micro Companies Alliance (Baxter): Historically positioned in microsurgical vessel control with titanium microclips and precision appliers. The 2025 FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier (preloaded with multiple titanium microclips) signals a push into automated delivery systems that reduce manual dexterity requirements in the OR.
- Established European microsurgical instrument specialists (e.g., Peter Lazic GmbH and S&T Microsurgical Instruments): These firms emphasize premium instruments, surgical craft, and regulatory compliance (ISO 13485 / CE pathways). Their strength is deep clinical trust and bespoke product lines for neurosurgery and microsurgery.
- U.S. surgical instrument manufacturers (e.g., Scanlan, Kapp Surgical): These players leverage custom instrument manufacturing and broad distribution relationships in acute care settings, offering complementary clamp and small-vessel control products that integrate with clip strategies.
- Innovative device entrants (e.g., Amsel Medical): Product differentiation around mechanical occlusion technologies (e.g., iDOT) highlights non-metallic or hybrid approaches that can compete on unique clinical use-cases and regulatory positioning.
- Active smaller providers and distributors (MicroSurgical Technology and others): These companies extend selection, supply-chain flexibility, and niche clinical solutions.
Recent market activity underscores the competitive momentum: Olympus launched a single-use, 360°-rotatable hemostasis clip in 2025, while the 2026 agreement giving Micro-Tech Endoscopy global distribution rights to a repositionable clip line illustrates acquisitive distribution strategies. These moves emphasize two sustained themes—product innovation and distribution consolidation.
Concentration and competitive implications
Market concentration metrics demonstrate that the top tiers of the industry command a majority share. This oligopolistic footprint produces both risk and opportunity: high barriers to entry for full-scale manufacturing and regulatory compliance, yet attractive acquisition targets for companies seeking rapid access to product lines or geographic reach. For 2026, disciplined M&A or licensing to secure differentiated clip technologies or rapid distribution pathways is likely to deliver asymmetric returns relative to greenfield investment.
Regulatory, reimbursement, and standards landscape
- Regulatory: Titanium microclips are regulated within established Class II pathways in major markets; compliance with GMP, labeling, and performance claims is non-negotiable. CE marking and ISO 13485 certification remain essential for European market access.
- Reimbursement: The availability of outpatient coding for defect closure procedures enhances the commercial case for disposable and repositionable clip systems by improving revenue capture in ambulatory settings.
- Standards and materials: Titanium Grade 1 is the accepted material standard; procurement strategies must account for traceability, annealing processes, and vendor qualification to meet implantation and imaging-compatibility requirements.
Practical, decision-oriented deliverables in the PW Consulting report
We structured this study to be a direct input into 2026 strategic planning cycles. The deliverables emphasize actionability over academic breadth and include:
- Proprietary market-sizing and forecast model (2020–2032) with scenario toggles for pricing, procedure volumes, and reimbursement uptake.
- Regulatory and reimbursement playbook with jurisdictional checklists and timelines for 510(k)/CE submissions and outpatient coding strategies.
- Competitive benchmarking templates that map product features (rotation, deployability, repositionability, applier automation), regulatory clearances, and likely pricing tiers.
- Manufacturing and supply-chain risk assessment, including raw-material sourcing maps for titanium and capacity stress-tests under demand surge scenarios.
- Commercial go-to-market frameworks for direct sales, distributor partnerships, and hospital system procurement negotiations, with specific modules for ambulatory surgery centers and integrated health networks.
- M&A and partnership screening tool that identifies acquisition targets by strategic fit and valuation sensitivity under varying growth scenarios.
Strategic recommendations for 2026
- Prioritize modular product platforms: Invest in applier architectures that accept multiple clip sizes and enable features such as 360° rotation and repositionability—these features are becoming clinical table stakes.
- Lock distribution early: Seek exclusive or semi-exclusive distribution agreements in priority markets as a defensive play against rapid consolidators.
- De-risk manufacturing: Certify secondary suppliers for precision titanium components and plan sterilization capacity to avoid scale-up bottlenecks.
- Use regulatory timing as a moat: Pipeline clearance and CE timelines should be staged to create rolling product introductions rather than one-time launches, sustaining commercial conversation across buying cycles.
- Target outpatient adoption: Align product pricing and value messaging to ambulatory and endoscopic settings where procedure shift and reimbursement codes can accelerate uptake.
How to use this report in your 2026 planning
For executive teams, the report functions as both a diagnostic and prescriptive tool. Use the market model to stress-test capital allocation scenarios and the go-to-market playbooks to define pilot geographies for new clip launches. Development teams should integrate the competitive benchmarking into product roadmaps, while corporate development groups should use the M&A screening to prepare for opportunistic consolidation. Clinical affairs teams will find the regulatory and reimbursement matrices particularly valuable for sequencing trials, claims, and payer engagement.
Conclusion — a data-driven but deliberately selective view
PW Consulting’s analysis shows a market that is growing at an attractive, investable pace with defined winners and clear entry barriers. The report provides the analytical backbone to develop differentiated strategies for product innovation, scale economics, and channel expansion in 2026. In keeping with our “trailer” approach, this briefing surfaces the structural insights and the tactical levers that matter most while reserving the granular regional, application, and segmentation datasets for the full report — the precise, downloadable intelligence you will need to translate strategy into action.
To obtain the full dataset, detailed segmentation, and the interactive forecast model that support these conclusions, visit the PW Consulting report page or contact our client services team to request access to the Worldwide Medical Microscopic Hemostatic Clip Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Microscopic Hemostatic Clip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Biodegradable Disposable Foodservice Market Hits USD 11.95 Billion in 2025, Signaling Strong Growth Ahead
By pmarketresearch, 2026-07-15
Worldwide Biodegradable Disposable Foodservice Market: Strategic Outlook for 2026 Decision-Making
PW Consulting's latest market study on the Worldwide Biodegradable Disposable Foodservice Market crystallizes why 2026 is a hinge year for manufacturers, foodservice operators, retailers, and investors. The sector—driven by regulatory pressure, corporate sustainability commitments, and shifting procurement economics—has matured from niche experimentation into a mainstream procurement category. Our report, based on 2020–2025 historical analysis and a 2026–2032 forecast, quantifies that transition: the market reached approximately USD 11,951.6 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.02% across the forecast window, passing the USD 20.5 Billion milestone by 2032. The market remains fragmented—our concentration analysis shows a CR3 near 18.5% and a CR5 around 26.8%—creating spaces for scale play, regional champions, and vertical integration.
Worldwide Biodegradable Disposable Foodservice Market
Why this report matters for 2026 corporate strategy
-
Timing: 2026 is the first full year many new regulatory measures and public procurement rules take effect in major markets. Companies that align product portfolios, supply chains, and compliance frameworks now will avoid costly last-minute transitions.
Worldwide Biodegradable Disposable Foodservice Market -
Clarity: With a clear growth trajectory and quantifiable market sizing, firms can move beyond aspirational ESG statements to concrete commercial plans—capital allocation, plant footprints, and procurement contracts—that reflect real demand curves.
Worldwide Biodegradable Disposable Foodservice Market -
Actionability: The report blends top-line forecasting with playbooks for pricing, material sourcing, composting compatibility, and retailer/foodservice contracting—turning market intelligence into executable steps for 2026.
What the PW Consulting report contains (operational depth)
-
Comprehensive market sizing and trend maps: validated historicals (2020–2025) and a granular forecast (2026–2032) with scenario analysis reflecting regulation-driven and baseline adoption paths.
-
Segment and material framework: a disciplined taxonomy across materials (paperboard, PLA, bagasse, starch blends, wood & bamboo) and product formats (plates, cups, containers, cutlery, straws). Note: to preserve strategic value we summarize dynamics without publishing every subsegment’s raw figures in this release.
-
Supply-chain and raw-material economics: step-by-step cost modeling for feedstocks (including agricultural residues like bagasse), sensitivity analysis to commodity swings, and logistics-led margin implications for regional production hubs.
-
Regulatory and compostability mapping: jurisdiction-by-jurisdiction compliance implications, operational thresholds for industrial vs. home compostability, and the interplay with Extended Producer Responsibility frameworks.
-
Commercial go-to-market modules: contracting templates, pricing strategies for mix shifts, private-label vs. branded options, and a retailer/foodservice scorecard to prioritize channel efforts.
-
Competitive intelligence and M&A playbook: validated company profiles, capability matrices, partnership archetypes, and valuation levers for buy-build-partner decisions.
-
Risk matrix and contingency planning: supply disruption scenarios, regulatory downside cases (e.g., tighter compostability tests), and mitigation measures such as dual-sourcing and co-packing arrangements.
Market dynamics shaping 2026 decisions
-
Regulatory acceleration: The EU’s Packaging and Packaging Waste Regulation (PPWR) coming into force creates harmonized design-for-recycling mandates that ripple across supply chains. Several U.S. states are implementing Extended Producer Responsibility (EPR) laws with provisions that affect compostable formats. Additionally, national bans—such as the UAE’s announced 2026 restriction on a broad set of single-use plastics—are compressing timelines for portfolio transitions.
-
Standards and composting definitions: Recent policy moves (including a notable decision by a U.S. standards body in early 2026 regarding synthetic polymers in organic compost) are tightening end-of-life definitions, raising the bar for certification and labeling. Manufacturers must now be equally fluent in product performance and in waste-system compatibility.
-
Raw-material advantage: Agricultural residues—most notably sugarcane bagasse—have become a practical, technical, and commercial mainstay for compostable tableware. Their abundance, favorable mechanical properties, and consumer acceptance render them a default feedstock in many value chains.
-
Channel transformation: Foodservice operators and major retailers are consolidating procurement, favoring suppliers who can guarantee compliance across multiple jurisdictions and provide traceability, cost predictability, and circularity reporting.
Competitive landscape — strategic profiles and implications
The market’s low concentration score signals opportunity: regional leaders and focused innovators can capture meaningful niches before global consolidation accelerates. Below are strategic takeaways on major incumbents and challengers included in our competitive analysis.
-
Huhtamaki Oyj (Espoo, Finland): A global platform with deep molded-fiber and paper-based capabilities. Strengths include scale and wide distribution; recent product launches show a pragmatic approach to reducing polymer content while maintaining performance. Strategic implication: scale investments for higher-value compostable formats and partnerships with waste-management players to guarantee end-of-life claims.
-
Vegware (Edinburgh, UK): A plant-based specialist with a strong proposition in PLA and bagasse formats. Advantageous in markets that prioritize renewable feedstocks and certification transparency. Strategic implication: pursue modular manufacturing partnerships in high-growth APAC and North American urban centers to reduce logistics emissions and lead times.
-
Eco-Products (Novolex, USA): Certified compostable product range with strong foodservice connections. Positioning benefits from certification pedigree—an important commercial differentiator as composting infrastructure matures. Strategic implication: extend service offers (e.g., collection/logistics) to lock in large institutional clients.
-
World Centric (California, USA): Niche focus on commercial composting compatibility. Reinforce commercial partnerships with composters and large-scale foodservice operators where industrial composting exists as a mature channel.
-
Asia-based producers (Bioleader, Luzhou Pack/OASIS, GreenGood): Competitive cost structures and technical capabilities in bagasse and molded pulp. Their rapid capacity expansion and export orientation make them attractive partners or acquisition targets for branded Western players seeking margin recovery.
-
Regional specialists (Biopac UK, Green Wave International, AMS Compostable, Sabert, Genpak): These firms demonstrate how regional compliance expertise and tailored product ranges can outperform global competitors in complex regulatory environments.
Recent market moves to watch
-
Strategic alliances and channel plays: In 2025 a European strategic alliance between a molded-fiber specialist and a major retailer demonstrated the power of co-developed, plastic-free SKUs to accelerate retail rollouts.
-
Product innovation: Several 2025–2026 product launches—ranging from low-plastic ice-cream cups to coffee cups designed to lower lifecycle impacts—illustrate that incremental material engineering remains a path to differentiation.
-
Market expansion: Regional players have been expanding into North America and other high-volume markets through incubator and distributor programs, signaling the next wave of competitive intensity.
Strategic recommendations for 2026 (executive checklist)
-
Manufacturers: Prioritize modular capacity investments that allow shifting between bagasse, paperboard, and starch blends; formalize certification roadmaps and integrate product-service bundles (e.g., take-back, compost collection) to support claims.
-
Foodservice operators & retailers: Consolidate suppliers around compliance, traceability, and total-cost-of-ownership rather than unit price alone. Pilot regionally tailored composting partnerships before rolling out nationally.
-
Raw-material suppliers: Secure offtake with long-term contracts tied to sustainability KPIs; invest in pre-treatment and standardization capabilities to meet industrial processing requirements.
-
Investors & M&A teams: Target companies with strong channel lock-ins (institutional contracts, retail programs), technical IP around coatings and compostability, or regional production footprints that address rising logistics costs. Valuations should price in near-term regulatory tailwinds but also account for potential standard harmonization risks.
-
Policy & compliance officers: Monitor EPR rollouts and compostability standard revisions closely; use scenario planning to quantify compliance costs and design-for-recycling trade-offs.
Conclusion — what leaders must do in 2026
2026 is not a year for passive optimism. The combination of predictable market growth (an 8.02% CAGR across 2026–2032), regulatory inflection points, and evolving waste-management realities requires decisive moves: invest in adaptable manufacturing, lock-in compliant feedstocks, and build integrated service propositions that guarantee end-of-life outcomes. The market’s fragmentation offers opportunities for focused scale, but first-mover advantages will accrue to those who align product innovation with regulatory certainty and circular-economy partnerships.
PW Consulting’s full Worldwide Biodegradable Disposable Foodservice Market report provides the granular segmentation, regional forecasts, and proprietary supplier scorecards necessary to convert these strategic implications into boardroom decisions. For executives preparing budgets, M&A teams assessing targets, or procurement leads redesigning supplier panels, the report is the operational intelligence map for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Biodegradable Disposable Foodservice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Facial Rejuvenation Surge — Market to Expand at an 8.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Facial Rejuvenation Market — Strategic Outlook for 2026: A PW Consulting Brief
PW Consulting’s new Worldwide Facial Rejuvenation Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers the market intelligence senior executives need to set winning strategies in 2026. The market, sized at approximately USD 32.5 billion in 2025, is forecast to expand at an 8.5% CAGR through 2032, reaching roughly USD 57.5 billion by the end of the period. This brief summarizes the report’s strategic value, highlights the competitive and regulatory context reshaping the industry, and outlines the pragmatic moves we recommend to translate growth into durable advantage. For full segmentation tables, downloadable models and company-level financials, please visit the PW Consulting release page.
Worldwide Facial Rejuvenation Market
Why this report matters in 2026
-
Decision-ready intelligence: While headline numbers signal robust growth, 2026 is a year of inflection where product innovation, regulatory shifts and channel dynamics converge. Our report maps these forces to practical decisions — product prioritization, training investments, M&A targets and commercial rollouts — with actionable timelines tied to regulatory and reimbursement realities.
Worldwide Facial Rejuvenation Market -
Bridging clinical and commercial agendas: Providers and manufacturers must navigate evidence demands, patient expectations for natural outcomes, and heightened scrutiny of device safety. We translate clinical endpoints into commercial KPIs so R&D and go-to-market teams can move in lockstep.
Worldwide Facial Rejuvenation Market -
Risk-aware growth planning: Concentration metrics indicate the market is guided by a stable set of leading players, yet mid‑market disruption and innovation in energy-based platforms and biostimulators create windows for fast followers and niche specialists. Our scenarios quantify those windows and the triggers that shift them.
What the report contains — practical, field-tested content
-
Comprehensive market sizing and forecast (2020–2032), with an integrated model you can adapt to your internal assumptions and product timelines.
-
Commercial playbooks for each major product class, including launch sequencing, pricing strategies, channel mix optimization and sample P&L impacts under multiple uptake scenarios.
-
Provider segment deep dives (dermatology clinics, medical spas, hospitals and others): decision criteria, purchasing cycles, training needs and clinician adoption barriers.
-
Regulatory and safety roadmaps that link upcoming changes (e.g., recent MoCRA advances and noted FDA safety communications) to compliance milestones and label strategy.
-
Competitive landscape and capability heatmaps covering leading injectables and energy-device firms, distribution partners, and emerging entrants; includes a proprietary M&A target screen and valuation sensitivities.
-
Investment-grade scenario analysis (baseline, accelerated adoption, regulatory tightening) with tactical responses for each scenario.
-
Operational checklists: training & certification playbooks, supply chain continuity plans, and post-market surveillance workflows tailored to aesthetic technologies.
Competitive dynamics — what incumbents and challengers are doing
Market concentration metrics indicate a market led by a set of dominant injectables and device companies, but with meaningful room for technology-led disruption. Global injectables incumbents continue to consolidate scale advantages through distribution networks, clinical training infrastructure and indication expansions, while device specialists compete on platform versatility and consumables economics.
-
Injectables leaders are strengthening clinical evidence and expanding training footprints. Recent openings of advanced training centers and expanded regulatory indications illustrate how leading suppliers convert clinical credibility into wider adoption among high‑volume providers.
-
Device manufacturers are differentiating on platform modularity and multi‑indication capability — investing in software, consumable ecosystems and safety features that shorten learning curves and reduce adverse outcomes.
-
Strategic M&A is an active theme: recent transactions demonstrate buyer appetite to combine novel neuromodulators, resilient filler platforms and complementary skin-health portfolios into vertically integrated offerings that span product, devices and services.
Key players profiled in the report include established injectables providers and device specialists across North America, Europe and Asia Pacific. Our company reviews combine clinical positioning, go‑to‑market execution, R&D pipelines, and near-term catalysts such as facility openings, new approvals, or product launches — analysis that informs competitor response plans and partnership evaluations.
Regulatory and safety environment — implications for strategy
-
Heightened device scrutiny: Regulatory advisories and safety communications published in late 2025 have raised the bar on device-level risk mitigation. Manufacturers should prioritize robust device labeling, user training programs, and evidence demonstrating safe use across diverse skin types and operator skill levels.
-
Cosmetics modernization and facility governance: New regulatory frameworks and portal changes require manufacturers and contract manufacturers to tighten GMP compliance and listing procedures — an operational imperative for anyone scaling production or launching new topical adjuncts.
-
Elective-service reimbursement constraints: With most procedures remaining elective for payers, commercial models must focus on out-of-pocket economics, bundled offerings, and patient financing. Exceptions for medically necessary uses remain important niche plays (e.g., chronic migraine treatments tied to neuromodulators).
-
Local licensing and age restrictions: Emerging national consultations on licensing for non-surgical cosmetic procedures introduce execution risk for rapid expansion strategies that underinvest in local regulatory affairs and practitioner credentialing.
Actionable strategic recommendations for 2026
-
Prioritize portfolio moves by commercial velocity and regulatory risk: Accelerate launches for products with strong clinical differentiation and low regulatory friction; sequence high‑complexity device rollouts to coincide with enhanced training and post-market surveillance capacity.
-
Invest in clinician training as a scalable moat: Establish or partner with certified training centers, digital learning modules and proctoring services to reduce adverse events, accelerate adoption and lock in supplier preference.
-
Design safety-first TCO (total cost of ownership) propositions for devices: Emphasize features that reduce operator error, include mandatory certification, and bundle consumables to create recurring revenue while improving patient outcomes.
-
Leverage evidence for premium positioning: Sponsor head‑to‑head and real‑world studies that demonstrate durability, natural aesthetic outcomes and safety across skin types — materials that directly support payer conversations, clinician adoption and premium pricing.
-
Adopt a disciplined M&A playbook: Target tuck-ins that fill capability gaps (biostimulators, resilient fillers, platform-based energy systems), and apply our deal filter that quantifies revenue synergies, regulatory liabilities and cultural fit in under 45 days.
-
Plan for regulatory scenarios: Build compliance checklists into Q1 2026 roadmaps, including MoCRA registration processes and device risk-mitigation plans to be audit-ready within prescribed timelines.
Scenario planning — three industry paths and the corresponding moves
-
Baseline (most likely): Steady adoption across injectables and energy devices, with incremental regulatory tightening. Actions: scale training, prioritize high-margin SKUs, reinforce supply chain flexibility.
-
Accelerated adoption: Faster uptake driven by new evidence, premiumization and expanded provider capacity. Actions: front-load commercial investment, expand manufacturing capacity, secure exclusive distribution partnerships.
-
Regulatory tightening: Stricter device and provider licensing limits elective access in select markets. Actions: diversify market exposure, enhance remote training and tele-education, and pursue product modifications to meet new requirements.
How executive teams should use this report in 2026
-
Board and C-suite: Use the integrated financial model and scenario outputs to stress-test revenue forecasts, capital allocation and near-term M&A decisions.
-
Commercial leaders: Implement the customer segmentation playbooks and channel strategies to optimize launch sequencing and salesforce focus.
-
R&D and regulatory: Align development roadmaps with the safety and compliance timelines detailed in the regulatory roadmaps to avoid launch delays and labeling risks.
-
Corporate development: Apply the proprietary target-screening criteria to shortlist acquisition or partnership opportunities that deliver immediate scale or technical differentiation.
PW Consulting’s Worldwide Facial Rejuvenation Market report combines market-scale forecasting, competitor intelligence and executional toolkits to convert market growth into sustainable commercial success. While this brief outlines the major currents shaping 2026, the full report includes the granular models, segment-level demand curves, and company financials necessary to act with speed and confidence. Visit our report page to access the complete dataset, customizable models, and a one‑page implementation checklist tailored to your function.
Contact PW Consulting for a tailored briefing; our team is prepared to walk your leadership through the scenarios and provide a bespoke 90‑day action plan designed to capture market share while managing regulatory and clinical risk.
For detailed analysis of this topic, please visit the official page: Worldwide Facial Rejuvenation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
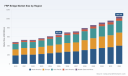
PW Consulting: Worldwide FRP Bridge Market to Expand from USD 651.5 Million in 2025 to USD 1.05 Billion by 2032 (2026–2032 Forecast) at 7.02% CAGR — North America, GFRP and Pedestrian Bridges Lead; Top 5 Capture 51.6%
By pmarketresearch, 2026-07-15
Worldwide FRP Bridge Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest Worldwide FRP Bridge Market report (base year 2025) synthesizes seven years of historical performance and a seven-year forecast to 2032 into a single decision-grade briefing for infrastructure leaders, composite manufacturers, investors, and public agencies. The FRP bridge market has moved from a niche, experimental technology to a commercially viable infrastructure alternative. Our analysis quantifies that trajectory and translates it into the practical choices that will define winners and laggards in 2026 and beyond.
Worldwide FRP Bridge Market
Market Trajectory at a Glance
After an observable recovery and expansion through the early 2020s, total industry revenue reached a new baseline in 2025 (base year). PW Consulting’s forecast shows sustained compound annual growth during the 2026–2032 forecast window, underpinned by durability advantages, accelerating standardization, and new modular product launches that reduce installation time and lifecycle costs. This macro picture provides the foundational context businesses need when allocating capital, sizing production capacity, or prioritizing R&D in 2026.
Worldwide FRP Bridge Market
Why this report matters for 2026 strategy
- Actionable foresight: We translate CAGR-based market trajectories into timing windows for capacity investments, pilot deployments, and go-to-market rollouts.
- Procurement intelligence: Public- and private-sector procurement teams gain a playbook for specifying FRP solutions that balance first-cost, lifecycle maintenance, and resilience requirements.
- Risk-adjusted planning: The report embeds raw-material volatility, evolving regulatory regimes, and consolidation dynamics into scenario-based financial models.
Core dynamics shaping 2026 decisions
Several converging forces are creating a favorable runway for FRP bridge adoption, but they also create operational and commercial tensions that decision-makers must address in 2026.
Worldwide FRP Bridge Market
- Durability economics: Corrosion resistance and low maintenance materially change lifecycle cost comparisons with traditional materials. Agencies focused on total cost of ownership are accelerating pilot deployments and specification updates.
- Standards and specification maturity: Initiatives such as industry-led prototype projects and state-level quality-control programs are removing a primary adoption barrier—confidence in predictable, certifiable performance for public procurement.
- Raw-material dynamics: Glass-fiber markets are tightening amid broader construction demand, creating near-term price pressure that can compress margins for resin-and-fiber-based products unless mitigated with procurement strategies or value-engineering.
- Product innovation and modularization: New designs that emphasize prefabricated modules, rapid installation, and lighter superstructures are shortening project timelines and unlocking opportunities in rehabilitation, remote, and disaster-response use cases.
What the report delivers (practical detail, intentionally selective)
PW Consulting balances depth with proprietary restraint. The published brief below demonstrates the type of intelligence embedded in the full report while intentionally withholding granular segment tables that subscribers receive.
- Market sizing and validated forecasts (historical 2020–2025 and forward to 2032) with scenario overlays and sensitivity to raw-material price shifts and policy changes.
- Supply-chain mapping, including pultrusion capacity, prefabrication node locations, and logistics considerations for long-span vs. short-span solutions.
- Commercial models: tendering strategies, value-based pricing templates, and lifecycle-cost comparison tools for public-works procurement.
- Regulatory and standards playbook: how to engage with state DOTs, test laboratories, and standards bodies to accelerate acceptance and shorten approval cycles.
- Go-to-market and partnership strategies for manufacturers, integrators, and engineering firms seeking scale or market-entry.
- Risk register and mitigation measures specific to 2026: material-price hedging, dual-sourcing strategies, and demonstration project sequencing.
Note: Detailed segmentation by region, fiber type, and application — including the granular numeric splits used for competitive benchmarking — is available only in the full report to preserve the commercial value of that intelligence.
Competitive landscape — structure, players, and implications
The FRP bridge market displays a moderate concentration profile with a mix of established pultruders, specialized bridge fabricators, and nimble modular-system suppliers. Measured concentration metrics indicate meaningful positions for a small group of suppliers, but space remains for regional specialists and innovators targeting niche applications.
Representative companies—each illustrating a distinct route-to-market—include:
- Strongwell Corporation (Bristol, Virginia, USA) — A leader in pultruded FRP structural shapes and integrated systems emphasizing corrosion resistance and lightweight deck/superstructure solutions for both pedestrian and vehicular bridges. Strongwell’s scale and pultrusion expertise position it to compete on standard product lines and large-volume contracts.
- Creative Pultrusions, Inc. (Alum Bank, Pennsylvania, USA) — Specializes in pultruded products and has expanded through acquisitions and platform offerings tailored to pedestrian and trail infrastructure. Their FiberSpan decks and truss solutions reflect a product-led strategy aimed at rapid adoption by trail managers and parks agencies.
- Bedford Reinforced Plastics (Bedford, Pennsylvania, USA) — Focuses on prefabricated pedestrian bridge systems that emphasize speed-of-install and disaster-response capabilities. Recent product guidance and decking options underscore a strategy of addressing urgent infrastructure needs.
- Composite Advantage, LLC (Dayton, Ohio, USA) — Produces FiberSpan decks and components tailored to rehabilitation projects, with a commercial approach targeting fast turnarounds and reduced maintenance burdens.
- CTS Bridges Ltd (United Kingdom) , Fiberline Composites A/S (Denmark) , and FiberCore Europe (Netherlands) — European players emphasizing modular design, pultruded profiles, and holistic bridge systems for traffic and pedestrian applications; their presence highlights differing regulatory contexts and regional engineering practices that suppliers must navigate.
- Lifespan Structures Ltd (UK), Areté Structures (USA), B&B FRP Manufacturing Inc. (USA) — Niche innovators and system integrators delivering prefabricated, truss-based, and square-tube designs for specific span and installation profiles.
Recent corporate and industry developments underscore the market’s momentum: new model launches and decking options from product suppliers; industry projects advancing specification and prototype construction; and targeted guidance on temporary FRP access solutions for disaster response. These moves accelerate buyer familiarity and reduce perceived procurement risk.
Strategic implications and recommended actions for 2026
For suppliers, integrators, and public agencies making near-term decisions, the following actions flow directly from our market view and scenario modeling:
- Adopt a dual approach to scale and specialization: Larger pultruders should secure volume advantages and standardize core product families while carving out specialist teams to support rapid-install and disaster-response offerings.
- Engage early with standards bodies and DOT programs: Active participation in specification development and producer quality-control programs pays off by shortening procurement lead times and improving bid success rates.
- Hedge raw-material exposure: With glass-fiber price volatility and an improving demand outlook, manufacturers should lock in contracts where possible and explore resin formulations and hybrid composites that reduce fiber intensity without sacrificing performance.
- Prioritize demonstrator projects: Targeted pilot installations (especially in jurisdictions with proactive specification programs) yield outsized returns in both marketing and validation, accelerating the sales funnel.
- Prepare for selective M&A and partnerships: Market concentration metrics suggest room for consolidation—buyers should look for vertical integration opportunities (pultrusion + prefabrication) and capability deals (e.g., modular installation tech).
- Embed lifecycle-cost procurement metrics: Agencies should update tenders to reward total-cost-of-ownership benefits (maintenance, downtime avoided, and resilience) rather than first-cost alone.
Why PW Consulting’s report is the 2026 operational tool you need
The full Worldwide FRP Bridge Market report delivers the analytical models, procurement templates, and strategic playbooks required to move from intent to deployment in 2026. Subscribers receive:
- Executive dashboards and scenario models calibrated to policy and commodity-change triggers.
- Supplier scorecards, procurement specification language, and LCCA templates that agencies can operationalize immediately.
- Commercial negotiation frameworks and suggested contractual terms for risk-sharing on material-price escalation and installation timelines.
- Detailed competitive benchmarking and capability maps (regionally and by product family) to inform partnership, licensing, or acquisition decisions.
To preserve the utility of our segment-level intelligence, we intentionally withhold the granular regional, fiber-type, and application split tables in this public briefing. Those datasets, which drive precise go/no-go investment decisions, are available in the full report and through our advisory services.
Next steps
Organizations that want to turn 2026 opportunity into measurable outcomes should request PW Consulting’s Worldwide FRP Bridge Market report and engage our advisory team for a customized strategy session. The full report contains the proprietary segmentation, supplier scorecards, and downloadable financial models that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide FRP Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cold‑Formed Steel Frame Market to Rise from USD 39.86 Billion in 2025 to USD 57.19 Billion by 2032 at a 5.29% CAGR
By pmarketresearch, 2026-07-15
Worldwide Cold-Formed Steel Frame Market: Strategic Imperatives for 2026
Executive Snapshot
PW Consulting’s new Worldwide Cold Formed Steel Frame Market report — base year 2025, forecast 2026–2032 — equips senior executives, investors, and project leaders with the actionable intelligence required to make high-consequence decisions in 2026. The market reached approximately USD 39.86 Billion in 2025 and, under our central-growth case, is projected to expand at a 5.29% CAGR through 2032, reaching roughly USD 57.19 Billion by the end of the forecast window. These headline metrics frame a market characterized by steady demand, technological differentiation, and a fragmented supplier base that is being reshaped by standards, sustainability, and raw-material volatility.
Worldwide Cold Formed Steel Frame Market
Why this report matters for 2026 decision-making
- Timing: With global construction activity evolving post-pandemic and regulatory updates rolling through 2024–2026, 2026 is a pivotal year to reset supply-chain exposures and product strategies.
- Actionability: This study goes beyond high-level forecasts. It delivers ready-to-use commercial playbooks — pricing sensitivity matrices, supplier-risk heatmaps, prefabrication ROI templates, and scenario-based go-to-market roadmaps — that enable near-term operational moves without waiting for long planning cycles.
- Strategic clarity: The report synthesizes macro drivers (construction cycles, modularization trends), micro-level levers (manufacturing footprint, roll-forming capability, EPD publication), and regulatory inflection points into prioritized strategic options for both manufacturers and large-buying contractors.
Market dynamics shaping 2026 strategies
Three vectors will disproportionately influence competitive outcomes in 2026:
Worldwide Cold Formed Steel Frame Market
- Standards and code alignment — Recent technical releases and specification updates have created immediate compliance and specification opportunities. Adoption of updated design standards and technical guides is accelerating product re-specification across public and private projects.
- Raw-material pricing and supply resilience — Hot-rolled coil price volatility has raised unit cost sensitivity across the value chain. Firms that proactively hedge feedstock exposure or integrate upstream sourcing options will preserve margin and price competitiveness.
- Sustainability and disclosure — Procurement teams increasingly demand quantified life-cycle impacts. Companies with Environmental Product Declarations (EPDs) and low-embodied-carbon propositions are already capturing a growing share of specification-driven projects.
What the report delivers — practical contents for immediate use
PW Consulting’s report was designed as an operational toolkit for 2026. Key deliverables include:
Worldwide Cold Formed Steel Frame Market
- Validated market sizing and a 2026–2032 forecasting engine with interactive scenario pathways (base, downside, upside) to stress-test strategic options against macroeconomic and input-cost shocks.
- Supply-chain maps and concentration analysis that identify single-source risks, logistics chokepoints, and nearshoring opportunities for roll-formers and coil suppliers.
- Commercial playbooks: margin management dashboards, auction-ready bid templates for modular construction projects, and distributor-partner scorecards.
- Regulatory impact matrix that translates recent code and standards updates into specification changes, lead-time impacts, and compliance cost estimates for product teams.
- Technology and innovation scan covering roll-forming equipment, digital prefabrication workflows, and software-enabled production (BIM-to-fab linkages) that materially reduce on-site labor and shrink delivery windows.
- M&A and partnership identification guides highlighting tuck-in and capability-acquisition targets aligned to scale, prefabrication, or low-carbon credentials.
Competitive landscape — how established players are positioned
The cold-formed steel framing market remains fragmented by design, with a relatively low top-3/top-5 concentration compared with many other construction inputs. This structure creates both margin pressure and opportunity, depending on strategic posture.
Incumbent manufacturers and integrated steel producers are pursuing differentiated strategies:
- Large roll-formers and systems providers with deep North American roots have leveraged code-compliant product lines and distributor networks to serve mid-rise and high-rise commercial demand. Firms with strong engineering support and prefabrication offerings are winning specification-led projects.
- Vertically integrated steel producers are capitalizing on raw-material control. Their ability to offer reliable coil supply and technical support to framing manufacturers mitigates input-price shocks and shortens procurement cycles for large customers.
- Specialist technology and equipment providers are raising the bar on speed and precision. Companies that bundle software-driven design-to-manufacture solutions enable contractors to shift schedules and reduce on-site labor dependency — a decisive commercial advantage in tight labor markets.
- Newer entrants and smaller specialists are differentiating on sustainability credentials, publishing EPDs and focusing on low-embodied-carbon assemblies to access green-build pipelines.
Our report contains company-level strategic profiles and actionable benchmarking on product breadth, prefabrication capacity, EPD coverage, geographic manufacturing footprints, and partnership ecosystems — enabling buyers and investors to prioritize targets and negotiate from an informed position.
Recent industry developments that change the playing field
- Standards updates released in 2024–2025 have been widely adopted by code bodies and influential procurers, shifting design specifications across multiple jurisdictions. This creates immediate re-specification risk for non-compliant suppliers and opportunity for certified suppliers to capture incremental project share.
- Industry associations and awards continue to spotlight high-profile mid-rise and high-rise projects using cold-formed steel framing, accelerating market recognition and confidence among architects and developers.
- Raw-material pricing trends and regional coil-price increases in 2025–2026 are reshaping contract terms. Buyers are renegotiating indexation clauses and exploring alternative sourcing strategies — a key negotiation theme for 2026.
- Sustainability disclosures by select manufacturers are already affecting RFP outcomes in projects where embodied-carbon is a procurement criterion.
Five strategic moves for 2026
- De-risk feedstock: implement layered procurement — combine short-term hedges, regional suppliers, and long-term supplier agreements to stabilize cost exposure.
- Invest in prefabrication and digital workflows: prioritize technologies that reduce on-site labor, shorten schedules, and create higher-margin system sales rather than commodity rolls.
- Mobilize sustainability credentials: accelerate EPD publication and low-carbon product roadmaps to be first in line when procurement adds embodied-carbon requirements.
- Re-evaluate go-to-market: adapt distribution models, strengthen contractor partnerships, and deploy performance-based warranties tied to speed and quality metrics.
- Scan for consolidation opportunities: target bolt-on acquisitions that add prefabrication capacity, niche product lines, or regional market access — especially where standards alignment creates integration value.
Who should read this report
Executives of framing manufacturers, integrated steel producers, modular builders, construction tech investors, procurement heads at large contractors, and policy teams at public agencies will find immediate decision-useful content. The report combines market-size rigor with practical tools to accelerate commercial and operational decisions across the 2026 planning horizon.
Next steps and access
PW Consulting has structured the report to be immediately deployable: from a high-level strategic briefing for boards to downloadable operational templates for commercial teams. In keeping with our “trailer” approach, we have deliberately presented high-confidence macro metrics and strategic direction here while reserving the full segmentation, scenario models, supplier heatmaps, and the interactive forecasting tool for report subscribers. Those details — including granular, model-ready inputs and company benchmarking — are accessible on the report landing page.
For executives preparing budgets, renegotiating suppliers, or assessing M&A targets in 2026, the report functions as both a decision accelerator and a defensible evidence base for capital allocation. PW Consulting stands ready to brief Boards, run focused workshops, and customize the report’s tools to specific corporate contexts.
To request an executive briefing or to access the full report and its downloadable toolset, please visit the PW Consulting report page or contact our commercial team.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Formed Steel Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Industrial Epoxy Glass Market Poised to Grow at a 5.82% CAGR
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief: Worldwide Industrial Epoxy Glass Market — Critical Imperatives for 2026 Decision‑Makers
Executive snapshot
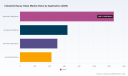
The global industrial epoxy glass market has reached a level of strategic significance rarely seen in commodity-linked specialty materials. After recovering and stabilizing through the early 2020s, the market recorded a total value of approximately USD 2,842.6 Million in 2025 and is modeled to grow at a compound annual growth rate (CAGR) of roughly 5.82% through our 2026–2032 forecast window. By 2032, baseline forecasts point toward a market north of USD 4.2 Billion (USD million basis), driven by sustained demand across high‑reliability electronics, aerospace & defense, automotive electronics and heavy industrial applications.
Worldwide Industrial Epoxy Glass Market
Why this report matters for 2026 corporate strategy
- Timing: 2026 is a pivot year — supply chains and procurement teams are recalibrating post‑pandemic inventory models while OEMs accelerate electrification and embedded electronics programs that lean on epoxy glass laminates.
- Margin pressure ahead: upstream resin pricing volatility and large incremental capacity additions create asymmetric risks to gross margins. Procurement or product teams that fail to model resin-price exposure and supplier capacity dynamics risk margin erosions in H2 2026–2027.
- Opportunity set: selective premiumization (flame‑retardant prepregs, visually critical prepregs, military‑grade laminates) and manufacturing modernization (in‑house machining and value‑added fabrication) remain the clearest paths to above‑market returns.
- Consolidation window: moderate market concentration combined with differentiated technical capabilities creates M&A and partnership opportunities for scale players and niche specialists alike.
What the PW Consulting report delivers — a practitioner’s toolkit
This report was authored to be operationally actionable for CPOs, product leaders, strategy teams and private equity investors. Key deliverables include:
Worldwide Industrial Epoxy Glass Market
- Top‑down and bottom‑up market model: historical series (2020–2025) and detailed scenario forecasts (2026–2032) with sensitivity levers for resin price, capacity additions and end‑market demand shocks.
- Full cost build‑up templates: standardized BOM and conversion models that isolate resin, reinforcement glass, energy, labor and logistics line items for unit‑cost estimation across common laminate and prepreg forms.
- Supplier mapping and scorecards: capability, certification and risk profiles for tier‑1 through tier‑3 producers; tailored sourcing templates for dual‑sourcing and nearshoring decisions.
- Regulatory and certification matrix: RoHS/REACH, UL94 and sector‑specific compliance checklists, including cost/time-to-certify estimates for aerospace and defense approvals.
- Competitive playbooks: capability-based cluster analysis and offensive/defensive movesets for global leaders, regional champions and contract manufacturers.
- M&A screening filters: quantitative models for target selection (scale, margin accretion, geographic fit, technology adjacency) and integration checklists focused on technology transfer and customer retention risk.
- Commercial strategy templates: value‑pricing frameworks and productization roadmaps for moving from commodity laminates to differentiated, higher‑margin offerings.
To preserve commercial value for subscribers, the report intentionally keeps granular sub‑segment shares and unit pricing behind the full report access page; the public brief is designed to demonstrate methodology and strategic importance while directing decision‑makers to the full dataset and interactive models.
Worldwide Industrial Epoxy Glass Market
Market dynamics to watch in 2026
- Raw‑material volatility: epoxy resin is the primary upstream feedstock. Recent price observations — for example, Northeast Asia epoxy resin pricing near USD 2.62/kg (April 2026) and China market quotes reported around USD 2,031/MT (February 2026) — underline how upstream swings transmit quickly to laminate producers’ cost bases. Procurement teams must stress‑test supplier quotes against +/- 15–20% resin swings in near‑term scenarios.
- Capacity and geographic imbalance: major capacity expansions in Asia are changing the supply equation. New and expanded facilities increase the risk of export margin compression for producers selling into mature markets, but also create sourcing opportunities for buyers who can leverage logistics and inventory strategies to lock in competitive supply.
- Certification and product differentiation: UL94 V‑0 flame retardancy and RoHS/REACH compliance remain table stakes for mainstream FR‑4 and related laminates. Differentiated prepregs (e.g., visual clarity, high‑Tg systems, flame‑retardant prepregs) are emerging as premium products with defensible pricing power.
- Concentration and competition: the market displays moderate concentration — top‑three and top‑five share metrics show meaningful, but not overwhelming, aggregation — implying space both for scale consolidation and for well‑positioned specialists to command niche margins.
Competitive landscape — strategic profiles and implications
Our report profiles the industry’s relevant manufacturers and synthesizes their strategic postures into actionable takeaways. Highlights include:
- Ventec International Group (Taiwan) — a global leader in high‑performance copper clad laminates and prepregs. Strengths: R&D depth, high‑performance product lines, and established relationships with advanced PCB manufacturers. Strategic implication: Ventec is likely to protect high‑end aerospace and telecom adjacencies through technology licensing and targeted capacity alignment.
- Isola Group (United States) — emphasizes high‑reliability copper‑clad laminates and prepregs. Strengths: strong brand with OEMs requiring high electrical reliability. Strategic implication: Isola will continue to invest in qualification programs and value‑added material system integrations to defend margin.
- Atlas Fibre, Franklin Fibre‑Lamitex, Current Inc., Iten Industries, Hexcel, Park Aerospace (United States) — these North American firms collectively represent product breadth across standard and specialty grades, as well as capabilities in fabrication and MIL/NEMA compliance. Strategic implication: regional service, fast turn prototyping and certifications keep North American players relevant despite price competition from Asia.
- SIDA (China JV) and Hony Engineering Plastics (China) — represent scale manufacturing and rapid product catalog evolution. Recent disclosures point to substantial annual capacity and updated product series meeting IEC/GB standards. Strategic implication: Chinese scale producers are positioned to pressure commodity laminate pricing globally; strategic responses include supplier partnerships, co‑investment in local capacity, or differentiated product strategies.
Recent industry moves underscore these dynamics: SHD Composites launched a flame‑retardant clear epoxy prepreg in April 2026, signaling product innovation at the material layer; Hony updated its product catalog and spec sheets in late 2025; and several Chinese producers have signaled capacity expansions that will influence global supply balances.
Strategic recommendations for 2026 — five priority actions
- Immediate (0–9 months): Implement a resin‑price hedging policy and renegotiate supplier contracts with transparent price pass‑through triggers. Run a two‑tier sourcing test (regional + global) to validate landed cost vs. lead time tradeoffs.
- Near term (9–18 months): Launch a product premiumization pilot — target one differentiated prepreg or flame‑retardant laminate with a defined go‑to‑market channel and margin target. Use the report’s cost build‑up templates to set price floors and escalation clauses.
- Operational (12–24 months): Invest in short‑run fabrication capabilities (machining, cutting, custom parts) to capture value from OEMs that prefer one‑stop suppliers. This reduces the race‑to‑the‑bottom on basic sheet commodities.
- Strategic sourcing (12–36 months): Consider equity or JV arrangements with regional producers to secure capacity and technical transfer. For global buyers, balancing exposure across Asian scale suppliers and North American specialist suppliers is the most resilient posture.
- M&A and innovation (24–36+ months): Use the market’s moderate concentration to target tuck‑ins that add certification pathways, customer relationships in aerospace/defense, or prepreg formulation IP. Prioritize targets with demonstrated qualification pipelines and low customer attrition risk.
How to use this brief and next steps
This briefing is a strategic trailer: it exposes the analytic backbone and commercial frameworks used in PW Consulting’s full Worldwide Industrial Epoxy Glass Market report while preserving the detailed sub‑segment tables, vendor scorecards and the interactive forecast model for report subscribers. Companies seeking to operationalize these recommendations should access the full report for:
- Downloadable models to run custom scenarios with your own resin pricing and demand assumptions.
- Full supplier scorecards with technical certifications and contact‑level sourcing intelligence.
- M&A screening outputs with ranked targets and integration risk matrices.
For procurement chiefs, R&D leaders and M&A teams planning 2026 actions: PW Consulting’s full dataset converts market signals into executable plans — from contract structures to capability investments and acquisition targets. Visit our report page to license the full intelligence package and gain immediate access to the detailed models and supplier playbooks that underpin the strategies outlined above.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Choroideremia Treatment Market Set to Soar at a 32.65% CAGR
By pmarketresearch, 2026-07-15
Worldwide Choroideremia Treatment Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive overview
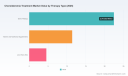
The choroideremia treatment landscape is entering a decisive chapter. Our proprietary market model projects a rapid expansion from the mid‑2020s base into the early 2030s, driven by a concentrated pipeline of gene‑based and vision‑restorative candidates, emergent optogenetic and small‑molecule approaches, and an evolving regulatory and reimbursement environment. From an established 2025 baseline, PW Consulting forecasts the global market to expand at a compound annual growth rate (CAGR) of 32.65% through 2032, culminating in a multi‑hundred million USD opportunity by the end of the forecast horizon. Concurrently, market concentration is high — the top three and top five developers account for the large majority of commercial and near‑commercial value — creating both competitive pressure and strategic opportunities for alliances, asset trades, and acquisition plays.
Worldwide Choroideremia Treatment Market
Why this report matters for 2026 decision‑makers
- Tactical timing: 2026 is a watershed year for choroideremia programs as academic, non‑profit and industry actors reposition portfolios after mixed clinical readouts and multiple program handovers. Decisions made now about partnerships, manufacturing scale‑up, regulatory strategy, and payer engagement will materially affect market access and commercial capture through 2032.
- Regulatory inflection points: Regulatory authorities remain divided on meaningful visual function endpoints. FDA precedent emphasizing larger letter‑gain thresholds has heightened development risk for traditional BCVA endpoints, while certain regional regulators may accept smaller gains or alternative functional endpoints. These differences create parallel approval pathways and demand bespoke evidence plans by jurisdiction.
- Payer & HTA pressure: Ultra‑rare prevalence, high one‑time treatment costs, and complex durability questions mean payers will scrutinize value — demanding long‑term effect evidence, risk‑share mechanisms, and innovative contracting. Developers without credible real‑world evidence (RWE) plans face commercialization delays and price erosion.
- Manufacturing and supply chain gating factors: AAV vector production capacity, GMP consistency for ocular dosing routes, and raw‑material cost volatility remain critical operational constraints. Manufacturing decisions taken in 2026 — insourcing vs. CDMO engagement, fill/finish choices, and scale prioritization — will determine time‑to‑market and per‑patient economics.
Competitive landscape — dynamics and tactical implications
The current developer ecosystem mixes pure‑play biotech innovators, optogenetic pioneers, and stewardship by non‑profit players. Several program transitions and regulatory designations in 2025–2026 are reshaping competitive trajectories:
Worldwide Choroideremia Treatment Market
- Kiora Pharmaceuticals (Encinitas, CA): Advancing a small‑molecule photoswitch platform with demonstrated functional vision endpoints in retinal degeneration programs. Kiora’s non‑viral approach reduces several vector manufacturing risks and presents a differentiated payer narrative focused on repeat‑dosing economics and broader patient applicability. Expansion into choroideremia is plausible, but execution will hinge on robust cross‑disease functional endpoint validation and manufacturing scale for ophthalmic formulation.
- Ray Therapeutics (Berkeley, CA): Building on optogenetic channelrhodopsin technology delivered via intravitreal administration, Ray has secured accelerated regulatory engagement for its lead RTx‑015 program. Intravitreal optogenetics lowers surgical complexity versus subretinal gene replacement, offering a potentially faster commercial route if safety and clinically meaningful vision improvement are demonstrated. Investors and partners should weigh the tradeoffs between novel mechanism advantage and the need for tailored visual rehabilitation services.
- Choroideremia Research Foundation (CRF): The acquisition of a legacy AAV gene replacement program and affiliated natural history datasets positions CRF as a data steward and potential enabler of secondary development or licensing. This stewardship model reduces barrier to entry for follow‑on developers but raises questions on commercialization scale and capital access — an opportunity for strategic collaborations between philanthropic, academic and industry players.
- Legacy and discontinued programs: High‑profile program halts and reprioritisations by larger firms underscore the clinical and commercial uncertainties in the space. These events have produced valuable clinical datasets and argue for re‑purposing assets or forming consortiums to extract patient‑relevant endpoints and comparator data.
Key market dynamics and technology themes
- Endpoint and trial design innovation: Conventional BCVA gains have proven a high bar for many choroideremia candidates. Expect to see increased regulatory acceptance of alternative functional endpoints, composite measures, and patient‑reported outcomes — provided they are validated with robust natural history and longitudinal datasets.
- Platform vs. one‑off therapies: Developers are choosing between platform‑level investments (optogenetics, photoswitches) that can address multiple IRDs, and single‑indication AAV replacements. Platform strategies may offer superior long‑term value and optionality but require different commercialization and payer narratives.
- Manufacturing economics as strategic moat: Control of AAV supply chains, reproducible GMP processes, and scalable intravitreal vs. subretinal delivery capabilities will differentiate winners. Cost models must account for vector yield uncertainties, cold‑chain logistics, and potential repeat dosing in non‑durable modalities.
- Consolidation and data monetization: Asset transfers and foundation stewardship create openings for licensing structures, outcome‑based deals, and pooled real‑world evidence initiatives that can de‑risk late‑stage development and support HTA submissions.
What PW Consulting’s Worldwide Choroideremia Treatment Market report delivers
This report is designed as an operational playbook for executives deciding on investment, partnership, or commercial strategies in 2026. Key deliverables include:
Worldwide Choroideremia Treatment Market
- A validated market model with historical (2020–2025) performance and a granular multi‑scenario forecast through 2032, reflecting varying uptake, regulatory outcomes, and therapeutic durability assumptions (note: detailed segment tables and regional splits are summarized in the full report).
- Competitive intelligence dossiers on all active and legacy programs, including asset histories, trial readouts, strategic moves (acquisitions, discontinuations, designations), and likely commercialization pathways.
- Regulatory playbook mapping FDA/EMA endpoint expectations, orphan/ATMP pathways, and accelerated approval risk matrices tailored to choroideremia modalities.
- Payer and HTA frameworks outlining evidence thresholds, expected price ranges under different durability assumptions, and risk‑sharing templates, including milestone and outcomes‑based contract constructs.
- Manufacturing and supply chain optimization guide covering AAV sourcing strategies, CDMO selection criteria, tech transfer checklists, and cost sensitivity analyses.
- M&A and partnership decision frameworks with trigger maps, valuation levers, and integration risk assessments specific to ultra‑rare ocular programs.
- Due‑diligence checklist and an investor‑oriented valuation workbook that converts clinical and regulatory scenarios into commercial NPV ranges and capital need projections.
Strategic recommendations for 2026
- Adopt a scenario‑based investment approach: fund pilots that preserve upside across efficacy and durability outcomes rather than overcommitting to a single clinical readout.
- Prioritize evidence generation for alternative functional endpoints and long‑term durability: early agreements with regulators and payers on acceptable surrogates will materially reduce commercialization risk.
- De‑risk manufacturing early: secure vector capacity or validated CDMO partnerships with ocular experience, and build contingency plans for yield variability and raw‑material shortages.
- Explore hybrid commercialization models: partnerships with specialized ophthalmic networks and rehabilitation providers can accelerate patient access for optogenetic or photoswitch therapies requiring ancillary services.
- Leverage non‑dilutive capital and philanthropic stewardship: foundations controlling legacy datasets or assets can be strategic allies in de‑risking development and validating endpoints.
- Design payer‑centric clinical programs: incorporate prospective RWE capture, registry alignment, and outcomes measurement that facilitate value‑based contracting.
Concluding perspective and next steps
Choroideremia remains an ultra‑rare indication with outsized scientific interest and complex commercial dynamics. The market is growing rapidly from a small base, concentrated among a few developers and shaped by regulatory endpoint debates, manufacturing constraints, and payer skepticism. For companies, investors, and health systems, 2026 is a moment to recalibrate — to prioritize flexible evidence strategies, secure manufacturing pathways, and align early with payers and patient organizations.
PW Consulting’s full Worldwide Choroideremia Treatment Market report provides the data tables, segmented forecasts, scenario workbooks, and actionable playbooks needed to convert strategic choices into execution plans. For executives who need to move from hypothesis to action in 2026, the report is structured to shorten decision cycles and quantify the impacts of alternative strategies without disclosing the proprietary segmentation that underpins our valuation work.
Contact PW Consulting to request the full report or to schedule a bespoke briefing tailored to your investment, licensing, or corporate development agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Choroideremia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com