

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Biodegradable Disposable Foodservice Market Hits USD 11.95 Billion in 2025, Signaling Strong Growth Ahead

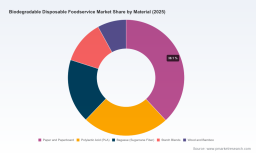
Worldwide Biodegradable Disposable Foodservice Market: Strategic Outlook for 2026 Decision-Making
PW Consulting's latest market study on the Worldwide Biodegradable Disposable Foodservice Market crystallizes why 2026 is a hinge year for manufacturers, foodservice operators, retailers, and investors. The sector—driven by regulatory pressure, corporate sustainability commitments, and shifting procurement economics—has matured from niche experimentation into a mainstream procurement category. Our report, based on 2020–2025 historical analysis and a 2026–2032 forecast, quantifies that transition: the market reached approximately USD 11,951.6 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.02% across the forecast window, passing the USD 20.5 Billion milestone by 2032. The market remains fragmented—our concentration analysis shows a CR3 near 18.5% and a CR5 around 26.8%—creating spaces for scale play, regional champions, and vertical integration.
Worldwide Biodegradable Disposable Foodservice Market
Why this report matters for 2026 corporate strategy
-
Timing: 2026 is the first full year many new regulatory measures and public procurement rules take effect in major markets. Companies that align product portfolios, supply chains, and compliance frameworks now will avoid costly last-minute transitions.
Worldwide Biodegradable Disposable Foodservice Market -
Clarity: With a clear growth trajectory and quantifiable market sizing, firms can move beyond aspirational ESG statements to concrete commercial plans—capital allocation, plant footprints, and procurement contracts—that reflect real demand curves.
Worldwide Biodegradable Disposable Foodservice Market -
Actionability: The report blends top-line forecasting with playbooks for pricing, material sourcing, composting compatibility, and retailer/foodservice contracting—turning market intelligence into executable steps for 2026.
What the PW Consulting report contains (operational depth)
-
Comprehensive market sizing and trend maps: validated historicals (2020–2025) and a granular forecast (2026–2032) with scenario analysis reflecting regulation-driven and baseline adoption paths.
-
Segment and material framework: a disciplined taxonomy across materials (paperboard, PLA, bagasse, starch blends, wood & bamboo) and product formats (plates, cups, containers, cutlery, straws). Note: to preserve strategic value we summarize dynamics without publishing every subsegment’s raw figures in this release.
-
Supply-chain and raw-material economics: step-by-step cost modeling for feedstocks (including agricultural residues like bagasse), sensitivity analysis to commodity swings, and logistics-led margin implications for regional production hubs.
-
Regulatory and compostability mapping: jurisdiction-by-jurisdiction compliance implications, operational thresholds for industrial vs. home compostability, and the interplay with Extended Producer Responsibility frameworks.
-
Commercial go-to-market modules: contracting templates, pricing strategies for mix shifts, private-label vs. branded options, and a retailer/foodservice scorecard to prioritize channel efforts.
-
Competitive intelligence and M&A playbook: validated company profiles, capability matrices, partnership archetypes, and valuation levers for buy-build-partner decisions.
-
Risk matrix and contingency planning: supply disruption scenarios, regulatory downside cases (e.g., tighter compostability tests), and mitigation measures such as dual-sourcing and co-packing arrangements.
Market dynamics shaping 2026 decisions
-
Regulatory acceleration: The EU’s Packaging and Packaging Waste Regulation (PPWR) coming into force creates harmonized design-for-recycling mandates that ripple across supply chains. Several U.S. states are implementing Extended Producer Responsibility (EPR) laws with provisions that affect compostable formats. Additionally, national bans—such as the UAE’s announced 2026 restriction on a broad set of single-use plastics—are compressing timelines for portfolio transitions.
-
Standards and composting definitions: Recent policy moves (including a notable decision by a U.S. standards body in early 2026 regarding synthetic polymers in organic compost) are tightening end-of-life definitions, raising the bar for certification and labeling. Manufacturers must now be equally fluent in product performance and in waste-system compatibility.
-
Raw-material advantage: Agricultural residues—most notably sugarcane bagasse—have become a practical, technical, and commercial mainstay for compostable tableware. Their abundance, favorable mechanical properties, and consumer acceptance render them a default feedstock in many value chains.
-
Channel transformation: Foodservice operators and major retailers are consolidating procurement, favoring suppliers who can guarantee compliance across multiple jurisdictions and provide traceability, cost predictability, and circularity reporting.
Competitive landscape — strategic profiles and implications
The market’s low concentration score signals opportunity: regional leaders and focused innovators can capture meaningful niches before global consolidation accelerates. Below are strategic takeaways on major incumbents and challengers included in our competitive analysis.
-
Huhtamaki Oyj (Espoo, Finland): A global platform with deep molded-fiber and paper-based capabilities. Strengths include scale and wide distribution; recent product launches show a pragmatic approach to reducing polymer content while maintaining performance. Strategic implication: scale investments for higher-value compostable formats and partnerships with waste-management players to guarantee end-of-life claims.
-
Vegware (Edinburgh, UK): A plant-based specialist with a strong proposition in PLA and bagasse formats. Advantageous in markets that prioritize renewable feedstocks and certification transparency. Strategic implication: pursue modular manufacturing partnerships in high-growth APAC and North American urban centers to reduce logistics emissions and lead times.
-
Eco-Products (Novolex, USA): Certified compostable product range with strong foodservice connections. Positioning benefits from certification pedigree—an important commercial differentiator as composting infrastructure matures. Strategic implication: extend service offers (e.g., collection/logistics) to lock in large institutional clients.
-
World Centric (California, USA): Niche focus on commercial composting compatibility. Reinforce commercial partnerships with composters and large-scale foodservice operators where industrial composting exists as a mature channel.
-
Asia-based producers (Bioleader, Luzhou Pack/OASIS, GreenGood): Competitive cost structures and technical capabilities in bagasse and molded pulp. Their rapid capacity expansion and export orientation make them attractive partners or acquisition targets for branded Western players seeking margin recovery.
-
Regional specialists (Biopac UK, Green Wave International, AMS Compostable, Sabert, Genpak): These firms demonstrate how regional compliance expertise and tailored product ranges can outperform global competitors in complex regulatory environments.
Recent market moves to watch
-
Strategic alliances and channel plays: In 2025 a European strategic alliance between a molded-fiber specialist and a major retailer demonstrated the power of co-developed, plastic-free SKUs to accelerate retail rollouts.
-
Product innovation: Several 2025–2026 product launches—ranging from low-plastic ice-cream cups to coffee cups designed to lower lifecycle impacts—illustrate that incremental material engineering remains a path to differentiation.
-
Market expansion: Regional players have been expanding into North America and other high-volume markets through incubator and distributor programs, signaling the next wave of competitive intensity.
Strategic recommendations for 2026 (executive checklist)
-
Manufacturers: Prioritize modular capacity investments that allow shifting between bagasse, paperboard, and starch blends; formalize certification roadmaps and integrate product-service bundles (e.g., take-back, compost collection) to support claims.
-
Foodservice operators & retailers: Consolidate suppliers around compliance, traceability, and total-cost-of-ownership rather than unit price alone. Pilot regionally tailored composting partnerships before rolling out nationally.
-
Raw-material suppliers: Secure offtake with long-term contracts tied to sustainability KPIs; invest in pre-treatment and standardization capabilities to meet industrial processing requirements.
-
Investors & M&A teams: Target companies with strong channel lock-ins (institutional contracts, retail programs), technical IP around coatings and compostability, or regional production footprints that address rising logistics costs. Valuations should price in near-term regulatory tailwinds but also account for potential standard harmonization risks.
-
Policy & compliance officers: Monitor EPR rollouts and compostability standard revisions closely; use scenario planning to quantify compliance costs and design-for-recycling trade-offs.
Conclusion — what leaders must do in 2026
2026 is not a year for passive optimism. The combination of predictable market growth (an 8.02% CAGR across 2026–2032), regulatory inflection points, and evolving waste-management realities requires decisive moves: invest in adaptable manufacturing, lock-in compliant feedstocks, and build integrated service propositions that guarantee end-of-life outcomes. The market’s fragmentation offers opportunities for focused scale, but first-mover advantages will accrue to those who align product innovation with regulatory certainty and circular-economy partnerships.
PW Consulting’s full Worldwide Biodegradable Disposable Foodservice Market report provides the granular segmentation, regional forecasts, and proprietary supplier scorecards necessary to convert these strategic implications into boardroom decisions. For executives preparing budgets, M&A teams assessing targets, or procurement leads redesigning supplier panels, the report is the operational intelligence map for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Biodegradable Disposable Foodservice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com