

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Worldwide Military Two-person Rotorcraft Market to Reach USD 12.73 Billion by 2032 at a 4.35% CAGR
By pmarketresearch, 2026-07-15
Worldwide Military Two-person Rotorcraft Market — Strategic Insights for 2026 Decision-makers
Executive summary
PW Consulting’s latest market study on the Worldwide Military Two-person Rotorcraft Market positions 2026 as an inflection year for procurement, industrial strategy, and alliance-driven R&D. Using 2025 as the report’s base year, the market expanded from approximately USD 7,650.4 Million in 2020 to USD 9,450.0 Million in 2025. Our modelling forecasts a near-term market size of roughly USD 10,052.2 Million in 2026 and projects growth to about USD 12,731.5 Million by 2032, implying a compound annual growth rate (CAGR) of 4.35% across the 2026–2032 forecast window. Market concentration is material: the top three OEMs account for a majority share (CR3 = 58.4%) and the top five command an even larger portion (CR5 = 76.2%), creating strategic implications for competition, supplier leverage, and national procurement policy.
Worldwide Military Two-person Rotorcraft Market
Why this report matters in 2026
Decision timelines for military rotorcraft are long and capital-intensive. 2026 will see programs transition from capability-definition into contracting and early production for several operators; simultaneously, NATO-aligned Next Generation Rotorcraft studies are shaping medium-lift requirements for the 2035+ timeframe. This creates a two-speed environment: immediate modernization and force-mix optimization versus long-horizon platform development. Our study translates that duality into actionable choices for defense ministries, OEMs, tier‑1 suppliers, and financial sponsors.
Worldwide Military Two-person Rotorcraft Market
What the report delivers (practical, actionable content)
- High-fidelity market sizing and a demand-by-year model calibrated to 2020–2025 historicals and forecasts through 2032, presented in constant USD (base year 2025).
- Scenario-based outlooks: three demand scenarios (baseline, accelerated modernization, and constrained spending) with sensitivity testing against defense budget trajectories and geopolitical shocks.
- Competitive landscaping that profiles incumbent two-person rotorcraft OEMs, their platform families, export footprints, and near-term product developments.
- Procurement playbooks for armed forces and acquisition authorities that convert capability requirements into procurement lot-sizing, risk mitigation clauses, and in-service support (ISS) contracting options.
- Supply-chain heatmaps and cost-driver analysis that quantify exposure to raw-material volatility (notably titanium and composite feedstocks) and to long lead times in advanced composite production.
- Transaction and partnership guidance: valuation comparators, M&A targets, and JV structures tailored for quick-time-to-market technology insertion (avionics, weapons integration, and mission systems).
- Implementation tools: an executive dashboard template, a supplier due-diligence checklist, and a phased integration roadmap for adopting modular mission packages and digital-enabled sustainment.
Key industry dynamics shaping 2026 strategies
- Program timing and NATO NGRC: The NATO Next Generation Rotorcraft Capability workstream has advanced concept studies and is influencing medium-lift roadmaps; early concept awards and OEM-led collaborations are already shifting R&D priorities toward compound and high-speed architectures.
- Supply-chain strain on advanced materials: Aerospace titanium demand continues to rise (the broader aerospace titanium market was estimated at around USD 3.1 billion in 2025 and showed further growth into 2026), while composite manufacturing constraints are identified as a multi-year bottleneck for scaling production of modern rotorcraft airframes and rotor assemblies.
- Consolidation and supplier power: A concentrated OEM market (high CR3/CR5) increases the bargaining position of leading manufacturers for large bilateral deals, but it also surfaces opportunities for niche suppliers and systems integrators to capture aftermarket and missionization revenue.
- Procurement behavior: Buyers are favoring flexible, modular platforms that can be rapidly reconfigured for ISR, light-attack, and training roles to maximize fleet utility and lower through-life costs.
Competitive landscape — what to watch
Our competitive review focuses on the principal platform providers and their strategic postures:
Worldwide Military Two-person Rotorcraft Market
- Airbus Helicopters (Marignane, France): A clear leader in light and multi-role two-crew platforms with active contract momentum in Europe. Recent program activity includes exercised options and new orders for light combat variants, alongside public concept work in collaboration with partners on next-generation rotorcraft concepts.
- Bell Textron (Fort Worth, USA): Positions light single- and twin-engine platforms into training and forward-area utility roles; its footprint in export training fleets makes it relevant for countries seeking lower-cost entry points into rotary training modernization.
- Leonardo Helicopters (Rome, Italy): Maintains strength in light twin multi-role rotors and trainer/utility types, often pairing avionics and mission systems to win modular capability contracts.
- Russian Helicopters / Rostec (Moscow, Russia): Continues to field dedicated two-seat attack and reconnaissance rotorcraft with designs oriented for anti-armor and battlefield support missions; geopolitical considerations influence market access and aftermarket services.
- Boeing (Arlington, USA): Anchored by heavy attack/tandem-crew designs in allied force inventories; platform modernization and avionics refresh programs remain a core part of sustainment and upgrade opportunities.
Recent company-specific events in late 2025–early 2026 illustrate tactical positioning: a European operator exercised options to expand a light combat helicopter fleet; a major OEM unveiled next-generation rotorcraft concepts in collaboration with missile and systems suppliers; and significant national orders for light combat helicopters were announced. These moves underscore a near-term emphasis on light/medium capability refresh and mid-term investment in NGRC-class technologies.
Strategic recommendations for 2026 (by stakeholder)
- Procurement authorities: Prioritize modularity clauses and production-rate flex options in contracts. Structure multi-year buys into initial tranches with clear industrial participation incentives to preserve sovereign sustainment capacity. Use our scenario models to stress-test lot-sizing against budget uncertainty.
- OEMs: Protect production continuity by investing in alternative suppliers for critical materials (titanium and advanced composites) and by diversifying composite-processing capabilities through partnerships or captive facilities. Accelerate modular mission-package development to capture expansion opportunities in ISR and light-attack roles.
- Tier‑1 and systems integrators: Focus on open-architecture mission systems and retrofit kits that extend legacy two-person platforms. Offer bundled sustainment contracts using predictive-maintenance analytics to lock in recurring revenue streams.
- Investors and PE: Look for carve-outs in aftermarket spares, missionization electronics, and composite-processing facilities. Valuations should account for concentration risk (high CR3/CR5) but also for defensible niche positions.
- Allied R&D consortia: Leverage collaborative R&D to de-risk NGRC technology paths (e.g., compound/hybrid rotorcraft) and to distribute development cost and sovereign IP rights across partners.
Operational risk radar — what to monitor through 2026
- Raw-material indices (titanium and carbon-fiber feed): input cost pressure and lead-time shifts.
- Composite manufacturing capacity and skilled labor availability: lead-time and quality variance.
- Defense budget signals and program re-baselines among large buyers.
- NATO NGRC milestones and award cadence for concept-to-demonstrator transitions.
- Export controls and geopolitical flashpoints that alter exportability and long-term sustainment.
- OEM order books and announced option exercises — near-term production ramp indicators.
How to use this report in 2026
PW Consulting’s report is designed as a decision-support instrument. Practical use cases include:
- Structuring multi-year acquisition and sustainment contracts with indexed cost and performance gates.
- Defining industrial participation and technology-transfer clauses aligned with sovereign capability objectives.
- Prioritizing capex for composite-processing and titanium sourcing to secure factory throughput for planned production ramps.
- Building M&A screening criteria around aftermarket revenue defensibility and systems-integration roadmaps.
Conclusion and next steps
2026 represents a pivotal year for two-person military rotorcraft strategy: immediate procurement decisions will lock in fleet shapes for a decade, while NGRC-era requirements are already redirecting R&D investments. PW Consulting’s market model—grounded in historicals through 2025 and forward-looking to 2032—provides the quantitative backbone and the operational playbooks that senior leaders need to convert strategic intent into executable programs.
For readers requiring the granular datasets (regional and role-specific splits, segment-level forecasts, supplier matrices, and full scenario outputs), the full report contains the detailed tables and model access necessary for transaction-level planning and contract negotiation. Visit PW Consulting’s report page to download the executive package and to request a bespoke briefing that maps our findings directly onto your program timelines and risk tolerances.
For detailed analysis of this topic, please visit the official page: Worldwide Military Two-person Rotorcraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Functional Magnetic Resonance Imaging Market to Reach USD 4,117.9 Million in 2025, Poised for 6.42% CAGR to USD 6,365.6 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Functional Magnetic Resonance Imaging Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market briefing on the Worldwide Functional Magnetic Resonance Imaging (fMRI) Market distills seven years of historical trends and a seven-year forecast into a concise, decision-grade playbook for executives, clinical leaders, and investors planning for 2026. Anchored on a base year of 2025 and a forecast window through 2032, the report quantifies a market poised to expand at a compound annual growth rate (CAGR) of 6.42%. The global fMRI ecosystem—already a multibillion-dollar clinical and research platform—continues to demonstrate resilience as hardware innovation, AI-enabled software, and regulatory shifts reshape procurement, service models, and clinical adoption.
Worldwide Functional Magnetic Resonance Imaging Market
Why this briefing matters for 2026
-
Timing-sensitive capital allocation: procurement cycles for MRI systems have long lead times. Our analysis aligns procurement windows with regulatory and supply-chain inflection points now visible on the horizon.
Worldwide Functional Magnetic Resonance Imaging Market -
OPEX vs CAPEX trade-offs: volatile supply markets and the emergence of low-cryogen platforms force a re-evaluation of total cost of ownership (TCO). The briefing provides frameworks for quantifying operating-risk premiums that should be embedded into 2026 capital budgets.
Worldwide Functional Magnetic Resonance Imaging Market -
Strategic positioning for competitive advantage: vendors and health systems that pair hardware with optimized fMRI workflows, turnkey stimulation hardware, and AI-accelerated analytics will secure differentiated revenue and utilization trajectories.
Snapshot: Market trajectory and concentration
The fMRI market is entering 2026 from a position of sustained growth: our model shows clear expansion from the mid‑2020s into the early 2030s, with the market size increasing materially in the last five years and continuing to expand under a 6.42% CAGR through 2032. Importantly, market share is concentrated—our concentration metrics show that the top three vendors account for roughly 62% of market value while the top five approach nearly 78%. This concentration underscores both the scale advantages enjoyed by leading OEMs and the strategic opportunities available to niche innovators and service specialists.
Core dynamics shaping 2026 decisions
-
Supply-chain and raw-material pressure: MRI magnet technologies historically rely on cryogens and helium logistics. Recent supply disruptions have led to spot price spikes that materially affect service economics. Procurement teams must now model helium risk as a first-order variable in vendor selection and contract negotiation.
-
Regulatory momentum toward low‑cryogen platforms: FDA clearances in 2025–2026 for lower‑helium or virtually helium‑free platforms represent a structural shift. Early adopters of these platforms stand to shrink long-term service risk and stabilize OPEX, while laggards face higher volatility exposure.
-
Software and workflow monetization: AI-based reconstruction and workflow platforms are migrating from point improvements to system-level differentiators. Vendors combining advanced reconstruction, standardized stimulation hardware, and validated analytics pipelines will capture higher-margin service and software revenue.
-
Clinical-commercial convergence: an expanding base of clinically validated fMRI applications—pre-surgical mapping, connectivity-informed diagnostics, and neurosurgical planning—creates new reimbursement and referral dynamics that organizations must map into service line strategies.
What the PW Consulting report contains (practical, operational, and investment-ready)
-
Market sizing and forecast model: a transparent, auditable financial model spanning 2020–2032 with scenario toggles for helium pricing, regulatory adoption rate, and AI workflow penetration. The model is designed for CFOs and strategy leads to run sensitivity analyses relevant to 2026 capital plans.
-
Procurement playbooks: vendor selection checklists, negotiation levers (warranty structure, helium‑risk sharing, service SLAs), and channel strategies for deploying modular fMRI solutions in mixed clinical/research environments.
-
Clinical adoption frameworks: validated use cases, implementation roadmaps for integrating fMRI into neurosurgical and neuro-oncology pathways, and metrics to track time-to-value post-installation.
-
Competitive intelligence dossier: granular company profiles, product roadmaps, patent activity snapshots, and go‑to‑market alignment analyses to support M&A diligence or partnership scouting.
-
Regulatory and reimbursement map: timelines for device clearances, policy levers to watch in major markets, and a pragmatic guide to positioning fMRI services for reimbursement and grant‑supported research.
-
Service and aftermarket optimization: templates for hybrid service models (in‑house + OEM), lifecycle management, and opportunities to convert installed bases through software monetization.
Competitive landscape: who to watch and why
The competitive topology is dominated by global OEMs with diversified MRI platforms and growing software stacks, alongside specialist providers that offer turnkey fMRI stimulation and workflow solutions. PW Consulting highlights several players whose strategic moves will be material to 2026 dynamics:
-
Siemens Healthineers (Erlangen, Germany): A broad MAGNETOM portfolio coupled with ongoing advances in bore design and helium‑management technologies has positioned the company to capitalize on clinical fMRI expansion and low‑cryogen transitions. Recent FDA clearance of a 1.5T platform featuring virtually helium‑free technology is a key differentiator for buyers prioritizing operational stability.
-
GE HealthCare (Chicago, USA): The SIGNA family and recent clearances for next‑generation platforms and AI workflow tools reflect an aggressive push to embed fMRI capabilities within end‑to‑end imaging platforms. GE’s regulatory wins in early 2026 validate a strategy that pairs hardware refreshes with software ecosystems.
-
Philips Healthcare (Amsterdam, Netherlands): Philips is advancing AI-powered reconstruction and workflow acceleration with approvals for dual-AI software that materially shortens scan times and improves neuro image fidelity—advantages that translate directly into throughput and patient pathway optimization.
-
Canon Medical Systems (Otawara, Japan): Canon’s emphasis on integrated visualization and dedicated fMRI applications aims to simplify clinical workflows, especially for centers moving from research use to routine clinical mapping.
-
United Imaging Healthcare (Shanghai, China): Rapid product introductions and high-performance gradient platforms are enabling competitive entries in advanced fMRI and ultra‑high field segments, especially in markets prioritizing capital efficiency and feature parity.
-
NordicNeuroLab (Bergen, Norway): As a specialist in fMRI stimulation and turnkey workflow tools, NordicNeuroLab remains a crucial partner for centers seeking standardized, cross-vendor fMRI acquisition and stimulus presentation capabilities.
Recent developments with strategic implications (2025–early 2026)
-
FDA clearances for low-cryogen and AI-enabled platforms—granted to multiple vendors in late 2025 and early 2026—reduce the technical barrier to replacing legacy fleets and materially change the calculus for long-term service contracts.
-
Product launches showcasing remote imaging platforms and dynamic videography capabilities signal a market move toward distributed, multi-site research networks and centralized analytics hubs.
-
Helium market volatility in early 2026 has introduced an immediate cost pressure that will compress margins for older fleets and create a multi-year demand wave for low‑helium technologies.
Strategic recommendations for 2026
-
For hospital systems and imaging networks: prioritize prospective procurement on platforms validated for low‑cryogen operation and AI workflow integration. Negotiate helium-risk sharing mechanisms and demand transparency on software roadmaps and upgrade paths.
-
For vendors and OEMs: accelerate commercialization of helium‑resilient magnet designs and monetize software with clear clinical value propositions (reduced scan time, improved diagnostic yield). Explore bundled service models that shift buyers away from purely transactional CapEx decisions.
-
For investors and M&A advisors: use the concentration metrics as a guide—scale matters—but also look for high-margin niche playbooks (turnkey fMRI workflows, validated analytics, multi-vendor stimulation hardware) that could be consolidated to capture aftermarket and software revenue streams.
-
For research institutions: leverage the growing availability of cloud-enabled analytics and vendor-neutral stimulation solutions to drive multi-center studies while reducing per-site infrastructural burdens.
Scenario planning: risk vectors and upside catalysts
-
Downside risk: prolonged helium supply disruption and slow regulatory adoption could depress utilization and delay fleet modernizations—sensitive to short-term cash constraints in public health systems.
-
Base case: steady recovery in equipment renewals, migration toward low‑cryogen platforms, and gradual software monetization consistent with a mid‑single-digit CAGR across the forecast window.
-
Upside catalysts: accelerated reimbursement for fMRI-derived diagnostics, broad adoption of AI-accelerated protocols that double throughput, or rapid consolidation in the aftermarket service market could materially outperform base projections.
How to use the full PW Consulting report in 2026 planning
-
Run the model: our interactive financial model lets procurement teams stress test vendor offers against helium-price scenarios, upgrade timelines, and utilization assumptions.
-
Validate clinical ROI: use our adoption playbooks and workflow benchmarks to quantify the marginal benefit of fMRI-enabled pathways versus standard imaging in neurosurgical and neuro-oncology services.
-
Inform negotiations: our vendor playbooks provide clause language for risk-sharing on raw materials, upgrade credits, and software‑as‑a‑service commitments—tools that materially reduce downside risk in long-term contracts.
PW Consulting’s Worldwide fMRI Market report is deliberately structured to guide 2026 strategic decisions without compromising your need for verified, proprietary detail. We present the analytic scaffolding and action steps here; the full report contains the underlying segment models, company-by-company financials, and the downloadable scenario model you can apply directly to your procurement and investment cases.
To access the complete dataset, proprietary segment breakdowns, and the interactive forecast tool, visit the official report page or contact the PW Consulting client desk. Our team is available for workshops to translate these insights into a tailored 2026 strategic plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Functional Magnetic Resonance Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 1‑Decanol Market to Expand at 6.5% CAGR, Hitting USD 436.36 Million by 2032 as Asia‑Pacific Leads with USD 120.69 Million
By pmarketresearch, 2026-07-15
Worldwide 1‑Decanol Market — Strategic Outlook for 2026: Navigating Growth, Supply Complexity, and Regulatory Reset
PW Consulting’s latest Worldwide 1‑Decanol Market report (base year 2025, forecast 2026–2032) distills the commercial imperatives chemical, personal‑care, and specialty‑polymer executives must act on in 2026. The mid‑chain fatty alcohol sector achieved material growth through 2020–2025 and the 1‑Decanol market reached approximately USD 280.8 million in 2025. Our baseline forecast projects a steady compound annual growth rate (CAGR) of 6.5% into the 2026–2032 window, with the market trajectory reflecting both structural demand for performance additives and episodic supply‑side shocks. This release is a strategic primer — it reveals the levers that matter, the blind spots to avoid, and the decision frameworks we recommend for the coming planning cycle, while preserving the granular segment and regional datapoints that subscribing clients can access on the report landing page.
Worldwide 1-Decanol Market
Why 2026 Is a Pivotal Year
-
Commercial inflection: After a period of steady expansion, 2026 will be a year when procurement and product teams must choose between defensive cost management and offensive share capture. Our scenario work shows that companies that align feedstock strategy with product differentiation will materially outperform peers.
Worldwide 1-Decanol Market -
Regulatory tightening: New regulatory milestones in Europe and state‑level actions in the U.S. are reshaping product compliance obligations. These changes will have immediate implications for formulations, labeling, and upstream supplier qualification.
Worldwide 1-Decanol Market -
Supply chain recalibration: Raw material volatility and trade policy shifts are prompting re‑routing of sourcing flows and accelerating near‑sourcing projects, particularly for producers reliant on oleochemical feedstocks.
High‑Level Market Dynamics — Drivers and Risks
-
Demand composition. End‑use pull remains broad — from plasticizers and lubricants to surfactants and flavors/fragrances. Growth is underpinned by durable industrial applications and selective premiumization in personal care and pharmaceutical excipients. That said, growth is heterogenous: the fastest upside is tied to high‑purity specialty grades and formulations that capture sustainability value.
-
Feedstock pressure. Natural‑feedstock suppliers have faced a tightening cost envelope following supply constraints in key producing geographies. Commodity swings have increased feedstock cost pass‑through risk for natural 1‑Decanol producers and are sharpening the cost‑competitiveness gap with synthetic routes.
-
Trade and tariff landscape. U.S. trade measures enacted in early 2026 have altered competitiveness for several import flows, forcing buyers and sellers to reprice or reroute. For export‑dependent producers, these tariffs materially affect destination strategies.
-
Regulatory overlay. EU chemical regulation updates require refreshed exposure dossiers for surfactant uses by mid‑2026; California’s recent listing activity has elevated disclosure and labeling risk for finished consumer products. These two vectors will increase compliance costs and slow product introductions for companies that lack regulatory bandwidth.
-
Consolidation and capacity signals. Market concentration at the producer level provides both stability and a capacity‑management lever for incumbents. Recent capacity investments and premium grade launches indicate incumbents are pursuing differentiated pathways rather than pure volume competition.
Segmentation & Strategic Positioning (Top‑Level)
PW Consulting’s segmentation framework evaluates 1‑Decanol across source routes (natural oleochemical vs synthetic petrochemical), application classes (industrial intermediates, personal care, specialty solvents, and others), and regional flows. In practice, strategic choices hinge less on nominal segment shares than on margin profile, supply risk, and regulatory exposure. Key takeaways for 2026 planning:
-
Source diversification is a hedge. Companies that maintain optionality across natural and synthetic routes can manage margin volatility and regulatory exposure more effectively.
-
Higher purity and specialty grades command optionality. Investment in fractional separation, hydrogenation control, or tailored purification is an accelerator to enter pharmaceutical and high‑end personal care spaces.
-
Formulation‑led differentiation beats volume play in constrained markets. Where feedstock costs are elevated, value capture comes from formulations that reduce active load or enable premium pricing through performance or sustainability claims.
Competitive Landscape — What Leading Producers Are Doing
The competitive map is anchored by global chemical majors and regional oleochemical champions. Each competitor pursues a distinct combination of feedstock integration, geographic reach, and product strategy. Our analysis of public moves and proprietary intelligence identifies three prevailing strategic archetypes:
-
Integrated majors focusing on portfolio breadth and technical service (example archetype: producers with diversified fatty alcohol lines and global application support). These firms are playing to strengths in scale, regulatory compliance, and multi‑application customer relationships.
-
Oleochemical specialists emphasizing feedstock integration and sustainability credentials (example archetype: regional players leveraging palm/kernal or coconut oil chains). These companies are racing to lock in raw material supply and to certify sustainable mass‑balance grades for sensitive customers.
-
Synthetic route specialists delivering high‑purity intermediates (example archetype: firms using petrochemical Ziegler or related routes). These players are targeting high‑value industrial and pharmaceutical niches where consistency and purity trump feedstock sustainability narratives.
Recent corporate developments validate this segmentation: capacity expansions in Asia signal continued investment in oleochemical supply; sustainability certification wins in Europe point to customer demand for traceable mass‑balance grades; and new high‑purity product launches are aimed squarely at pharmaceutical and other regulated end markets. For commercial leaders, mapping competitor moves against customer sustainability and purity requirements is now table stakes.
Actionable Recommendations for 2026 Decision Makers
-
Procurement and Sourcing: Move from spot‑price exposure to a portfolio approach. Negotiate hybrid contracts that combine fixed volumes for security with indexed volumes for flexibility. Prioritize supplier audits and dual‑source plans in regions exposed to tariff shifts.
-
Product Strategy: Segment SKUs into commodity, premium, and regulated clusters. Accelerate development of high‑purity grades and certified sustainable variants for customers willing to pay a premium. Where regulatory labeling risk is high, offer reformulation support to customers.
-
Regulatory & Compliance: Invest in a regulatory dashboard and designate a cross‑functional owner to track REACH updates, U.S. state listings, and certification trajectories. Preemptive dossier updates and early supplier qualification will cut time‑to‑market and reduce downstream liabilities.
-
Manufacturing & CAPEX: Reassess brownfield upgrades that improve yield or purity rather than greenfield volume. For exporters, evaluate asset optimization to serve tariff‑favored destinations and reduce logistics friction.
-
M&A & Partnerships: Target bolt‑on acquisitions that add specialty grades, regional sourcing control, or customer application expertise. Consider tolling or JV structures to manage feedstock tightness without overcommitting capital.
What the PW Consulting Report Delivers (Practical Contents)
Our full report is structured to be execution‑ready for 2026 planning cycles. Key operational deliverables include:
-
Forward‑looking demand models by application and by region with scenario stress‑testing under alternative regulatory and commodity assumptions.
-
Supply‑side mapping that traces feedstock origins, conversion technologies, and logistics choke points — including supplier profiles and capacity change trackers.
-
Price and margin sensitivity tools that let commercial and finance teams model pass‑through, margin compression, and hedging effectiveness.
-
Regulatory and certification playbook covering EU chemical obligations, U.S. labeling exposures, and voluntary sustainability schemes — with recommended compliance timelines and resource estimates.
-
Competitive benchmarking and capability heatmaps to prioritize investment, M&A targets, and partnership candidates.
-
Go‑to‑market templates for sales teams — segment prioritization, value messages for sustainability and purity, and negotiation levers for different buyer profiles.
To preserve the strategic value of the report as a decision tool, the public summary intentionally omits the full set of segmented regional and application level datapoints. Subscribers receive these core breakdowns, along with interactive dashboards and downloadable models that allow immediate scenario testing and board‑ready slide creation.
Final Considerations — Timing and Next Steps
For executives preparing 2026 budgets and strategic plans, two short time windows matter: immediate supplier and compliance actions that must be taken in Q1–Q2 to avoid downstream disruption, and mid‑year product and investment reviews to capture opportunities arising from premium grade demand. PW Consulting recommends convening a cross‑functional steering group to run three rapid workstreams in parallel: (1) supply‑risk mitigation, (2) product & regulatory readiness, and (3) commercial value capture. These workstreams should be chartered with clear KPIs tied to margin protection and selective growth targets.
PW Consulting’s Worldwide 1‑Decanol Market report provides the empirical backbone and pragmatic templates to execute these steps. For teams that need to translate market dynamics into a 90‑day action plan or an investor‑grade strategic memo, our subscribers’ deliverables include bespoke workshops and model walkthroughs.
Discover the detailed segment tables, regional flows, and downloadable scenario models on the report landing page — they are the pieces that convert market intelligence into executable strategy for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Buruli Ulcer Treatment Market Poised for Steady Expansion at a 4.8% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Buruli Ulcer Treatment Market — Strategic Outlook and Actionable Insights for 2026
Executive summary
As global health stakeholders recalibrate priorities for neglected tropical diseases, Buruli ulcer treatment is moving from episodic reaction to structured market planning. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies a steady recovery and expansion of the treatment market, driven by guideline consolidation, procurement program continuity, and persistent endemic burden in prioritized geographies. The report projects that the market, which reached USD 78.45 Million in the base year (2025), will grow at a compound annual growth rate (CAGR) of 4.8% through the forecast period, approaching the low hundreds of millions by 2032 under the central-case scenario.
Worldwide Buruli Ulcer Treatment Market
Why this matters for 2026 decision-makers
2026 will be a pivotal year for funders, national program managers, manufacturers, and procurement platforms. Several dynamics converge to create near-term strategic inflection points:
Worldwide Buruli Ulcer Treatment Market
- Guideline stability: WHO’s recent endorsement of standardized multidrug regimens (rifampicin plus clarithromycin for an eight‑week course) reduces clinical uncertainty and enables clearer demand forecasting.
- Program funding and procurement continuity: Treatment is largely provided free through WHO‑supported national programs in endemic regions, which centralizes purchasing decisions and elevates the importance of prequalified, low-cost suppliers for continuity of care.
- Supply structure: The market remains dependent on a small set of generic manufacturers and WHO‑prequalified suppliers, translating into a mid‑range market concentration profile and tangible supplier power in sourcing negotiations.
The combination of these factors creates a predictable growth path that can be actively shaped by strategic procurement, targeted investment in supply resilience, and differentiated commercial approaches for non-endemic markets (such as specialist centers in higher‑income countries).
Worldwide Buruli Ulcer Treatment Market
Market trajectory — what the numbers tell us
Our report integrates historical data (2020–2025) and near‑term forecasts to deliver a practical picture of market momentum. From a base of USD 78.45 Million in 2025, the market is forecast to expand at a 4.8% CAGR across 2026–2032, reflecting modest but consistent growth. The trajectory reflects the dual realities of a constrained therapeutic toolbox (antibiotics, wound care, occasional surgery, and rehabilitation) and the stabilization of treatment protocols that enable scaled program delivery and better procurement planning.
For stakeholders sizing operations and capital allocation in 2026, two operational takeaways are clear: budgetary requirements will rise predictably (enabling multi‑year contracting), and the concentration of purchasing via national programs opens opportunities for negotiated long‑term supply agreements and pooled procurement platforms that can secure supply while reducing unit costs.
Competitive landscape and supplier strategy
Despite the overall small absolute market size relative to major therapeutic categories, competitive dynamics are becoming material for supply security and program resilience. The market shows moderate concentration, with the top three and top five suppliers controlling a meaningful share of supply — a structural feature that shapes pricing, availability of WHO‑prequalified options, and risk exposure for national programs.
- WHO‑prequalified suppliers (example: Macleods Pharmaceuticals) — Prequalification status remains a near‑term procurement prerequisite for large donor‑funded purchases. Macleods’ prequalification milestones underscore the strategic advantage of WHO endorsement for participating in national tenders and international procurement schemes.
- Large generics divisions (example: Sandoz) — Established generics producers can provide scale and regulatory maturity; their inclusion in national formularies eases procurement complexity in many programs.
- Specialized generics manufacturers (example: Cipla) — Manufacturers based in India remain critical given their role in producing quality, affordable antibiotic inputs. Their supply chain networks and cost structures are central to ongoing affordability in endemic regions.
For manufacturers, the strategic options in 2026 include: securing WHO prequalification where absent, pursuing long‑term framework agreements with pooled purchasers, and investing in small but high‑value services (e.g., packaging for program delivery, cold chain where relevant, or starter kits for integrated wound management) that create differentiation beyond price.
Policy, reimbursement, and program dynamics
Policy and reimbursement realities underpin the market’s architecture. The WHO’s recommendation for an eight‑week rifampicin‑clarithromycin regimen (October 2023) and the model of free treatment through WHO‑supported national programs reduce out‑of‑pocket markets while increasing the importance of reliable donor and government financing. For policy makers and donors, the 2026 decision horizon is one of choosing between continued program continuity, scaled elimination initiatives, or targeted surveillance and tertiary‑care strengthening.
- Donors and ministries: prioritize funding envelopes that enable multi‑year procurement and buffer stock generation to smooth supplier delivery variability.
- Procurement agencies: adopt supplier prequalification and performance metrics in tender design to balance cost with continuity.
- Clinical program designers: leverage the consolidated guideline to harmonize training, supply kits, and M&E frameworks that drive better patient outcomes.
Supply‑side risks and mitigation
Key operational risks for 2026 include raw material sourcing concentration, single‑source suppliers for critical fixed‑dose combinations, and limited commercial incentive for producers to expand capacity. Our analysis identifies pragmatic mitigation steps:
- Develop supplier diversification roadmaps and engage conditional contracting to incentivize capacity investments.
- Use pooled procurement and demand guarantees to reduce per‑unit costs and de‑risk manufacturer investments in small‑volume, high‑impact products.
- Integrate horizon scanning for regulatory and guideline changes into procurement cycles to avoid sudden obsolescence of product specifications.
Practical, actionable intelligence in the report
PW Consulting’s market study is designed to be operational. Key deliverables inside the full report include:
- Robust market sizing with scenarios (central, low, and high) reflecting programmatic and epidemiological uncertainty.
- Scenario‑based procurement models and contracting templates tailored for donors and national program buyers.
- Supplier capability dossiers and a prequalification roadmap that identifies realistic timelines and cost implications for manufacturers seeking WHO endorsement.
- Clinical pathway mapping that aligns guideline updates with product formulations, packaging, and logistics requirements.
- Risk heatmaps and mitigation playbooks covering raw materials, regulatory shifts, and demand volatility.
- Commercial playbooks for manufacturers and distributors, including niche market strategies for non‑endemic high‑income country centers and opportunities for value‑added services (training, bundled kits, diagnostics compatibility).
These components are presented with reproducible models and assumptions so that procurement officers and corporate strategists can re‑run scenarios using their own inputs.
Strategic recommendations for 2026 planning
For each stakeholder group — donors, national program managers, manufacturers, and distributors — the report offers concise, prioritized actions for 2026:
- Donors: formalize multi‑year funding commitments with supplier performance clauses and buffer stock financing to stabilize markets.
- National programs: adopt standardized tender specifications aligned with WHO guidelines and insist on WHO prequalification in tenders where feasible.
- Manufacturers: pursue WHO prequalification where absent, and explore differentiated service offerings rather than competing solely on price.
- Distributors and implementers: partner with clinical programs to offer bundled solutions (medication + wound care kits + training) to improve adherence and outcomes.
What we do not disclose here (and why)
Consistent with our “trailer” approach, this release intentionally highlights the strategic contours and operational implications while withholding detailed segment tables, granular regional splits, and unit‑price models. Those specific, actionable datasets — essential for bidding, budgeting, and investment decisions — are included in the full PW Consulting report and interactive data module. The withheld detail is designed to enable direct application in procurement and go‑to‑market plans, and to ensure that stakeholders using the models have access to the full methodological transparency and data provenance that underpins our forecasts.
Conclusion — how to use these insights in 2026
For decision‑makers preparing 2026 budgets and strategies, the key takeaways are straightforward: expect steady growth driven by program stability and guideline clarity; prioritize procurement design that secures supply continuity; and pursue targeted supplier engagement to mitigate raw material and concentration risks. The market’s modest absolute size belies the potential for outsized programmatic impact when procurement and clinical delivery are aligned.
Obtain the full report and data module
PW Consulting’s Worldwide Buruli Ulcer Treatment Market report contains the complete dataset, segment breakdowns, supplier scorecards, and reproducible forecasting tools that operational teams need to execute decisions in 2026. Visit our website to access the full report, request a briefing, or commission a custom scenario tailored to your procurement or investment case.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Antibody Fragments Market Set to Reach USD 22,797.7 Million by 2032, Backed by a 9.6% CAGR
By pmarketresearch, 2026-07-15
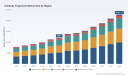
Worldwide Antibody Fragments Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive summary
Antibody fragments — including Fab, scFv and single-domain formats — are migrating from niche tools into mainstream therapeutic, diagnostic and R&D pipelines. Our new Worldwide Antibody Fragments Market report (base year 2025; historical window 2020–2025; forecast 2026–2032; revenues expressed in USD Million) shows a robust multi-year expansion at a compound annual growth rate (CAGR) of 9.6% across the forecast horizon. Total market value grows substantially from the 2025 baseline into the early 2030s, reflecting accelerating demand for smaller, modular biologics that offer tissue penetration, manufacturability advantages and differentiation in crowded biologics portfolios.
Worldwide Antibody Fragments Market
Why this preview matters for 2026 decision cycles
-
Timing: 2026 will be a pivot year for resource allocation. Biotech and pharma companies that set platform bets, manufacturing footprints and partnership strategies early in 2026 will capture outsized share of the next growth phase.
Worldwide Antibody Fragments Market -
Capital discipline: With elevated R&D and CMC costs specific to fragment formats, executives need a short list of de-risking levers — from targeted external collaborations to focused in-house process development — to preserve margins while scaling.
Worldwide Antibody Fragments Market -
Regulatory readiness: Fragment therapeutics are treated as biologics by regulators; preclinical and clinical development paths are rigorous. Proactive regulatory planning reduces time-to-market and competitive uncertainty.
Market trajectory — the big-picture numbers
Our modelling — based on historical performance (2020–2025) and forward-looking adoption curves — projects substantial expansion through 2032. The market baseline in 2025 anchors investment decisions for 2026 and beyond; the forecast period (2026–2032) reflects steady double-digit opportunity across therapeutic, diagnostic and discovery segments. Market concentration is moderate: the top three players account for a meaningful portion of revenue (CR3 ≈ 42.5%), and the top five approach majority share (CR5 ≈ 58.8%), underscoring both incumbent strength and room for specialist entrants.
Segment dynamics — what matters and what we hide (intentional)
Fragment formats are heterogeneous: each offers trade-offs across potency, half-life, manufacturability and IP. Our full report provides granular splits and subsegment revenue trajectories; here we surface the critical commercial drivers that will shape capitalization plans in 2026 without disclosing proprietary subsegment numbers.
-
Therapeutic momentum: Clinical pipelines and recent approvals validate fragment modalities' value proposition in indications requiring deep tissue penetration or rapid tissue clearance. However, clinical success alone does not guarantee commercial viability — COGS and pricing dynamics will decide margin sustainability.
-
Diagnostics and research uptake: Fragments' smaller size and modularity make them attractive in diagnostic reagents and research reagents markets, with commercial models that differ materially from therapeutics (shorter development cycles, volume-based economics).
-
Manufacturing and cost profile: The absence of an Fc domain eliminates Protein A affinity capture, often necessitating multi-step purification (ion exchange, hydrophobic interaction chromatography and other polishing steps). That operational reality can raise manufacturing costs substantially versus full-length monoclonal antibodies and must be factored into go/no-go investment decisions.
Competitive landscape — incumbents, challengers and service partners
The competitive map combines large integrated pharmas with specialist service providers and platform companies. Incumbents leverage scale, global regulatory teams and established commercial channels; nimble players focus on platform differentiation (e.g., nanobody technology, bespoke expression systems) and CMC innovations.
-
Large pharmas (examples included in our analysis): Established firms are integrating fragment formats into broader biologics portfolios, using their clinical and commercialization muscle to bring fragment-based drugs through late-stage trials and to market. Their strategic moves include platform investments and targeted acquisitions.
-
Platform leaders: Companies with proprietary single-domain antibody platforms are emphasizing tissue penetration and manufacturability in their value propositions. Ongoing platform advancements — including those publicly announced in 2025 — indicate continued prioritization of next-generation fragment therapeutics.
-
CMO / CDMO and service specialists: Firms offering optimized expression systems (mammalian and microbial), stabilization technologies and custom production services are critical enablers. Investment in modular production capacity and fragment-specific purification know-how is an attractive partner strategy for sponsors aiming to shorten technical timelines.
Recent developments to watch
-
Platform acceleration: Major platform announcements in 2025 show sustained promotional activity by platform owners positioning single-domain technologies as next-gen therapeutics with manufacturing and clinical benefits.
-
Partnership proliferation: Early-2025 partnership expansions and milestone-driven collaborations underscore a trend toward distributed R&D models — sponsors outsource early discovery and some lead optimization to specialists to reduce fixed cost exposure.
-
Academic and industry synthesis: Reviews published in 2025 synthesize industrialization progress for nanobodies and related formats, highlighting evolving IP landscapes and clinical pipelines that will influence licensing and M&A activity.
Manufacturing, CMC and supply chain considerations
Manufacturing choices are among the highest-impact decisions for 2026. Key considerations we model and recommend:
-
Expression platform selection: Microbial systems (e.g., E. coli, Pichia pastoris) can deliver cost and yield advantages for certain fragments and have demonstrated optimized fed-batch yields in industry reports. Mammalian (CHO) systems remain necessary for complex constructs or when post-translational modifications drive function.
-
Purification strategy: The lack of Fc-driven Protein A capture commonly forces multi-step purification schemas. Our scenario analyses show this can increase manufacturing cost by up to ~60% compared with full monoclonal antibodies unless offset by platform-specific innovations.
-
Half-life engineering trade-offs: PEGylation, albumin-binding tags or Fc fusions extend in vivo persistence but materially increase COGS. Our modelling quantifies margin erosion scenarios for high-volume, price-sensitive indications — a critical consideration for 2026 portfolio prioritization.
Regulatory, reimbursement and commercial pathways
Antibody fragments are regulated as biologics and require comparable preclinical, clinical and post-market evidence. From a commercial standpoint, pricing strategies must account for higher COGS in many configurations, and payer acceptance will hinge on clear value demonstrations (efficacy, safety, dosing convenience). For 2026 planning, sponsors should:
-
Integrate health economics early into clinical design to support reimbursement dossiers.
-
Engage regulatory authorities proactively to align nonclinical and CMC expectations for fragment formats.
-
Model pricing scenarios that reflect both premium indications and volume-sensitive diagnostic/research markets.
What the PW Consulting report delivers (practical contents)
Our full report is built as an operational playbook for 2026. Key deliverables include:
-
Top-line market forecasts (2026–2032) with sensitivity cases and scenario stress tests.
-
Competitive profiles and capability matrices for incumbents, platform owners and CDMOs — highlighting R&D pipelines, manufacturing footprints and strategic intent.
-
Actionable CMC roadmaps and cost modelling templates to quantify trade-offs between expression systems, purification strategies and half-life extension techniques.
-
Regulatory pathway decision trees and reimbursement modelling frameworks calibrated to fragment-specific risks and evidence requirements.
-
M&A, licensing and partnership playbooks with prioritized targets and value-capture scenarios tuned for 2026 execution windows.
How to use this intelligence in 2026 — recommended moves
-
Prioritize platform bets by aligning scientific advantage with commercial pathway: commit to formats where clinical differentiation aligns with sustainable manufacturing economics.
-
Pursue staged externalization: mitigate upfront capital by partnering with service providers for early-phase production while retaining strategic control of late-stage manufacturing decisions.
-
Invest in CMC innovation: targeted investment in purification, stabilization and half-life engineering can unlock margin expansion and competitive advantage.
-
Align payer strategy with development: integrate health economics and real-world evidence generation plans into phase II/III designs to accelerate reimbursement acceptance.
-
Monitor IP and platform developments closely: platform advances and partnership flows announced in 2024–2025 indicate where licensing competition will be fiercest in 2026.
Conclusion — the strategic inflection is now
The antibody fragments market is at an inflection point. Our forecasts show a materially larger market beyond 2026, but the winners will be those who translate technical advantages into manufacturable, reimbursable products within disciplined cost frameworks. PW Consulting’s report equips leadership teams with the forecast granularity, competitive mapping and implementation tools required to make high-confidence, time-sensitive decisions in 2026.
Next steps
For executives preparing 2026 budgets and strategic plans: request the full Worldwide Antibody Fragments Market report for complete subsegment data, regional breakdowns and the proprietary models that underpin our forecasts. The full intelligence pack includes downloadable modelling workbooks and an executive briefing option to translate findings into a 90-day action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Carob Chocolate Bars Market to Grow at 7.2% CAGR, Approaching USD 350 Million by 2032
By pmarketresearch, 2026-07-15
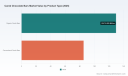
Carob Chocolate Bars Market: Strategic Playbook for 2026 Decision-Makers
PW Consulting’s latest market study on Carob Chocolate Bars delivers a clear, executable line of sight for executives planning portfolio moves in 2026. Built on a 2020–2025 historical base and projecting through 2032, the study quantifies a robust growth pathway (2025 market size: USD 215.0 Million; forecast CAGR: 7.2% through 2032), and—more importantly—translates that trajectory into practical options for product, channel, and M&A strategies. This release highlights the study’s strategic value, explains where competitive advantage will be won, and outlines immediate actions that can be piloted this year. For full subsegment tables, granular regional splits, and downloadable financial models, readers are invited to consult the complete report on PW Consulting’s site.
Carob Chocolate Bars Market
Why 2026 Is a Pivotal Year
-
Macro momentum: The category is well beyond niche status. The mid‑2020s have shifted carob from alternative curiosity to a credible mainstream adjunct to mainstream chocolate alternatives, driven by dietary trends and ingredient innovation. The model projects consistent expansion through 2032, with accelerating uptake tied to improved sensory profiles and scaled ingredient solutions.
Carob Chocolate Bars Market -
Competitive inflection points: Leading boutique brands and ingredient specialists are moving from artisanal supply to scalable retail execution. Recent retailer listings and ingredient launches demonstrate that product-market fit is transitioning into routinized market growth—creating windows for scale players and selective investors in 2026.
Carob Chocolate Bars Market -
Decision urgency: For manufacturers, private labels, ingredient suppliers, and health-retail buyers, decisions taken in 2026 on sourcing, formulation, and channel strategy will determine who captures the low‑friction consumer conversions over the next five years.
What the PW Consulting Report Delivers: Operationally Useful Intelligence
This is not an academic compendium. The report was designed to be a playbook for commercial teams, product leads, and corporate strategists. Key practical deliverables include:
-
Commercial forecasting models calibrated to multiple go-to-market scenarios (base, premiumization, and value) with sensitivity levers you can adjust for pricing, ingredient cost, and distribution mix.
-
Granular retailer engagement templates and assortment rationales tailored to health‑focused channels, mainstream grocery, and direct‑to‑consumer strategies—ready to be adapted into pitch decks.
-
Supply‑chain risk matrix and procurement playbook covering sourcing routes, inventory buffers for seasonality, and cost mitigation tactics—especially relevant where carob pod export/import spreads create pressure on COGS.
-
Product roadmaps and formulation briefs that bridge sensory uplift (taste & texture) with clean‑label positioning, sugar reduction targets, and functional claims—aligned to the emerging ‘prebiotic’ opportunities from carob-derived ingredients.
-
Regulatory checklist and labeling templates keyed to cross‑border trade in plant‑origin food products, minimizing time-to-shelf friction in target markets.
-
Investment thesis frameworks and M&A scorecards to evaluate bolt‑on acquisitions, strategic partnerships, or co-manufacturing arrangements for rapid scale.
Market Dynamics: Where Growth Is Coming From
Three structural dynamics are driving the category’s 7.2% CAGR:
-
Health and clean‑label migration: Consumers seeking vegan, dairy‑free, and lower‑sugar options are receptive to carob’s positioning. PW Consulting’s sensory benchmarking shows that many carob formulations are marketed with substantially lower sugar than conventional chocolate equivalents, a point of advantage in retailer health assortments.
-
Ingredient innovation: New ingredient launches and academic research have improved flavor fidelity and functional credentials (e.g., prebiotic fibers derived from carob). These developments reduce the historical tradeoff between taste and health, opening broader buyer segments.
-
Channel evolution: Health retail, specialty stores, and targeted online channels continue to incubate the category, while selective mainstream listings are expanding trial and availability—creating a hybrid growth model of niche-to-mass diffusion.
Competitive Landscape: Who’s Shaping the Category
The market remains fragmented—dominated by focused specialists rather than consolidated incumbents—creating tactical opportunities for both nimble brand builders and strategic acquirers. Noteworthy competitive behaviours identified in the study include:
-
Missy J’s (Colorado, USA): Leverages regional sourcing stories and strong organic/vegan credentials. Their strength is brand authenticity and product breadth across snacks and confectionery formats—useful for companies considering portfolio extension strategies.
-
The Carob Kitchen (South Australia): Farms-to-bar integration and multiple sugar‑profile SKUs illustrate a defensive strategy: control upstream input quality while offering differentiated formulations to address varied consumer taste points.
-
Caroboo (UK): Active retailer expansion—recently securing listings in major health retail channels—shows the commercial payoff of focused trade partnerships and shelf visibility in the health channel.
-
CarobMe/Carobō (Australia & international), D&D Chocolates (UK), Carob World (Portugal), and The Australian Carob Co.: Together, these players display a spectrum of approaches—ingredient development, sustainability narratives, compostable packaging, and co-manufacturing models—that are shaping adoption pathways in different markets.
PW Consulting’s competitive profiles include capability matrices, cost‑to‑serve estimates, and distribution playbooks for each of these players—tools that acquirers and retail buyers can use to prioritize targets or suppliers.
Recent Signals That Matter for 2026 Strategy
-
Retail expansion wins: Recent listings in national health-retail chains validate that buyer demand is maturing—an important signal for scale-up timing.
-
Academic and ingredient innovation: Flavor-enhancement techniques and the introduction of prebiotic carob ingredients materially change the product development calculus; companies that quickly integrate these techniques will reduce the category’s sensory tradeoffs and accelerate mainstream acceptance.
-
Raw material pressure: Price and export/import spreads for carob pods and processed carob ingredients are an active factor in margin planning. Procurement strategies and supplier diversification will be necessary to protect gross margins as footprints expand.
Strategic Recommendations for 2026
We translate the analysis into a prioritized set of actions for different player archetypes. Each recommendation is accompanied in the full report by implementation templates and expected ROI timelines.
-
For Brand Owners: Pilot a two‑tier roadmap—retain a core clean‑label/health line while launching a taste‑optimized premium SKU that leverages recent flavor‑enhancement techniques. Use retailer pilots to test pricing elasticity and levers for rapid scaling.
-
For Ingredient Suppliers: Accelerate commercialization of functional ingredients (e.g., prebiotic fractions). Build co‑development agreements with early adopter brands and offer sensory proof‑points to lower manufacturer adoption barriers.
-
For Retailers: Adopt a staged assortment approach—trial limited listings in high‑traffic health channels while monitoring conversion and repeat purchase rates. Consider private label partnerships where supply security and margin capture align.
-
For Investors and M&A Teams: Target bolt‑ons that provide either upstream integration (supply security) or rapid access to retail lists and production capacity. Our M&A scorecard ranks targets by strategic fit and integration risk.
Risk Management and KPIs
Key risks are supply volatility, sensory acceptance, and regulatory labeling frictions for cross‑border sales. PW Consulting’s dashboard prescribes a concise KPI set to monitor performance and flag rapid course corrections:
-
Sales funnel metrics: trial-to-repeat conversion, SKU velocity in new retail listings, and online conversion rates by creative variant.
-
Supply indicators: lead-time variance, seasonal pod availability, and cost-per-kilo delta versus baseline procurement models.
-
Product health metrics: rate of returns or complaints tied to taste/texture, and percentage of SKUs meeting targeted sugar-reduction thresholds.
How to Use This Intelligence Now
Start with rapid diagnostic workshops that map your organization against the playbook’s maturity stages (incubation, scale, consolidation). Within 60–90 days you can implement low-cost pilots—one consumer taste-study using improved flavor techniques, one procurement hedging trial, and one retailer assortment test—each with clear success thresholds defined in the report.
The full PW Consulting Carob Chocolate Bars Market Report contains the detailed subsegment economics, regional demand matrices, SKU-level pricing bands, and downloadable financial models required to execute the above actions. The report intentionally reserves core subsegment tables and buyer-level data to the full publication to support proprietary decision processes and preserve commercial value for subscribers.
Final Thought
Carob is not an overnight revolution—but it is on a reproducible growth trajectory. With a clear framework for product improvement, ingredient partnerships, and channel activation, 2026 offers a strategic launch window: organizations that combine sensory uplift with clean‑label positioning and supply resilience will capture disproportionate share as the category expands. PW Consulting’s study gives you the roadmap to convert the projected market growth into concrete commercial outcomes. For the full dataset, playbooks, and templates, consult the complete report.
For detailed analysis of this topic, please visit the official page: Carob Chocolate Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Natural Gelling Agent Market to Grow at a 6.42% CAGR Through 2032
By pmarketresearch, 2026-07-15
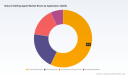
Worldwide Natural Gelling Agent Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market intelligence on the Worldwide Natural Gelling Agent market synthesizes five years of observed momentum (2020–2025) with a rigorous forecast through 2032. Built for commercial executives, innovation leaders, and M&A teams, this executive preview explains why the natural gelling agent landscape will be a strategic battleground in 2026 and how leading companies can convert macro growth and structural risks into durable advantage.
Worldwide Natural Gelling Agent Market
Why this market matters in 2026
The market has demonstrated steady expansion from an estimated USD 6,712.45 million in 2020 to USD 9,132.40 million in the base year (2025). Our modelling points to continued, predictable growth — a compound annual growth rate (CAGR) of 6.42% — that drives the global market toward approximately USD 14,117.17 million by 2032. For commercial teams planning 18–36 month investment cycles, those numbers translate into both incremental revenue pools and capacity-planning imperatives: predictable scale, yet with enough tail-risk from raw material and regional supply concentration to require proactive strategy.
Worldwide Natural Gelling Agent Market
Key forces shaping the market in 2026
- Sustained end-market demand with product premiumization. Food & beverage formulation trends (clean-label, plant-based, reduced sugar/fat) continue to lift demand for naturally derived hydrocolloids and gelling agents. Premiumization in pharmaceuticals and personal care also creates higher-margin opportunities for purified and specialty grades.
- Supply-side concentration and raw-material volatility. Seaweed-derived inputs that underpin carrageenan and alginate remain geographically concentrated in Asia–Pacific, exposing supply to weather, harvest cycles, and geopolitics. We are already observing price pressure on carrageenan in early 2026 and historic episodes of alginate price spikes tied to brown-seaweed availability.
- Consolidation and capability stacking. The sector shows a move from pure-ingredient suppliers to integrated ingredient platforms that combine sourcing, formulation services, and regulatory expertise. This consolidation affects price dynamics, innovation velocity, and customer switching costs.
- Regulatory and trade tailwinds/uncertainties. Recent policy changes (for example, exemptions on select chemical tariffs in the US in 2025) temporarily ease cost pressure for imported inputs, but companies must track evolving trade measures and local regulatory approvals for food and pharma ingredients.
- Sustainability and traceability as commercial differentiators. Buyers increasingly pay premiums for verified sustainable sourcing (e.g., responsible seaweed harvesting, circular sourcing of citrus peel for pectin). Firms that can demonstrate traceable, low-carbon supply chains will gain shelf-space and contract advantages.
What PW Consulting’s report delivers — practical, decision-ready content
Our full market study is designed as an operational toolkit, not just a desk-reference. Key deliverables include:
Worldwide Natural Gelling Agent Market
- Top-down market sizing and reconciled historical series (2020–2025) with transparent methodology and sensitivity checks against price and volume scenarios.
- Forward-looking forecast (2026–2032) using scenario modelling that isolates demand drivers (e.g., food reformulation trends), supply-side constraints (raw-material cycles), and macroeconomic sensitivity.
- Supply-chain risk maps and a raw-material price tracker that flags structural vulnerabilities (seaweed concentration, seasonal harvest risks, and substitution dynamics) and recommends hedging and sourcing tactics.
- Competitive benchmarking and capability matrices for leading suppliers covering plant footprints, technology capabilities, specialty grades, and go-to-market positioning.
- Commercial playbooks with 12- to 36-month actions: route-to-market options, co-development models with food manufacturers, vertical integration scenarios, and price-capture strategies during tightening cycles.
- M&A and partnership heatmaps including likely targets for bolt-on acquisitions, strategic JV structures, and integration risk templates to preserve value post-deal.
- Regulatory and sustainability trackers focused on food, pharma, and cosmetics approvals; certification pathways for sustainable sourcing; and packaging/labeling implications for clean-label claims.
Competitive landscape — who matters and why
The sector is moderately concentrated: the top three players control a meaningful share of the market, and the top five widen that share materially. This level of concentration creates both barriers and opportunities — barriers through scale and customer relationships, opportunities through divestment and partnership plays as larger firms optimize portfolios.
Prominent industry participants profiled in the report include global ingredient leaders and specialized hydrocolloid manufacturers. Our strategic assessment of these players highlights where value is being created and where gaps remain:
- Cargill, Incorporated — Strength: diversified hydrocolloid portfolio and investments in pectin capacity to serve food customers. Strategic implication: best positioned to support large-scale CPG reformulation programs; smaller rivals should look for niche specialty grades or service differentiation.
- CP Kelco (now part of Tate & Lyle) — Strength: specialty hydrocolloids and technical application support. Strategic implication: the CP Kelco acquisition amplifies Tate & Lyle’s capability to supply pectin and specialty gums — expect intensified competition in premium food applications and targeted pricing pressure in commodity grades.
- Tate & Lyle plc — Strength: ingredient platform scale and distribution reach. Strategic implication: platform consolidation will push peers to secure proprietary formulations or service-led differentiation.
- Kerry Group plc — Strength: application development and clean-label solutions for food & beverage customers. Strategic implication: Kerry will continue to be a preferred partner for CPGs prioritizing speed-to-market for reformulated SKUs.
- Ingredion, ADM, Ashland, DuPont/IFF — Strengths: broad ingredient portfolios and global customer relationships. Strategic implication: these players compete on integrated solutions (starches + gums) and offer scale advantages in supply continuity.
- Specialists such as GELITA, Rousselot, Jungbunzlauer, Herbstreith & Fox, FMC, Gino Gums & Stabilizers, AEP Colloids — Strengths: product specialization (gelatin, xanthan, pectin, carrageenan) and technical purity. Strategic implication: specialists remain attractive partners for premium, regulated applications (pharma, nutraceuticals) and as M&A targets for scale players.
Recent industry moves to monitor in 2026
- Tate & Lyle’s acquisition of CP Kelco (completed mid‑2024) materially changes the competitive map for specialty gums and pectin — expect integration-related synergies, portfolio rationalization, and targeted capacity realignment.
- Capacity investments continue: Jungbunzlauer’s announced build‑out of a North American xanthan facility signals new regional supply options and local sourcing advantages for North American formulators.
- Major producers have also increased production footprint in key origin regions (for example, pectin capacity expansions in South America) to diversify sourcing and reduce lead times for global customers.
- Raw-material signals: carrageenan saw upward price pressure in early 2026 due to tightening red seaweed supply, while sodium alginate experienced earlier price spikes tied to brown seaweed availability — these dynamics have direct implications on formulation economics and contract negotiations.
Actionable strategic guidance for 2026
For companies making resource allocation decisions in 2026, the choices fall into three clear, mutually reinforcing pillars:
- De-risk supply and secure margin. Negotiate multi‑year supply agreements with staggered volumes, invest in alternative sourcing (geographic and species diversification), and evaluate small-scale in-region processing to reduce freight and tariff exposure.
- Differentiate through formulation and services. Move up the value chain with co-developed, application-specific systems (reformulation toolkits, clean‑label blends, shelf-life extension systems) that command premium pricing and increase switching costs for customers.
- Use M&A and partnerships selectively. Pursue bolt-on acquisitions to close capability gaps (specialty grades, purification technology, regional production) and form JVs with raw-material suppliers to secure feedstock access under preferred commercial terms.
What we recommend you read in the full report
The full PW Consulting study contains the detailed segment breakouts, regional maps, company scorecards, and actionable playbooks that will support rapid, evidence-based decisions in 2026. To preserve strategic opportunity and encourage evidence-led engagement with our clients, this public preview omits granular regional, type and application split tables; those precise segment level breakdowns are available in the full report download and by request to our advisory team.
Concluding perspective
The natural gelling agent market is large, growing, and increasingly strategic to food, pharma and personal‑care supply chains. With an expected CAGR of 6.42% over the forecast window and an expanding revenue base that approaches the low‑ten‑billions (USD millions) by the end of the decade, 2026 is a pivotal year to align procurement, innovation and corporate development plans. The right combination of supply de‑risking, product differentiation, and targeted M&A will determine which companies capture the highest-margin segments and which will be forced into transactional competition.
For companies preparing budgets, capital plans, and customer‑facing innovation roadmaps in 2026, the evidence is clear: act now to secure feedstock resilience and accelerate service-oriented differentiation. PW Consulting’s full report equips leaders with the data, scenario models, and playbooks needed to translate these strategic imperatives into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Gelling Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fleet Maintenance Service Market Poised to Reach USD 358,110 Million by 2032, Driven by a 5.11% CAGR
By pmarketresearch, 2026-07-15
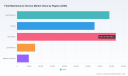
Worldwide Fleet Maintenance Service Market: Strategic Imperatives for 2026 — PW Consulting Insights
As fleet operators, OEMs, and service providers prepare budgets and strategic roadmaps for 2026, PW Consulting’s latest Worldwide Fleet Maintenance Service Market report offers targeted intelligence designed to shape decisive action. Our analysis combines a multi-year historical lens (2020–2025), a detailed 2026 baseline, and scenario-driven forecasts through 2032 to translate macro trends into executable choices. The market is growing at a steady compound annual growth rate (CAGR) of 5.11% and reached USD 252,480 Million in 2025, making maintenance strategy a material line item for operators and suppliers alike.
Worldwide Fleet Maintenance Service Market
Why this report matters for 2026 decision-makers
2026 is a pivot year for commercial fleet economics. Technology inflection points (AI, cloud telematics, predictive diagnostics) intersect with tighter regulatory scrutiny and persistent labor market constraints. That combination compresses time-to-value for maintenance investments while increasing the penalties for lagging behind peers. Our work is explicitly structured to help executives answer three strategic questions:
Worldwide Fleet Maintenance Service Market
- Where should limited capital be deployed to maximize uptime and reduce total cost of ownership (TCO) over a 3–5 year horizon?
- Which partnerships, platform capabilities, and service models materially improve resilience against compliance and labor volatility?
- How should procurement and M&A teams prioritize targets to gain near-term operational leverage without overpaying in a highly fragmented supplier landscape?
Snapshot: size, growth and market structure
PW Consulting’s base-year modeling places the global fleet maintenance services market at USD 252,480 Million in 2025, with an anticipated step-up in demand in 2026 consistent with a 5.11% CAGR through our forecast window. Importantly, concentration metrics show a highly fragmented supply base — the top three providers account for only a low double-digit share, and the top five remain below 20%. For decision-makers, fragmentation signals both opportunity (partnerships, roll-up strategies) and risk (inconsistent service quality, variable pricing).
Worldwide Fleet Maintenance Service Market
Drivers redefining maintenance economics in 2026
- Technology adoption compressing reactive cycles. Advances in telematics, diagnostics, and AI-enabled service advisors are accelerating the shift from corrective to predictive and condition-based maintenance. Early adopters report measurable reductions in unplanned downtime and parts spend per mile.
- Labor and skills scarcity. Technician shortages and higher wage expectations continue to lift labor rates; fleets are deploying tools and revised compensation models to retain talent and stabilize repair throughput.
- Regulatory tailwinds creating enforcement and cost pressures. Notable regulatory changes — including state-level inspection reforms and federal enforcement updates — are changing compliance workflows and increasing the administrative burden on maintenance operations. Targeted programs for emissions and safety impose recurring costs and reroute maintenance priorities.
- Commercial models and service delivery innovation. Mobile on-site repairs, subscription-style maintenance programs, and integrated leasing-plus-maintenance offerings are diffusing across market segments, shortening procurement cycles for bundled services.
Regulatory and compliance dynamics to watch closely
Regulatory shifts in 2025–2026 affect not only the frequency and scope of required inspections but also the economics of managing non-compliance. For example, several state-level inspection reforms have recalibrated inspection cadence for lighter assets while retaining stricter oversight for heavy vehicles. At the federal level, the FMCSA’s 2026 CSA overhaul separates vehicle maintenance into new categories — a move that directly impacts how fleet operators must document and close work orders. Additionally, targeted regional programs for emissions compliance introduce per-asset recurring costs and associated retest downtime that should be factored into lifecycle budgeting.
Competitive landscape: capability maps and strategic playbooks
The maintenance services ecosystem spans software-first platforms, telematics incumbents, traditional full-service providers, and mobile maintenance specialists. Key market participants profiled in our report include cloud-native fleet platforms, global telematics vendors, connected-operations specialists, and full-service providers with national footprints. Each offers differentiated strengths:
- Cloud fleet platforms emphasize maintenance workflows, inspections, and AI-enabled service advisories that accelerate repair approvals and cost control.
- Telematics and connected-operations providers deliver diagnostic depth, open-platform analytics, and marketplace integrations that augment predictive maintenance capability.
- Full-service fleet operators and leasing firms combine on-site maintenance networks, telematics integration, and lifecycle management to offer turnkey maintenance outsourcing.
- Technology-enabled mobile service firms focus on convenience and rapid response, creating hybrid models between traditional repair networks and digital-first platforms.
Recent product and commercial developments underscore accelerating competitive intensity. For example, several leading platform vendors launched or piloted AI-powered service advisory features and integrated fleet platforms in 2025–2026, while telematics firms introduced advanced camera solutions and expanded diagnostics—moves that compress the differentiation window for first movers.
What’s inside the PW Consulting report (operational detail without revealing proprietary splits)
Our report is structured to be operationally actionable for C-suite and delivery teams. Highlights include:
- Proprietary macro model and demand-supply scenarios calibrated from 2020–2025 and extended through 2032, allowing clients to run upside/downside cases.
- Vendor capability matrix and supplier scorecards that benchmark product, service, geographic reach, technology stack, and commercial models.
- Segment playbooks — fleet size cohorts, vehicle-type considerations, and service-type strategies — with procurement clauses, KPI templates, and SLA examples.
- Technology decision framework detailing ROI calculations for telematics, AI diagnostics, and mobile service enablement across different fleet profiles.
- M&A and partnership playbook with diligence checklists, valuation sensitivities, and integration risk checklists for roll-ups and capability buys.
- Regulatory impact maps and compliance-cost calculators that quantify the operational effect of recent inspection reforms and emissions programs.
We intentionally withhold detailed region-/application-level splits and contract-level pricing from this summary to preserve the report’s value as a primary research product. Subscribers receive the full set of tables, downloadable models, and comparative vendor scorecards.
Strategic recommendations for 2026 (prioritized)
- Prioritize diagnostic depth over feature breadth. Investing in platforms and integrations that provide reliable fault codes and telematics-derived prognostics delivers faster TCO payback than broad, under-integrated suites.
- Make technician retention a strategic imperative. Reallocate a portion of planned technology savings to workforce stability — higher technician pay bands and structured upskilling preserve throughput and quality.
- Revisit service contracts with a compliance lens. Re-negotiate SLAs to include compliance-driven inspection support and retest allowances; factor in recurring program fees and test downtime when assessing pricing.
- Design a hybrid delivery model. Combine centralized predictive analytics with decentralized mobile repair capacity to optimize both asset uptime and total repair cost.
- Use M&A selectively to acquire capability, not just scale. Target tuck-ins that fill gaps in AI diagnostics, mobile maintenance coverage, or parts-supply resilience rather than broad geographic roll-ups alone.
- Implement a two-track pilot plan. Run a rapid 6–9 month predictive-maintenance pilot alongside a workforce transformation program to validate assumptions before scaling.
How PW Consulting helps
Clients leveraging PW Consulting’s dataset and advisory services typically use our outputs to:
- Accelerate vendor selection with side-by-side scorecards and negotiated commercial templates.
- Model program economics at the asset level to inform capex vs. opex decisions.
- Support M&A underwriting with integrated operational and market risk scenarios.
- Build compliance-ready maintenance playbooks that translate regulatory changes into shop-floor checklists.
Final note: what to do next
For 2026, the margin between fleets that gain market advantage and those that merely protect status quo will be defined by choices on telematics integration, technician economics, and compliance orchestration. PW Consulting’s Worldwide Fleet Maintenance Service Market report equips leaders with the models, vendor evaluations, and scenario playbooks to make those choices confidently. To access the full dataset, regional and service-type breakdowns, vendor scorecards, and downloadable financial models, request the complete report and supporting deliverables through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Fleet Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com