

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Military Two-person Rotorcraft Market to Reach USD 12.73 Billion by 2032 at a 4.35% CAGR

Worldwide Military Two-person Rotorcraft Market — Strategic Insights for 2026 Decision-makers
Executive summary
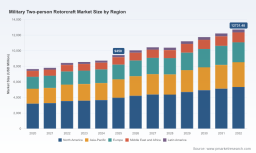
PW Consulting’s latest market study on the Worldwide Military Two-person Rotorcraft Market positions 2026 as an inflection year for procurement, industrial strategy, and alliance-driven R&D. Using 2025 as the report’s base year, the market expanded from approximately USD 7,650.4 Million in 2020 to USD 9,450.0 Million in 2025. Our modelling forecasts a near-term market size of roughly USD 10,052.2 Million in 2026 and projects growth to about USD 12,731.5 Million by 2032, implying a compound annual growth rate (CAGR) of 4.35% across the 2026–2032 forecast window. Market concentration is material: the top three OEMs account for a majority share (CR3 = 58.4%) and the top five command an even larger portion (CR5 = 76.2%), creating strategic implications for competition, supplier leverage, and national procurement policy.
Worldwide Military Two-person Rotorcraft Market
Why this report matters in 2026
Decision timelines for military rotorcraft are long and capital-intensive. 2026 will see programs transition from capability-definition into contracting and early production for several operators; simultaneously, NATO-aligned Next Generation Rotorcraft studies are shaping medium-lift requirements for the 2035+ timeframe. This creates a two-speed environment: immediate modernization and force-mix optimization versus long-horizon platform development. Our study translates that duality into actionable choices for defense ministries, OEMs, tier‑1 suppliers, and financial sponsors.
Worldwide Military Two-person Rotorcraft Market
What the report delivers (practical, actionable content)
- High-fidelity market sizing and a demand-by-year model calibrated to 2020–2025 historicals and forecasts through 2032, presented in constant USD (base year 2025).
- Scenario-based outlooks: three demand scenarios (baseline, accelerated modernization, and constrained spending) with sensitivity testing against defense budget trajectories and geopolitical shocks.
- Competitive landscaping that profiles incumbent two-person rotorcraft OEMs, their platform families, export footprints, and near-term product developments.
- Procurement playbooks for armed forces and acquisition authorities that convert capability requirements into procurement lot-sizing, risk mitigation clauses, and in-service support (ISS) contracting options.
- Supply-chain heatmaps and cost-driver analysis that quantify exposure to raw-material volatility (notably titanium and composite feedstocks) and to long lead times in advanced composite production.
- Transaction and partnership guidance: valuation comparators, M&A targets, and JV structures tailored for quick-time-to-market technology insertion (avionics, weapons integration, and mission systems).
- Implementation tools: an executive dashboard template, a supplier due-diligence checklist, and a phased integration roadmap for adopting modular mission packages and digital-enabled sustainment.
Key industry dynamics shaping 2026 strategies
- Program timing and NATO NGRC: The NATO Next Generation Rotorcraft Capability workstream has advanced concept studies and is influencing medium-lift roadmaps; early concept awards and OEM-led collaborations are already shifting R&D priorities toward compound and high-speed architectures.
- Supply-chain strain on advanced materials: Aerospace titanium demand continues to rise (the broader aerospace titanium market was estimated at around USD 3.1 billion in 2025 and showed further growth into 2026), while composite manufacturing constraints are identified as a multi-year bottleneck for scaling production of modern rotorcraft airframes and rotor assemblies.
- Consolidation and supplier power: A concentrated OEM market (high CR3/CR5) increases the bargaining position of leading manufacturers for large bilateral deals, but it also surfaces opportunities for niche suppliers and systems integrators to capture aftermarket and missionization revenue.
- Procurement behavior: Buyers are favoring flexible, modular platforms that can be rapidly reconfigured for ISR, light-attack, and training roles to maximize fleet utility and lower through-life costs.
Competitive landscape — what to watch
Our competitive review focuses on the principal platform providers and their strategic postures:
Worldwide Military Two-person Rotorcraft Market
- Airbus Helicopters (Marignane, France): A clear leader in light and multi-role two-crew platforms with active contract momentum in Europe. Recent program activity includes exercised options and new orders for light combat variants, alongside public concept work in collaboration with partners on next-generation rotorcraft concepts.
- Bell Textron (Fort Worth, USA): Positions light single- and twin-engine platforms into training and forward-area utility roles; its footprint in export training fleets makes it relevant for countries seeking lower-cost entry points into rotary training modernization.
- Leonardo Helicopters (Rome, Italy): Maintains strength in light twin multi-role rotors and trainer/utility types, often pairing avionics and mission systems to win modular capability contracts.
- Russian Helicopters / Rostec (Moscow, Russia): Continues to field dedicated two-seat attack and reconnaissance rotorcraft with designs oriented for anti-armor and battlefield support missions; geopolitical considerations influence market access and aftermarket services.
- Boeing (Arlington, USA): Anchored by heavy attack/tandem-crew designs in allied force inventories; platform modernization and avionics refresh programs remain a core part of sustainment and upgrade opportunities.
Recent company-specific events in late 2025–early 2026 illustrate tactical positioning: a European operator exercised options to expand a light combat helicopter fleet; a major OEM unveiled next-generation rotorcraft concepts in collaboration with missile and systems suppliers; and significant national orders for light combat helicopters were announced. These moves underscore a near-term emphasis on light/medium capability refresh and mid-term investment in NGRC-class technologies.
Strategic recommendations for 2026 (by stakeholder)
- Procurement authorities: Prioritize modularity clauses and production-rate flex options in contracts. Structure multi-year buys into initial tranches with clear industrial participation incentives to preserve sovereign sustainment capacity. Use our scenario models to stress-test lot-sizing against budget uncertainty.
- OEMs: Protect production continuity by investing in alternative suppliers for critical materials (titanium and advanced composites) and by diversifying composite-processing capabilities through partnerships or captive facilities. Accelerate modular mission-package development to capture expansion opportunities in ISR and light-attack roles.
- Tier‑1 and systems integrators: Focus on open-architecture mission systems and retrofit kits that extend legacy two-person platforms. Offer bundled sustainment contracts using predictive-maintenance analytics to lock in recurring revenue streams.
- Investors and PE: Look for carve-outs in aftermarket spares, missionization electronics, and composite-processing facilities. Valuations should account for concentration risk (high CR3/CR5) but also for defensible niche positions.
- Allied R&D consortia: Leverage collaborative R&D to de-risk NGRC technology paths (e.g., compound/hybrid rotorcraft) and to distribute development cost and sovereign IP rights across partners.
Operational risk radar — what to monitor through 2026
- Raw-material indices (titanium and carbon-fiber feed): input cost pressure and lead-time shifts.
- Composite manufacturing capacity and skilled labor availability: lead-time and quality variance.
- Defense budget signals and program re-baselines among large buyers.
- NATO NGRC milestones and award cadence for concept-to-demonstrator transitions.
- Export controls and geopolitical flashpoints that alter exportability and long-term sustainment.
- OEM order books and announced option exercises — near-term production ramp indicators.
How to use this report in 2026
PW Consulting’s report is designed as a decision-support instrument. Practical use cases include:
- Structuring multi-year acquisition and sustainment contracts with indexed cost and performance gates.
- Defining industrial participation and technology-transfer clauses aligned with sovereign capability objectives.
- Prioritizing capex for composite-processing and titanium sourcing to secure factory throughput for planned production ramps.
- Building M&A screening criteria around aftermarket revenue defensibility and systems-integration roadmaps.
Conclusion and next steps
2026 represents a pivotal year for two-person military rotorcraft strategy: immediate procurement decisions will lock in fleet shapes for a decade, while NGRC-era requirements are already redirecting R&D investments. PW Consulting’s market model—grounded in historicals through 2025 and forward-looking to 2032—provides the quantitative backbone and the operational playbooks that senior leaders need to convert strategic intent into executable programs.
For readers requiring the granular datasets (regional and role-specific splits, segment-level forecasts, supplier matrices, and full scenario outputs), the full report contains the detailed tables and model access necessary for transaction-level planning and contract negotiation. Visit PW Consulting’s report page to download the executive package and to request a bespoke briefing that maps our findings directly onto your program timelines and risk tolerances.
For detailed analysis of this topic, please visit the official page: Worldwide Military Two-person Rotorcraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com