

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Natural Gelling Agent Market to Grow at a 6.42% CAGR Through 2032

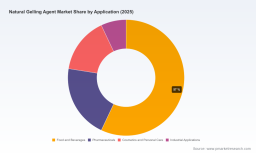
Worldwide Natural Gelling Agent Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market intelligence on the Worldwide Natural Gelling Agent market synthesizes five years of observed momentum (2020–2025) with a rigorous forecast through 2032. Built for commercial executives, innovation leaders, and M&A teams, this executive preview explains why the natural gelling agent landscape will be a strategic battleground in 2026 and how leading companies can convert macro growth and structural risks into durable advantage.
Worldwide Natural Gelling Agent Market
Why this market matters in 2026
The market has demonstrated steady expansion from an estimated USD 6,712.45 million in 2020 to USD 9,132.40 million in the base year (2025). Our modelling points to continued, predictable growth — a compound annual growth rate (CAGR) of 6.42% — that drives the global market toward approximately USD 14,117.17 million by 2032. For commercial teams planning 18–36 month investment cycles, those numbers translate into both incremental revenue pools and capacity-planning imperatives: predictable scale, yet with enough tail-risk from raw material and regional supply concentration to require proactive strategy.
Worldwide Natural Gelling Agent Market
Key forces shaping the market in 2026
- Sustained end-market demand with product premiumization. Food & beverage formulation trends (clean-label, plant-based, reduced sugar/fat) continue to lift demand for naturally derived hydrocolloids and gelling agents. Premiumization in pharmaceuticals and personal care also creates higher-margin opportunities for purified and specialty grades.
- Supply-side concentration and raw-material volatility. Seaweed-derived inputs that underpin carrageenan and alginate remain geographically concentrated in Asia–Pacific, exposing supply to weather, harvest cycles, and geopolitics. We are already observing price pressure on carrageenan in early 2026 and historic episodes of alginate price spikes tied to brown-seaweed availability.
- Consolidation and capability stacking. The sector shows a move from pure-ingredient suppliers to integrated ingredient platforms that combine sourcing, formulation services, and regulatory expertise. This consolidation affects price dynamics, innovation velocity, and customer switching costs.
- Regulatory and trade tailwinds/uncertainties. Recent policy changes (for example, exemptions on select chemical tariffs in the US in 2025) temporarily ease cost pressure for imported inputs, but companies must track evolving trade measures and local regulatory approvals for food and pharma ingredients.
- Sustainability and traceability as commercial differentiators. Buyers increasingly pay premiums for verified sustainable sourcing (e.g., responsible seaweed harvesting, circular sourcing of citrus peel for pectin). Firms that can demonstrate traceable, low-carbon supply chains will gain shelf-space and contract advantages.
What PW Consulting’s report delivers — practical, decision-ready content
Our full market study is designed as an operational toolkit, not just a desk-reference. Key deliverables include:
Worldwide Natural Gelling Agent Market
- Top-down market sizing and reconciled historical series (2020–2025) with transparent methodology and sensitivity checks against price and volume scenarios.
- Forward-looking forecast (2026–2032) using scenario modelling that isolates demand drivers (e.g., food reformulation trends), supply-side constraints (raw-material cycles), and macroeconomic sensitivity.
- Supply-chain risk maps and a raw-material price tracker that flags structural vulnerabilities (seaweed concentration, seasonal harvest risks, and substitution dynamics) and recommends hedging and sourcing tactics.
- Competitive benchmarking and capability matrices for leading suppliers covering plant footprints, technology capabilities, specialty grades, and go-to-market positioning.
- Commercial playbooks with 12- to 36-month actions: route-to-market options, co-development models with food manufacturers, vertical integration scenarios, and price-capture strategies during tightening cycles.
- M&A and partnership heatmaps including likely targets for bolt-on acquisitions, strategic JV structures, and integration risk templates to preserve value post-deal.
- Regulatory and sustainability trackers focused on food, pharma, and cosmetics approvals; certification pathways for sustainable sourcing; and packaging/labeling implications for clean-label claims.
Competitive landscape — who matters and why
The sector is moderately concentrated: the top three players control a meaningful share of the market, and the top five widen that share materially. This level of concentration creates both barriers and opportunities — barriers through scale and customer relationships, opportunities through divestment and partnership plays as larger firms optimize portfolios.
Prominent industry participants profiled in the report include global ingredient leaders and specialized hydrocolloid manufacturers. Our strategic assessment of these players highlights where value is being created and where gaps remain:
- Cargill, Incorporated — Strength: diversified hydrocolloid portfolio and investments in pectin capacity to serve food customers. Strategic implication: best positioned to support large-scale CPG reformulation programs; smaller rivals should look for niche specialty grades or service differentiation.
- CP Kelco (now part of Tate & Lyle) — Strength: specialty hydrocolloids and technical application support. Strategic implication: the CP Kelco acquisition amplifies Tate & Lyle’s capability to supply pectin and specialty gums — expect intensified competition in premium food applications and targeted pricing pressure in commodity grades.
- Tate & Lyle plc — Strength: ingredient platform scale and distribution reach. Strategic implication: platform consolidation will push peers to secure proprietary formulations or service-led differentiation.
- Kerry Group plc — Strength: application development and clean-label solutions for food & beverage customers. Strategic implication: Kerry will continue to be a preferred partner for CPGs prioritizing speed-to-market for reformulated SKUs.
- Ingredion, ADM, Ashland, DuPont/IFF — Strengths: broad ingredient portfolios and global customer relationships. Strategic implication: these players compete on integrated solutions (starches + gums) and offer scale advantages in supply continuity.
- Specialists such as GELITA, Rousselot, Jungbunzlauer, Herbstreith & Fox, FMC, Gino Gums & Stabilizers, AEP Colloids — Strengths: product specialization (gelatin, xanthan, pectin, carrageenan) and technical purity. Strategic implication: specialists remain attractive partners for premium, regulated applications (pharma, nutraceuticals) and as M&A targets for scale players.
Recent industry moves to monitor in 2026
- Tate & Lyle’s acquisition of CP Kelco (completed mid‑2024) materially changes the competitive map for specialty gums and pectin — expect integration-related synergies, portfolio rationalization, and targeted capacity realignment.
- Capacity investments continue: Jungbunzlauer’s announced build‑out of a North American xanthan facility signals new regional supply options and local sourcing advantages for North American formulators.
- Major producers have also increased production footprint in key origin regions (for example, pectin capacity expansions in South America) to diversify sourcing and reduce lead times for global customers.
- Raw-material signals: carrageenan saw upward price pressure in early 2026 due to tightening red seaweed supply, while sodium alginate experienced earlier price spikes tied to brown seaweed availability — these dynamics have direct implications on formulation economics and contract negotiations.
Actionable strategic guidance for 2026
For companies making resource allocation decisions in 2026, the choices fall into three clear, mutually reinforcing pillars:
- De-risk supply and secure margin. Negotiate multi‑year supply agreements with staggered volumes, invest in alternative sourcing (geographic and species diversification), and evaluate small-scale in-region processing to reduce freight and tariff exposure.
- Differentiate through formulation and services. Move up the value chain with co-developed, application-specific systems (reformulation toolkits, clean‑label blends, shelf-life extension systems) that command premium pricing and increase switching costs for customers.
- Use M&A and partnerships selectively. Pursue bolt-on acquisitions to close capability gaps (specialty grades, purification technology, regional production) and form JVs with raw-material suppliers to secure feedstock access under preferred commercial terms.
What we recommend you read in the full report
The full PW Consulting study contains the detailed segment breakouts, regional maps, company scorecards, and actionable playbooks that will support rapid, evidence-based decisions in 2026. To preserve strategic opportunity and encourage evidence-led engagement with our clients, this public preview omits granular regional, type and application split tables; those precise segment level breakdowns are available in the full report download and by request to our advisory team.
Concluding perspective
The natural gelling agent market is large, growing, and increasingly strategic to food, pharma and personal‑care supply chains. With an expected CAGR of 6.42% over the forecast window and an expanding revenue base that approaches the low‑ten‑billions (USD millions) by the end of the decade, 2026 is a pivotal year to align procurement, innovation and corporate development plans. The right combination of supply de‑risking, product differentiation, and targeted M&A will determine which companies capture the highest-margin segments and which will be forced into transactional competition.
For companies preparing budgets, capital plans, and customer‑facing innovation roadmaps in 2026, the evidence is clear: act now to secure feedstock resilience and accelerate service-oriented differentiation. PW Consulting’s full report equips leaders with the data, scenario models, and playbooks needed to translate these strategic imperatives into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Gelling Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com