

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 1‑Decanol Market to Expand at 6.5% CAGR, Hitting USD 436.36 Million by 2032 as Asia‑Pacific Leads with USD 120.69 Million

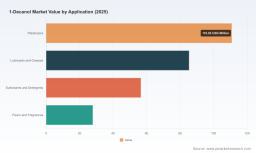
Worldwide 1‑Decanol Market — Strategic Outlook for 2026: Navigating Growth, Supply Complexity, and Regulatory Reset
PW Consulting’s latest Worldwide 1‑Decanol Market report (base year 2025, forecast 2026–2032) distills the commercial imperatives chemical, personal‑care, and specialty‑polymer executives must act on in 2026. The mid‑chain fatty alcohol sector achieved material growth through 2020–2025 and the 1‑Decanol market reached approximately USD 280.8 million in 2025. Our baseline forecast projects a steady compound annual growth rate (CAGR) of 6.5% into the 2026–2032 window, with the market trajectory reflecting both structural demand for performance additives and episodic supply‑side shocks. This release is a strategic primer — it reveals the levers that matter, the blind spots to avoid, and the decision frameworks we recommend for the coming planning cycle, while preserving the granular segment and regional datapoints that subscribing clients can access on the report landing page.
Worldwide 1-Decanol Market
Why 2026 Is a Pivotal Year
-
Commercial inflection: After a period of steady expansion, 2026 will be a year when procurement and product teams must choose between defensive cost management and offensive share capture. Our scenario work shows that companies that align feedstock strategy with product differentiation will materially outperform peers.
Worldwide 1-Decanol Market -
Regulatory tightening: New regulatory milestones in Europe and state‑level actions in the U.S. are reshaping product compliance obligations. These changes will have immediate implications for formulations, labeling, and upstream supplier qualification.
Worldwide 1-Decanol Market -
Supply chain recalibration: Raw material volatility and trade policy shifts are prompting re‑routing of sourcing flows and accelerating near‑sourcing projects, particularly for producers reliant on oleochemical feedstocks.
High‑Level Market Dynamics — Drivers and Risks
-
Demand composition. End‑use pull remains broad — from plasticizers and lubricants to surfactants and flavors/fragrances. Growth is underpinned by durable industrial applications and selective premiumization in personal care and pharmaceutical excipients. That said, growth is heterogenous: the fastest upside is tied to high‑purity specialty grades and formulations that capture sustainability value.
-
Feedstock pressure. Natural‑feedstock suppliers have faced a tightening cost envelope following supply constraints in key producing geographies. Commodity swings have increased feedstock cost pass‑through risk for natural 1‑Decanol producers and are sharpening the cost‑competitiveness gap with synthetic routes.
-
Trade and tariff landscape. U.S. trade measures enacted in early 2026 have altered competitiveness for several import flows, forcing buyers and sellers to reprice or reroute. For export‑dependent producers, these tariffs materially affect destination strategies.
-
Regulatory overlay. EU chemical regulation updates require refreshed exposure dossiers for surfactant uses by mid‑2026; California’s recent listing activity has elevated disclosure and labeling risk for finished consumer products. These two vectors will increase compliance costs and slow product introductions for companies that lack regulatory bandwidth.
-
Consolidation and capacity signals. Market concentration at the producer level provides both stability and a capacity‑management lever for incumbents. Recent capacity investments and premium grade launches indicate incumbents are pursuing differentiated pathways rather than pure volume competition.
Segmentation & Strategic Positioning (Top‑Level)
PW Consulting’s segmentation framework evaluates 1‑Decanol across source routes (natural oleochemical vs synthetic petrochemical), application classes (industrial intermediates, personal care, specialty solvents, and others), and regional flows. In practice, strategic choices hinge less on nominal segment shares than on margin profile, supply risk, and regulatory exposure. Key takeaways for 2026 planning:
-
Source diversification is a hedge. Companies that maintain optionality across natural and synthetic routes can manage margin volatility and regulatory exposure more effectively.
-
Higher purity and specialty grades command optionality. Investment in fractional separation, hydrogenation control, or tailored purification is an accelerator to enter pharmaceutical and high‑end personal care spaces.
-
Formulation‑led differentiation beats volume play in constrained markets. Where feedstock costs are elevated, value capture comes from formulations that reduce active load or enable premium pricing through performance or sustainability claims.
Competitive Landscape — What Leading Producers Are Doing
The competitive map is anchored by global chemical majors and regional oleochemical champions. Each competitor pursues a distinct combination of feedstock integration, geographic reach, and product strategy. Our analysis of public moves and proprietary intelligence identifies three prevailing strategic archetypes:
-
Integrated majors focusing on portfolio breadth and technical service (example archetype: producers with diversified fatty alcohol lines and global application support). These firms are playing to strengths in scale, regulatory compliance, and multi‑application customer relationships.
-
Oleochemical specialists emphasizing feedstock integration and sustainability credentials (example archetype: regional players leveraging palm/kernal or coconut oil chains). These companies are racing to lock in raw material supply and to certify sustainable mass‑balance grades for sensitive customers.
-
Synthetic route specialists delivering high‑purity intermediates (example archetype: firms using petrochemical Ziegler or related routes). These players are targeting high‑value industrial and pharmaceutical niches where consistency and purity trump feedstock sustainability narratives.
Recent corporate developments validate this segmentation: capacity expansions in Asia signal continued investment in oleochemical supply; sustainability certification wins in Europe point to customer demand for traceable mass‑balance grades; and new high‑purity product launches are aimed squarely at pharmaceutical and other regulated end markets. For commercial leaders, mapping competitor moves against customer sustainability and purity requirements is now table stakes.
Actionable Recommendations for 2026 Decision Makers
-
Procurement and Sourcing: Move from spot‑price exposure to a portfolio approach. Negotiate hybrid contracts that combine fixed volumes for security with indexed volumes for flexibility. Prioritize supplier audits and dual‑source plans in regions exposed to tariff shifts.
-
Product Strategy: Segment SKUs into commodity, premium, and regulated clusters. Accelerate development of high‑purity grades and certified sustainable variants for customers willing to pay a premium. Where regulatory labeling risk is high, offer reformulation support to customers.
-
Regulatory & Compliance: Invest in a regulatory dashboard and designate a cross‑functional owner to track REACH updates, U.S. state listings, and certification trajectories. Preemptive dossier updates and early supplier qualification will cut time‑to‑market and reduce downstream liabilities.
-
Manufacturing & CAPEX: Reassess brownfield upgrades that improve yield or purity rather than greenfield volume. For exporters, evaluate asset optimization to serve tariff‑favored destinations and reduce logistics friction.
-
M&A & Partnerships: Target bolt‑on acquisitions that add specialty grades, regional sourcing control, or customer application expertise. Consider tolling or JV structures to manage feedstock tightness without overcommitting capital.
What the PW Consulting Report Delivers (Practical Contents)
Our full report is structured to be execution‑ready for 2026 planning cycles. Key operational deliverables include:
-
Forward‑looking demand models by application and by region with scenario stress‑testing under alternative regulatory and commodity assumptions.
-
Supply‑side mapping that traces feedstock origins, conversion technologies, and logistics choke points — including supplier profiles and capacity change trackers.
-
Price and margin sensitivity tools that let commercial and finance teams model pass‑through, margin compression, and hedging effectiveness.
-
Regulatory and certification playbook covering EU chemical obligations, U.S. labeling exposures, and voluntary sustainability schemes — with recommended compliance timelines and resource estimates.
-
Competitive benchmarking and capability heatmaps to prioritize investment, M&A targets, and partnership candidates.
-
Go‑to‑market templates for sales teams — segment prioritization, value messages for sustainability and purity, and negotiation levers for different buyer profiles.
To preserve the strategic value of the report as a decision tool, the public summary intentionally omits the full set of segmented regional and application level datapoints. Subscribers receive these core breakdowns, along with interactive dashboards and downloadable models that allow immediate scenario testing and board‑ready slide creation.
Final Considerations — Timing and Next Steps
For executives preparing 2026 budgets and strategic plans, two short time windows matter: immediate supplier and compliance actions that must be taken in Q1–Q2 to avoid downstream disruption, and mid‑year product and investment reviews to capture opportunities arising from premium grade demand. PW Consulting recommends convening a cross‑functional steering group to run three rapid workstreams in parallel: (1) supply‑risk mitigation, (2) product & regulatory readiness, and (3) commercial value capture. These workstreams should be chartered with clear KPIs tied to margin protection and selective growth targets.
PW Consulting’s Worldwide 1‑Decanol Market report provides the empirical backbone and pragmatic templates to execute these steps. For teams that need to translate market dynamics into a 90‑day action plan or an investor‑grade strategic memo, our subscribers’ deliverables include bespoke workshops and model walkthroughs.
Discover the detailed segment tables, regional flows, and downloadable scenario models on the report landing page — they are the pieces that convert market intelligence into executable strategy for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com