

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Functional Magnetic Resonance Imaging Market to Reach USD 4,117.9 Million in 2025, Poised for 6.42% CAGR to USD 6,365.6 Million by 2032

Worldwide Functional Magnetic Resonance Imaging Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market briefing on the Worldwide Functional Magnetic Resonance Imaging (fMRI) Market distills seven years of historical trends and a seven-year forecast into a concise, decision-grade playbook for executives, clinical leaders, and investors planning for 2026. Anchored on a base year of 2025 and a forecast window through 2032, the report quantifies a market poised to expand at a compound annual growth rate (CAGR) of 6.42%. The global fMRI ecosystem—already a multibillion-dollar clinical and research platform—continues to demonstrate resilience as hardware innovation, AI-enabled software, and regulatory shifts reshape procurement, service models, and clinical adoption.
Worldwide Functional Magnetic Resonance Imaging Market
Why this briefing matters for 2026
-
Timing-sensitive capital allocation: procurement cycles for MRI systems have long lead times. Our analysis aligns procurement windows with regulatory and supply-chain inflection points now visible on the horizon.
Worldwide Functional Magnetic Resonance Imaging Market -
OPEX vs CAPEX trade-offs: volatile supply markets and the emergence of low-cryogen platforms force a re-evaluation of total cost of ownership (TCO). The briefing provides frameworks for quantifying operating-risk premiums that should be embedded into 2026 capital budgets.
Worldwide Functional Magnetic Resonance Imaging Market -
Strategic positioning for competitive advantage: vendors and health systems that pair hardware with optimized fMRI workflows, turnkey stimulation hardware, and AI-accelerated analytics will secure differentiated revenue and utilization trajectories.
Snapshot: Market trajectory and concentration
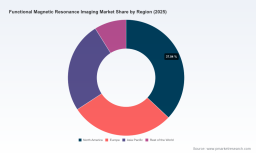
The fMRI market is entering 2026 from a position of sustained growth: our model shows clear expansion from the mid‑2020s into the early 2030s, with the market size increasing materially in the last five years and continuing to expand under a 6.42% CAGR through 2032. Importantly, market share is concentrated—our concentration metrics show that the top three vendors account for roughly 62% of market value while the top five approach nearly 78%. This concentration underscores both the scale advantages enjoyed by leading OEMs and the strategic opportunities available to niche innovators and service specialists.
Core dynamics shaping 2026 decisions
-
Supply-chain and raw-material pressure: MRI magnet technologies historically rely on cryogens and helium logistics. Recent supply disruptions have led to spot price spikes that materially affect service economics. Procurement teams must now model helium risk as a first-order variable in vendor selection and contract negotiation.
-
Regulatory momentum toward low‑cryogen platforms: FDA clearances in 2025–2026 for lower‑helium or virtually helium‑free platforms represent a structural shift. Early adopters of these platforms stand to shrink long-term service risk and stabilize OPEX, while laggards face higher volatility exposure.
-
Software and workflow monetization: AI-based reconstruction and workflow platforms are migrating from point improvements to system-level differentiators. Vendors combining advanced reconstruction, standardized stimulation hardware, and validated analytics pipelines will capture higher-margin service and software revenue.
-
Clinical-commercial convergence: an expanding base of clinically validated fMRI applications—pre-surgical mapping, connectivity-informed diagnostics, and neurosurgical planning—creates new reimbursement and referral dynamics that organizations must map into service line strategies.
What the PW Consulting report contains (practical, operational, and investment-ready)
-
Market sizing and forecast model: a transparent, auditable financial model spanning 2020–2032 with scenario toggles for helium pricing, regulatory adoption rate, and AI workflow penetration. The model is designed for CFOs and strategy leads to run sensitivity analyses relevant to 2026 capital plans.
-
Procurement playbooks: vendor selection checklists, negotiation levers (warranty structure, helium‑risk sharing, service SLAs), and channel strategies for deploying modular fMRI solutions in mixed clinical/research environments.
-
Clinical adoption frameworks: validated use cases, implementation roadmaps for integrating fMRI into neurosurgical and neuro-oncology pathways, and metrics to track time-to-value post-installation.
-
Competitive intelligence dossier: granular company profiles, product roadmaps, patent activity snapshots, and go‑to‑market alignment analyses to support M&A diligence or partnership scouting.
-
Regulatory and reimbursement map: timelines for device clearances, policy levers to watch in major markets, and a pragmatic guide to positioning fMRI services for reimbursement and grant‑supported research.
-
Service and aftermarket optimization: templates for hybrid service models (in‑house + OEM), lifecycle management, and opportunities to convert installed bases through software monetization.
Competitive landscape: who to watch and why
The competitive topology is dominated by global OEMs with diversified MRI platforms and growing software stacks, alongside specialist providers that offer turnkey fMRI stimulation and workflow solutions. PW Consulting highlights several players whose strategic moves will be material to 2026 dynamics:
-
Siemens Healthineers (Erlangen, Germany): A broad MAGNETOM portfolio coupled with ongoing advances in bore design and helium‑management technologies has positioned the company to capitalize on clinical fMRI expansion and low‑cryogen transitions. Recent FDA clearance of a 1.5T platform featuring virtually helium‑free technology is a key differentiator for buyers prioritizing operational stability.
-
GE HealthCare (Chicago, USA): The SIGNA family and recent clearances for next‑generation platforms and AI workflow tools reflect an aggressive push to embed fMRI capabilities within end‑to‑end imaging platforms. GE’s regulatory wins in early 2026 validate a strategy that pairs hardware refreshes with software ecosystems.
-
Philips Healthcare (Amsterdam, Netherlands): Philips is advancing AI-powered reconstruction and workflow acceleration with approvals for dual-AI software that materially shortens scan times and improves neuro image fidelity—advantages that translate directly into throughput and patient pathway optimization.
-
Canon Medical Systems (Otawara, Japan): Canon’s emphasis on integrated visualization and dedicated fMRI applications aims to simplify clinical workflows, especially for centers moving from research use to routine clinical mapping.
-
United Imaging Healthcare (Shanghai, China): Rapid product introductions and high-performance gradient platforms are enabling competitive entries in advanced fMRI and ultra‑high field segments, especially in markets prioritizing capital efficiency and feature parity.
-
NordicNeuroLab (Bergen, Norway): As a specialist in fMRI stimulation and turnkey workflow tools, NordicNeuroLab remains a crucial partner for centers seeking standardized, cross-vendor fMRI acquisition and stimulus presentation capabilities.
Recent developments with strategic implications (2025–early 2026)
-
FDA clearances for low-cryogen and AI-enabled platforms—granted to multiple vendors in late 2025 and early 2026—reduce the technical barrier to replacing legacy fleets and materially change the calculus for long-term service contracts.
-
Product launches showcasing remote imaging platforms and dynamic videography capabilities signal a market move toward distributed, multi-site research networks and centralized analytics hubs.
-
Helium market volatility in early 2026 has introduced an immediate cost pressure that will compress margins for older fleets and create a multi-year demand wave for low‑helium technologies.
Strategic recommendations for 2026
-
For hospital systems and imaging networks: prioritize prospective procurement on platforms validated for low‑cryogen operation and AI workflow integration. Negotiate helium-risk sharing mechanisms and demand transparency on software roadmaps and upgrade paths.
-
For vendors and OEMs: accelerate commercialization of helium‑resilient magnet designs and monetize software with clear clinical value propositions (reduced scan time, improved diagnostic yield). Explore bundled service models that shift buyers away from purely transactional CapEx decisions.
-
For investors and M&A advisors: use the concentration metrics as a guide—scale matters—but also look for high-margin niche playbooks (turnkey fMRI workflows, validated analytics, multi-vendor stimulation hardware) that could be consolidated to capture aftermarket and software revenue streams.
-
For research institutions: leverage the growing availability of cloud-enabled analytics and vendor-neutral stimulation solutions to drive multi-center studies while reducing per-site infrastructural burdens.
Scenario planning: risk vectors and upside catalysts
-
Downside risk: prolonged helium supply disruption and slow regulatory adoption could depress utilization and delay fleet modernizations—sensitive to short-term cash constraints in public health systems.
-
Base case: steady recovery in equipment renewals, migration toward low‑cryogen platforms, and gradual software monetization consistent with a mid‑single-digit CAGR across the forecast window.
-
Upside catalysts: accelerated reimbursement for fMRI-derived diagnostics, broad adoption of AI-accelerated protocols that double throughput, or rapid consolidation in the aftermarket service market could materially outperform base projections.
How to use the full PW Consulting report in 2026 planning
-
Run the model: our interactive financial model lets procurement teams stress test vendor offers against helium-price scenarios, upgrade timelines, and utilization assumptions.
-
Validate clinical ROI: use our adoption playbooks and workflow benchmarks to quantify the marginal benefit of fMRI-enabled pathways versus standard imaging in neurosurgical and neuro-oncology services.
-
Inform negotiations: our vendor playbooks provide clause language for risk-sharing on raw materials, upgrade credits, and software‑as‑a‑service commitments—tools that materially reduce downside risk in long-term contracts.
PW Consulting’s Worldwide fMRI Market report is deliberately structured to guide 2026 strategic decisions without compromising your need for verified, proprietary detail. We present the analytic scaffolding and action steps here; the full report contains the underlying segment models, company-by-company financials, and the downloadable scenario model you can apply directly to your procurement and investment cases.
To access the complete dataset, proprietary segment breakdowns, and the interactive forecast tool, visit the official report page or contact the PW Consulting client desk. Our team is available for workshops to translate these insights into a tailored 2026 strategic plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Functional Magnetic Resonance Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com