

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Antibody Fragments Market Set to Reach USD 22,797.7 Million by 2032, Backed by a 9.6% CAGR

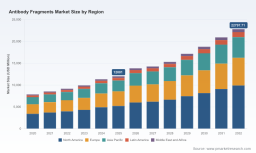
Worldwide Antibody Fragments Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive summary
Antibody fragments — including Fab, scFv and single-domain formats — are migrating from niche tools into mainstream therapeutic, diagnostic and R&D pipelines. Our new Worldwide Antibody Fragments Market report (base year 2025; historical window 2020–2025; forecast 2026–2032; revenues expressed in USD Million) shows a robust multi-year expansion at a compound annual growth rate (CAGR) of 9.6% across the forecast horizon. Total market value grows substantially from the 2025 baseline into the early 2030s, reflecting accelerating demand for smaller, modular biologics that offer tissue penetration, manufacturability advantages and differentiation in crowded biologics portfolios.
Worldwide Antibody Fragments Market
Why this preview matters for 2026 decision cycles
-
Timing: 2026 will be a pivot year for resource allocation. Biotech and pharma companies that set platform bets, manufacturing footprints and partnership strategies early in 2026 will capture outsized share of the next growth phase.
Worldwide Antibody Fragments Market -
Capital discipline: With elevated R&D and CMC costs specific to fragment formats, executives need a short list of de-risking levers — from targeted external collaborations to focused in-house process development — to preserve margins while scaling.
Worldwide Antibody Fragments Market -
Regulatory readiness: Fragment therapeutics are treated as biologics by regulators; preclinical and clinical development paths are rigorous. Proactive regulatory planning reduces time-to-market and competitive uncertainty.
Market trajectory — the big-picture numbers
Our modelling — based on historical performance (2020–2025) and forward-looking adoption curves — projects substantial expansion through 2032. The market baseline in 2025 anchors investment decisions for 2026 and beyond; the forecast period (2026–2032) reflects steady double-digit opportunity across therapeutic, diagnostic and discovery segments. Market concentration is moderate: the top three players account for a meaningful portion of revenue (CR3 ≈ 42.5%), and the top five approach majority share (CR5 ≈ 58.8%), underscoring both incumbent strength and room for specialist entrants.
Segment dynamics — what matters and what we hide (intentional)
Fragment formats are heterogeneous: each offers trade-offs across potency, half-life, manufacturability and IP. Our full report provides granular splits and subsegment revenue trajectories; here we surface the critical commercial drivers that will shape capitalization plans in 2026 without disclosing proprietary subsegment numbers.
-
Therapeutic momentum: Clinical pipelines and recent approvals validate fragment modalities' value proposition in indications requiring deep tissue penetration or rapid tissue clearance. However, clinical success alone does not guarantee commercial viability — COGS and pricing dynamics will decide margin sustainability.
-
Diagnostics and research uptake: Fragments' smaller size and modularity make them attractive in diagnostic reagents and research reagents markets, with commercial models that differ materially from therapeutics (shorter development cycles, volume-based economics).
-
Manufacturing and cost profile: The absence of an Fc domain eliminates Protein A affinity capture, often necessitating multi-step purification (ion exchange, hydrophobic interaction chromatography and other polishing steps). That operational reality can raise manufacturing costs substantially versus full-length monoclonal antibodies and must be factored into go/no-go investment decisions.
Competitive landscape — incumbents, challengers and service partners
The competitive map combines large integrated pharmas with specialist service providers and platform companies. Incumbents leverage scale, global regulatory teams and established commercial channels; nimble players focus on platform differentiation (e.g., nanobody technology, bespoke expression systems) and CMC innovations.
-
Large pharmas (examples included in our analysis): Established firms are integrating fragment formats into broader biologics portfolios, using their clinical and commercialization muscle to bring fragment-based drugs through late-stage trials and to market. Their strategic moves include platform investments and targeted acquisitions.
-
Platform leaders: Companies with proprietary single-domain antibody platforms are emphasizing tissue penetration and manufacturability in their value propositions. Ongoing platform advancements — including those publicly announced in 2025 — indicate continued prioritization of next-generation fragment therapeutics.
-
CMO / CDMO and service specialists: Firms offering optimized expression systems (mammalian and microbial), stabilization technologies and custom production services are critical enablers. Investment in modular production capacity and fragment-specific purification know-how is an attractive partner strategy for sponsors aiming to shorten technical timelines.
Recent developments to watch
-
Platform acceleration: Major platform announcements in 2025 show sustained promotional activity by platform owners positioning single-domain technologies as next-gen therapeutics with manufacturing and clinical benefits.
-
Partnership proliferation: Early-2025 partnership expansions and milestone-driven collaborations underscore a trend toward distributed R&D models — sponsors outsource early discovery and some lead optimization to specialists to reduce fixed cost exposure.
-
Academic and industry synthesis: Reviews published in 2025 synthesize industrialization progress for nanobodies and related formats, highlighting evolving IP landscapes and clinical pipelines that will influence licensing and M&A activity.
Manufacturing, CMC and supply chain considerations
Manufacturing choices are among the highest-impact decisions for 2026. Key considerations we model and recommend:
-
Expression platform selection: Microbial systems (e.g., E. coli, Pichia pastoris) can deliver cost and yield advantages for certain fragments and have demonstrated optimized fed-batch yields in industry reports. Mammalian (CHO) systems remain necessary for complex constructs or when post-translational modifications drive function.
-
Purification strategy: The lack of Fc-driven Protein A capture commonly forces multi-step purification schemas. Our scenario analyses show this can increase manufacturing cost by up to ~60% compared with full monoclonal antibodies unless offset by platform-specific innovations.
-
Half-life engineering trade-offs: PEGylation, albumin-binding tags or Fc fusions extend in vivo persistence but materially increase COGS. Our modelling quantifies margin erosion scenarios for high-volume, price-sensitive indications — a critical consideration for 2026 portfolio prioritization.
Regulatory, reimbursement and commercial pathways
Antibody fragments are regulated as biologics and require comparable preclinical, clinical and post-market evidence. From a commercial standpoint, pricing strategies must account for higher COGS in many configurations, and payer acceptance will hinge on clear value demonstrations (efficacy, safety, dosing convenience). For 2026 planning, sponsors should:
-
Integrate health economics early into clinical design to support reimbursement dossiers.
-
Engage regulatory authorities proactively to align nonclinical and CMC expectations for fragment formats.
-
Model pricing scenarios that reflect both premium indications and volume-sensitive diagnostic/research markets.
What the PW Consulting report delivers (practical contents)
Our full report is built as an operational playbook for 2026. Key deliverables include:
-
Top-line market forecasts (2026–2032) with sensitivity cases and scenario stress tests.
-
Competitive profiles and capability matrices for incumbents, platform owners and CDMOs — highlighting R&D pipelines, manufacturing footprints and strategic intent.
-
Actionable CMC roadmaps and cost modelling templates to quantify trade-offs between expression systems, purification strategies and half-life extension techniques.
-
Regulatory pathway decision trees and reimbursement modelling frameworks calibrated to fragment-specific risks and evidence requirements.
-
M&A, licensing and partnership playbooks with prioritized targets and value-capture scenarios tuned for 2026 execution windows.
How to use this intelligence in 2026 — recommended moves
-
Prioritize platform bets by aligning scientific advantage with commercial pathway: commit to formats where clinical differentiation aligns with sustainable manufacturing economics.
-
Pursue staged externalization: mitigate upfront capital by partnering with service providers for early-phase production while retaining strategic control of late-stage manufacturing decisions.
-
Invest in CMC innovation: targeted investment in purification, stabilization and half-life engineering can unlock margin expansion and competitive advantage.
-
Align payer strategy with development: integrate health economics and real-world evidence generation plans into phase II/III designs to accelerate reimbursement acceptance.
-
Monitor IP and platform developments closely: platform advances and partnership flows announced in 2024–2025 indicate where licensing competition will be fiercest in 2026.
Conclusion — the strategic inflection is now
The antibody fragments market is at an inflection point. Our forecasts show a materially larger market beyond 2026, but the winners will be those who translate technical advantages into manufacturable, reimbursable products within disciplined cost frameworks. PW Consulting’s report equips leadership teams with the forecast granularity, competitive mapping and implementation tools required to make high-confidence, time-sensitive decisions in 2026.
Next steps
For executives preparing 2026 budgets and strategic plans: request the full Worldwide Antibody Fragments Market report for complete subsegment data, regional breakdowns and the proprietary models that underpin our forecasts. The full intelligence pack includes downloadable modelling workbooks and an executive briefing option to translate findings into a 90-day action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com