

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Global Medical Microscopic Hemostatic Clip Market Poised for 7.2% CAGR in 2026–2032

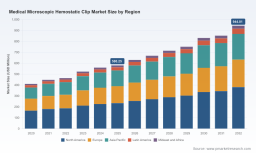
Worldwide Medical Microscopic Hemostatic Clip Market — Strategic Outlook for 2026 Decision-Makers
As healthcare providers accelerate minimally invasive and microsurgical procedures, the market for microscopic hemostatic clips is entering a phase of sustained, measurable expansion. PW Consulting’s latest research — based on a 2025 base year and a detailed historical review from 2020–2025 — projects continued growth through a seven-year forecast window (2026–2032). Our model indicates a compound annual growth rate (CAGR) of 7.2% in the forecast period, with the global market expanding materially from the 2025 baseline to a substantially larger market by 2032. For executives planning capital allocation, product development, distribution partnerships, or M&A activity in 2026, this study translates macro momentum into concrete, actionable guidance.
Worldwide Medical Microscopic Hemostatic Clip Market
Why this matters for 2026 planning
- Predictability: A mid-single-digit-plus CAGR provides a stable long-term growth envelope for investment prioritization across R&D, manufacturing scale-up, and commercial expansion.
- Timing: 2026 will be a pivotal year for companies that want to secure distribution channels and regulatory positioning before adoption curves steepen in key procedure areas.
- Value capture: As product innovation (e.g., rotation, one-step deployment, repositionability, and automated appliers) reshapes clinical workflows, first-mover advantages can translate into durable share gains in a moderately concentrated market.
Market trajectory — the headline figures
PW Consulting’s market architecture places 2025 as the analytical base year. From that baseline, our scenario analysis and deterministic forecast produce a clear growth pathway to 2032 underpinned by a 7.2% CAGR for the forecast period (2026–2032). The trajectory reflects a combination of rising procedural volumes in endoscopy and laparoscopy, device innovation that lowers procedural time and expands indications, and a regulatory/reimbursement environment that increasingly facilitates outpatient and ambulatory adoption.
Worldwide Medical Microscopic Hemostatic Clip Market
Key dynamics shaping demand
- Clinical workflow innovation: New clip designs and delivery systems that enable 360° rotation, one-step deployment, and repositionability are reducing procedure time and improving closure reliability in GI endoscopy and select microsurgical interventions.
- Device-format debate: The market is evolving along a disposables-versus-reusable axis. Single-use, preloaded appliers simplify logistics but increase unit cost; reusable appliers reduce per-procedure cost but demand sterilization and lifecycle management — commercial strategies must reconcile clinical preference with institutional procurement priorities.
- Regulatory clarity and reimbursements: Titanium hemostatic microclips fall under established regulatory frameworks (Class II implantable clips under 21 CFR 878.4300 in the U.S., product code FZP) and increasingly explicit reimbursement pathways in outpatient settings. These factors lower adoption friction for next-generation clips that meet GMP and labeling standards.
- Material and manufacturing constraints: Titanium Grade 1 is the material standard due to its biocompatibility, malleability, MRI compatibility, and radiolucency. This creates both a supply-chain dependency and a high bar for manufacturing quality control, favoring established suppliers with precision metalworking and sterilization capabilities.
Competitive landscape — tactical takeaways
The market exhibits meaningful concentration among a small group of specialized players and surgical-instrument incumbents. Our competitive assessment synthesizes product-level differentiation, regulatory position, route-to-market, and recent strategic moves:
Worldwide Medical Microscopic Hemostatic Clip Market
- Synovis Micro Companies Alliance (Baxter): Historically positioned in microsurgical vessel control with titanium microclips and precision appliers. The 2025 FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier (preloaded with multiple titanium microclips) signals a push into automated delivery systems that reduce manual dexterity requirements in the OR.
- Established European microsurgical instrument specialists (e.g., Peter Lazic GmbH and S&T Microsurgical Instruments): These firms emphasize premium instruments, surgical craft, and regulatory compliance (ISO 13485 / CE pathways). Their strength is deep clinical trust and bespoke product lines for neurosurgery and microsurgery.
- U.S. surgical instrument manufacturers (e.g., Scanlan, Kapp Surgical): These players leverage custom instrument manufacturing and broad distribution relationships in acute care settings, offering complementary clamp and small-vessel control products that integrate with clip strategies.
- Innovative device entrants (e.g., Amsel Medical): Product differentiation around mechanical occlusion technologies (e.g., iDOT) highlights non-metallic or hybrid approaches that can compete on unique clinical use-cases and regulatory positioning.
- Active smaller providers and distributors (MicroSurgical Technology and others): These companies extend selection, supply-chain flexibility, and niche clinical solutions.
Recent market activity underscores the competitive momentum: Olympus launched a single-use, 360°-rotatable hemostasis clip in 2025, while the 2026 agreement giving Micro-Tech Endoscopy global distribution rights to a repositionable clip line illustrates acquisitive distribution strategies. These moves emphasize two sustained themes—product innovation and distribution consolidation.
Concentration and competitive implications
Market concentration metrics demonstrate that the top tiers of the industry command a majority share. This oligopolistic footprint produces both risk and opportunity: high barriers to entry for full-scale manufacturing and regulatory compliance, yet attractive acquisition targets for companies seeking rapid access to product lines or geographic reach. For 2026, disciplined M&A or licensing to secure differentiated clip technologies or rapid distribution pathways is likely to deliver asymmetric returns relative to greenfield investment.
Regulatory, reimbursement, and standards landscape
- Regulatory: Titanium microclips are regulated within established Class II pathways in major markets; compliance with GMP, labeling, and performance claims is non-negotiable. CE marking and ISO 13485 certification remain essential for European market access.
- Reimbursement: The availability of outpatient coding for defect closure procedures enhances the commercial case for disposable and repositionable clip systems by improving revenue capture in ambulatory settings.
- Standards and materials: Titanium Grade 1 is the accepted material standard; procurement strategies must account for traceability, annealing processes, and vendor qualification to meet implantation and imaging-compatibility requirements.
Practical, decision-oriented deliverables in the PW Consulting report
We structured this study to be a direct input into 2026 strategic planning cycles. The deliverables emphasize actionability over academic breadth and include:
- Proprietary market-sizing and forecast model (2020–2032) with scenario toggles for pricing, procedure volumes, and reimbursement uptake.
- Regulatory and reimbursement playbook with jurisdictional checklists and timelines for 510(k)/CE submissions and outpatient coding strategies.
- Competitive benchmarking templates that map product features (rotation, deployability, repositionability, applier automation), regulatory clearances, and likely pricing tiers.
- Manufacturing and supply-chain risk assessment, including raw-material sourcing maps for titanium and capacity stress-tests under demand surge scenarios.
- Commercial go-to-market frameworks for direct sales, distributor partnerships, and hospital system procurement negotiations, with specific modules for ambulatory surgery centers and integrated health networks.
- M&A and partnership screening tool that identifies acquisition targets by strategic fit and valuation sensitivity under varying growth scenarios.
Strategic recommendations for 2026
- Prioritize modular product platforms: Invest in applier architectures that accept multiple clip sizes and enable features such as 360° rotation and repositionability—these features are becoming clinical table stakes.
- Lock distribution early: Seek exclusive or semi-exclusive distribution agreements in priority markets as a defensive play against rapid consolidators.
- De-risk manufacturing: Certify secondary suppliers for precision titanium components and plan sterilization capacity to avoid scale-up bottlenecks.
- Use regulatory timing as a moat: Pipeline clearance and CE timelines should be staged to create rolling product introductions rather than one-time launches, sustaining commercial conversation across buying cycles.
- Target outpatient adoption: Align product pricing and value messaging to ambulatory and endoscopic settings where procedure shift and reimbursement codes can accelerate uptake.
How to use this report in your 2026 planning
For executive teams, the report functions as both a diagnostic and prescriptive tool. Use the market model to stress-test capital allocation scenarios and the go-to-market playbooks to define pilot geographies for new clip launches. Development teams should integrate the competitive benchmarking into product roadmaps, while corporate development groups should use the M&A screening to prepare for opportunistic consolidation. Clinical affairs teams will find the regulatory and reimbursement matrices particularly valuable for sequencing trials, claims, and payer engagement.
Conclusion — a data-driven but deliberately selective view
PW Consulting’s analysis shows a market that is growing at an attractive, investable pace with defined winners and clear entry barriers. The report provides the analytical backbone to develop differentiated strategies for product innovation, scale economics, and channel expansion in 2026. In keeping with our “trailer” approach, this briefing surfaces the structural insights and the tactical levers that matter most while reserving the granular regional, application, and segmentation datasets for the full report — the precise, downloadable intelligence you will need to translate strategy into action.
To obtain the full dataset, detailed segmentation, and the interactive forecast model that support these conclusions, visit the PW Consulting report page or contact our client services team to request access to the Worldwide Medical Microscopic Hemostatic Clip Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Microscopic Hemostatic Clip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com