

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Choroideremia Treatment Market Set to Soar at a 32.65% CAGR

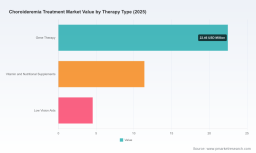
Worldwide Choroideremia Treatment Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive overview
The choroideremia treatment landscape is entering a decisive chapter. Our proprietary market model projects a rapid expansion from the mid‑2020s base into the early 2030s, driven by a concentrated pipeline of gene‑based and vision‑restorative candidates, emergent optogenetic and small‑molecule approaches, and an evolving regulatory and reimbursement environment. From an established 2025 baseline, PW Consulting forecasts the global market to expand at a compound annual growth rate (CAGR) of 32.65% through 2032, culminating in a multi‑hundred million USD opportunity by the end of the forecast horizon. Concurrently, market concentration is high — the top three and top five developers account for the large majority of commercial and near‑commercial value — creating both competitive pressure and strategic opportunities for alliances, asset trades, and acquisition plays.
Worldwide Choroideremia Treatment Market
Why this report matters for 2026 decision‑makers
- Tactical timing: 2026 is a watershed year for choroideremia programs as academic, non‑profit and industry actors reposition portfolios after mixed clinical readouts and multiple program handovers. Decisions made now about partnerships, manufacturing scale‑up, regulatory strategy, and payer engagement will materially affect market access and commercial capture through 2032.
- Regulatory inflection points: Regulatory authorities remain divided on meaningful visual function endpoints. FDA precedent emphasizing larger letter‑gain thresholds has heightened development risk for traditional BCVA endpoints, while certain regional regulators may accept smaller gains or alternative functional endpoints. These differences create parallel approval pathways and demand bespoke evidence plans by jurisdiction.
- Payer & HTA pressure: Ultra‑rare prevalence, high one‑time treatment costs, and complex durability questions mean payers will scrutinize value — demanding long‑term effect evidence, risk‑share mechanisms, and innovative contracting. Developers without credible real‑world evidence (RWE) plans face commercialization delays and price erosion.
- Manufacturing and supply chain gating factors: AAV vector production capacity, GMP consistency for ocular dosing routes, and raw‑material cost volatility remain critical operational constraints. Manufacturing decisions taken in 2026 — insourcing vs. CDMO engagement, fill/finish choices, and scale prioritization — will determine time‑to‑market and per‑patient economics.
Competitive landscape — dynamics and tactical implications
The current developer ecosystem mixes pure‑play biotech innovators, optogenetic pioneers, and stewardship by non‑profit players. Several program transitions and regulatory designations in 2025–2026 are reshaping competitive trajectories:
Worldwide Choroideremia Treatment Market
- Kiora Pharmaceuticals (Encinitas, CA): Advancing a small‑molecule photoswitch platform with demonstrated functional vision endpoints in retinal degeneration programs. Kiora’s non‑viral approach reduces several vector manufacturing risks and presents a differentiated payer narrative focused on repeat‑dosing economics and broader patient applicability. Expansion into choroideremia is plausible, but execution will hinge on robust cross‑disease functional endpoint validation and manufacturing scale for ophthalmic formulation.
- Ray Therapeutics (Berkeley, CA): Building on optogenetic channelrhodopsin technology delivered via intravitreal administration, Ray has secured accelerated regulatory engagement for its lead RTx‑015 program. Intravitreal optogenetics lowers surgical complexity versus subretinal gene replacement, offering a potentially faster commercial route if safety and clinically meaningful vision improvement are demonstrated. Investors and partners should weigh the tradeoffs between novel mechanism advantage and the need for tailored visual rehabilitation services.
- Choroideremia Research Foundation (CRF): The acquisition of a legacy AAV gene replacement program and affiliated natural history datasets positions CRF as a data steward and potential enabler of secondary development or licensing. This stewardship model reduces barrier to entry for follow‑on developers but raises questions on commercialization scale and capital access — an opportunity for strategic collaborations between philanthropic, academic and industry players.
- Legacy and discontinued programs: High‑profile program halts and reprioritisations by larger firms underscore the clinical and commercial uncertainties in the space. These events have produced valuable clinical datasets and argue for re‑purposing assets or forming consortiums to extract patient‑relevant endpoints and comparator data.
Key market dynamics and technology themes
- Endpoint and trial design innovation: Conventional BCVA gains have proven a high bar for many choroideremia candidates. Expect to see increased regulatory acceptance of alternative functional endpoints, composite measures, and patient‑reported outcomes — provided they are validated with robust natural history and longitudinal datasets.
- Platform vs. one‑off therapies: Developers are choosing between platform‑level investments (optogenetics, photoswitches) that can address multiple IRDs, and single‑indication AAV replacements. Platform strategies may offer superior long‑term value and optionality but require different commercialization and payer narratives.
- Manufacturing economics as strategic moat: Control of AAV supply chains, reproducible GMP processes, and scalable intravitreal vs. subretinal delivery capabilities will differentiate winners. Cost models must account for vector yield uncertainties, cold‑chain logistics, and potential repeat dosing in non‑durable modalities.
- Consolidation and data monetization: Asset transfers and foundation stewardship create openings for licensing structures, outcome‑based deals, and pooled real‑world evidence initiatives that can de‑risk late‑stage development and support HTA submissions.
What PW Consulting’s Worldwide Choroideremia Treatment Market report delivers
This report is designed as an operational playbook for executives deciding on investment, partnership, or commercial strategies in 2026. Key deliverables include:
Worldwide Choroideremia Treatment Market
- A validated market model with historical (2020–2025) performance and a granular multi‑scenario forecast through 2032, reflecting varying uptake, regulatory outcomes, and therapeutic durability assumptions (note: detailed segment tables and regional splits are summarized in the full report).
- Competitive intelligence dossiers on all active and legacy programs, including asset histories, trial readouts, strategic moves (acquisitions, discontinuations, designations), and likely commercialization pathways.
- Regulatory playbook mapping FDA/EMA endpoint expectations, orphan/ATMP pathways, and accelerated approval risk matrices tailored to choroideremia modalities.
- Payer and HTA frameworks outlining evidence thresholds, expected price ranges under different durability assumptions, and risk‑sharing templates, including milestone and outcomes‑based contract constructs.
- Manufacturing and supply chain optimization guide covering AAV sourcing strategies, CDMO selection criteria, tech transfer checklists, and cost sensitivity analyses.
- M&A and partnership decision frameworks with trigger maps, valuation levers, and integration risk assessments specific to ultra‑rare ocular programs.
- Due‑diligence checklist and an investor‑oriented valuation workbook that converts clinical and regulatory scenarios into commercial NPV ranges and capital need projections.
Strategic recommendations for 2026
- Adopt a scenario‑based investment approach: fund pilots that preserve upside across efficacy and durability outcomes rather than overcommitting to a single clinical readout.
- Prioritize evidence generation for alternative functional endpoints and long‑term durability: early agreements with regulators and payers on acceptable surrogates will materially reduce commercialization risk.
- De‑risk manufacturing early: secure vector capacity or validated CDMO partnerships with ocular experience, and build contingency plans for yield variability and raw‑material shortages.
- Explore hybrid commercialization models: partnerships with specialized ophthalmic networks and rehabilitation providers can accelerate patient access for optogenetic or photoswitch therapies requiring ancillary services.
- Leverage non‑dilutive capital and philanthropic stewardship: foundations controlling legacy datasets or assets can be strategic allies in de‑risking development and validating endpoints.
- Design payer‑centric clinical programs: incorporate prospective RWE capture, registry alignment, and outcomes measurement that facilitate value‑based contracting.
Concluding perspective and next steps
Choroideremia remains an ultra‑rare indication with outsized scientific interest and complex commercial dynamics. The market is growing rapidly from a small base, concentrated among a few developers and shaped by regulatory endpoint debates, manufacturing constraints, and payer skepticism. For companies, investors, and health systems, 2026 is a moment to recalibrate — to prioritize flexible evidence strategies, secure manufacturing pathways, and align early with payers and patient organizations.
PW Consulting’s full Worldwide Choroideremia Treatment Market report provides the data tables, segmented forecasts, scenario workbooks, and actionable playbooks needed to convert strategic choices into execution plans. For executives who need to move from hypothesis to action in 2026, the report is structured to shorten decision cycles and quantify the impacts of alternative strategies without disclosing the proprietary segmentation that underpins our valuation work.
Contact PW Consulting to request the full report or to schedule a bespoke briefing tailored to your investment, licensing, or corporate development agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Choroideremia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com