

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Solar Laser Drilling Market to Expand at 13.66% CAGR, Reaching USD 1,696.53 Million by 2032 as Asia Pacific Leads with USD 498.01 Million

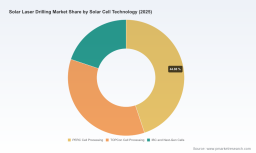
Worldwide Solar Laser Drilling Market — 2026 Strategic Outlook (PW Consulting)
Executive snapshot
PW Consulting’s latest market study, "Worldwide Solar Laser Drilling Market (Base year: 2025; Forecast: 2026–2032)," synthesizes five years of historical performance (2020–2025) and provides a forward-looking, decision‑grade view for corporate strategy teams. The market showed robust expansion from roughly USD 372.4 million in 2020 to approximately USD 692.5 million in 2025. Under our baseline forecast the market is projected to continue expanding at a compound annual growth rate (CAGR) of 13.66% through 2032, reaching an estimated USD 1,696.5 million by 2032. This trajectory reflects a structural shift in photovoltaic manufacturing toward higher-efficiency cell architectures and module designs that place a premium on precision laser processing.
Worldwide Solar Laser Drilling Market
Why this report matters for 2026 decision cycles
-
Capital allocation precision: As manufacturers plan 2026–2027 capital expenditures, the report translates market dynamics into timing signals for laser equipment procurement vs. retrofit.
Worldwide Solar Laser Drilling Market -
Technology selection: We map laser source technologies to near‑term and medium‑term cell technology roadmaps so engineering leaders can align sensor-to-action decisions with R&D and production targets.
Worldwide Solar Laser Drilling Market -
Vendor and sourcing strategy: The analysis gives supply‑chain managers a fact‑based framework for vendor selection, partnership timing, and contingency planning amid rising module design complexity.
-
M&A and partnership readiness: Corporate development teams get scenario frameworks that identify attractive consolidation targets and partnership archetypes across the laser-to-module value chain.
What the study contains — practical, executable deliverables
-
Transparent market-sizing methodology and reconciled historicals (2020–2025) with forecast scenarios through 2032.
-
Demand-driver decomposition linking cell technology adoption, module architecture changes (including double‑glass trends), and downstream system economics to laser drilling requirements.
-
Technology-by-use-case mapping: comparative performance, throughput, and yield implications for nanosecond, picosecond, and femtosecond processing in solar applications.
-
Actionable CapEx playbooks: stepwise guidance for pilot, scale-up and full production, with an integrated payback and sensitivity model (Excel) that you can apply to your factory templates.
-
Vendor scorecards and negotiation playbooks that align technical KPIs (throughput, mean time between failures, maintenance cost) with commercial terms.
-
Policy and tariff scenario analysis with decision trees quantifying order‑book timing risk under alternative trade regimes.
-
Supply‑chain heatmap and risk mitigation checklist focused on critical subcomponents and service footprints for global manufacturing footprints.
Macro and adoption signals to watch in 2026
-
Post‑pandemic capacity rebalancing has given way to strategic investment—but not uniformly. Our interviews and order‑intake tracking indicate pockets of investment caution tied to policy uncertainty and technology transitions.
-
Double‑glass module adoption and cell architecture upgrades continue to push demand for high‑precision glass drilling and back‑side processing. This is a recurring demand vector that will support growth independent of short‑term tariff noise.
-
The market’s concentration profile (CR3 ≈ 42.5%; CR5 ≈ 58.2%) signals a moderately consolidated supplier environment where top vendors command material share while a set of specialized suppliers compete on niche performance dimensions.
-
Technological innovation is accelerating: advances in drilling speed, chipping control, and beam‑delivery systems are compressing unit production costs, but they also raise the bar for incumbent maintenance and upgrade strategies.
Competitive landscape — strategic positioning of key suppliers
-
3D‑Micromac AG (Germany) — Strong in high‑throughput laser micromachining for photovoltaics with product focus on laser contact opening (LCO) and Thermal Laser Separation (TLS) for cell dicing. Their systems are often evaluated where throughput and yield are primary selection criteria.
-
Han’s Laser (China) — A leading supplier of PV glass laser drilling solutions for thin double‑glass modules. Their capabilities are relevant to glass processing specialists and module makers transitioning to heavier double‑glass formats.
-
TRUMPF (Germany) — Major industrial laser systems provider with broad manufacturing credentials; typically selected where integration into large, automated lines and global service coverage are priorities.
-
Coherent Corp. (USA) and IPG Photonics (USA) — Key laser source suppliers with complementary strengths: Coherent in precision sources and system integration; IPG in fiber‑laser power and reliability for high‑throughput applications.
-
Laserax (Canada), Novanta Photonics (USA), SCANLAB (Germany), Rache Corp (USA), Laserod Technologies (USA) — A cohort of specialized providers covering laser cleaning, beam delivery, scanning systems, and ablation techniques. Each is differentiated by focus areas (recycling, scribing, micro‑structuring), and their equipment is often used in targeted optimization projects.
Recent signal events and their strategic implications
-
LPKF’s 2026 earnings and segment commentary noted order intake volatility and highlighted that tariff uncertainty and the perovskite transition are prompting buyers to defer decisions. For strategic planners this underscores the need for decision‑stage models that value optionality and phased investment.
-
BY Photonics’ late‑2025 technology announcement demonstrating sub‑3‑second drilling for thicker PV glass is a reminder that step‑change process improvements can rapidly reset operational benchmarks—pressuring competitors and creating short windows for OEMs to secure differentiated throughput gains.
Five practical strategic recommendations for 2026
-
Adopt a two‑track procurement posture: pilots now, staged rollouts later. Use pilot results to de‑risk full production investments and to validate supplier claims on throughput and yield under your specific cell/module recipes.
-
Align laser technology choices with your cell roadmap, not current production. Different laser classes bring tradeoffs in throughput, edge quality and cost of ownership; ensure your selection supports the cell technologies you plan to scale over the next 3–5 years.
-
Embed tariff and technology scenarios into your procurement contracts. Include clauses for price renegotiation and tech upgrades that reflect the probability of policy shifts or disruptive cell coating adoption.
-
Diversify supplier relationships where service footprint, spare parts availability and regional support are material to uptime. Given the market concentration profile, selective dual‑sourcing is a pragmatic hedge.
-
Monitor upstream module design trends—particularly double‑glass and advanced shingling techniques—because these structural shifts are among the strongest multipliers for laser drilling demand.
Risk scenarios — what could change the outlook
-
Adverse trade policies or protracted tariff uncertainty could delay orders and temporarily compress market growth in 2026–2027.
-
Accelerated perovskite integration would reshape equipment needs, creating both risk and opportunity for laser specialists depending on their ability to adapt processing parameters.
-
Rapid supplier innovation (e.g., dramatic improvements in drilling speed or cost) could shorten product cycles and increase replacement capex requirements for manufacturers that adopted earlier generations.
How corporate teams should use this report in 2026
-
Board and executive teams: use the report’s scenarios and financial models to stress‑test investment proposals and to set realistic timelines for ROIs tied to module price and cell‑efficiency outcomes.
-
Operations and engineering: apply the included throughput and yield models to pilot line specifications; use the vendor scorecards during RFPs to accelerate selection and commissioning.
-
Corporate development and procurement: leverage the M&A playbook and supplier benchmarking to prioritize acquisition targets or strategic supplier partnerships that accelerate capability building.
Next steps — where to get the full intelligence
This release is a strategic preview: it illustrates the direction, scale and decision implications of the solar laser drilling market without disclosing proprietary segment tables and granular regional/application splits that are contained in the full study. The complete report includes downloadable Excel models, detailed regional and application segmentation, vendor financials and contract negotiation templates designed to be used directly in board decks and CapEx proposals. For organizations evaluating manufacturing investments or supplier strategies in 2026, the full dataset and scenario models are essential to convert market insight into executable plans.
PW Consulting invites decision‑makers to review the full report and the associated toolkit to accelerate time‑to‑decision and reduce deployment risk. Contact PW Consulting to request access to the complete analysis and the embedded modeling assets.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com