

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Foot Traffic and Customer Location Intelligence Market Hits USD 8,620.5 Million in 2025, Poised for 15.65% CAGR

PW Consulting: Strategic Brief — Worldwide Foot Traffic and Customer Location Intelligence Solution Market (2026 Outlook)
Executive summary
PW Consulting is pleased to announce the release of our latest market intelligence brief, Worldwide Foot Traffic and Customer Location Intelligence Solution Market. Drawing on a rigorous historical analysis (2020–2025) and a forward-looking forecast (2026–2032), this study synthesizes commercial telemetry, anonymized mobility datasets, sensor deployments and platform economics to quantify an industry that has matured from niche analytics to strategic operating capability.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
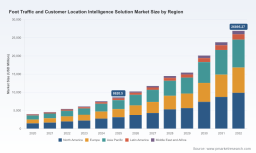
In aggregate terms, the global market expanded from roughly USD 4.02 billion in 2020 to USD 8.62 billion in 2025 and is projected to accelerate through the forecast period—reaching approximately USD 10.24 billion in 2026 and ultimately approaching USD 26.90 billion by 2032. This trajectory represents a compound annual growth rate (CAGR) of approximately 15.65% across the forecast window, underscoring how foot traffic and customer location intelligence are transitioning from point solutions to enterprise-grade decision engines.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Why this report matters for 2026 corporate decision-makers
-
Strategic timing: 2026 is a pivot year. Early adopters who scaled pilots into enterprise deployments during 2023–2025 are now seeking measurable ROI and integration playbooks to govern multi-site operations, omnichannel attribution and revenue uplift modeling.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market -
Economic inflection: The market’s sustained double-digit growth implies that technology selection, data governance and procurement decisions made in 2026 will materially determine multi-year competitive positioning. Implementation choices now will magnify or constrain the potential value that location intelligence delivers at scale.
-
Operationalization challenge: Moving from descriptive footfall metrics to predictive, prescriptive use cases—site selection, cannibalization modeling, workforce scheduling, dynamic pricing and targeted OOH attribution—demands a repeatable, auditable methodology. Our report provides that methodology without substituting for bespoke advisory engagement.
What’s inside the report — practical, execution-oriented content
-
Data architecture blueprints: Recommended pipelines for blending anonymized mobile-derived signals, sensor-based counts (camera/sensor fusion), POI reference data and transaction datasets while maintaining privacy-first processing and compliance constraints.
-
Deployment playbooks: Staged adoption paths for retailers, landlords, transit authorities and venue operators—from proof-of-concept KPIs to enterprise rollouts—aligned to resource profiles (capex vs. opex), integration complexity and expected time-to-value.
-
Vendor selection framework: A decision matrix that weighs product capabilities, data pedigree, integration APIs, professional services depth and contractual constructs (data licensing, SLAs, indemnities). The framework is paired with a reproducible scoring model that procurement teams can apply to their RFP shortlists.
-
Use-case ROI templates: Standardized calculators for estimating incremental revenue, cost avoidance and efficiency gains across common use cases—e.g., site optimization, trade-area analysis, in-store conversion, and out-of-home campaign attribution. Each template highlights critical sensitivity factors and data levers that drive value.
-
Privacy & compliance playbook: Practical controls and process flows to address data sovereignty, localization requirements and cross-border processing considerations, linked to recent legislative and enforcement trends.
-
Scenario-based forecasts: Three executable adoption pathways (conservative, market-parity, accelerated) to stress-test investment decisions under differing macroeconomic and regulatory regimes.
Competitive landscape — positioning the market participants
The market exhibits a classic technology consolidation arc: a relatively fragmented supplier ecosystem where a group of specialist and platform vendors have started to assume leadership roles. Our cr3 and cr5 metrics reflect a market that is consolidating but still leaves substantial opportunity for mid-market and regional players—the top three firms do not yet dominate the majority of market value, and the top five together account for slightly over forty percent of the market.
Key vendor archetypes we observe:
-
Data-first analytics platforms: Providers that build on large anonymized mobility datasets and deliver standardized APIs and dashboards for visitation trends and trade-area analysis.
-
Sensor and on-premise analytics specialists: Companies offering hardware, edge computing and computer-vision-based footfall measurement for indoor accuracy and real-time operations.
-
Enterprise GIS and integration platforms: Established geospatial platforms that act as system-of-records for spatial analytics, enabling large-scale mapping, routing and contextualization of location signals.
Representative companies in these archetypes include established location-intelligence specialists, mobility data aggregators, and sensor manufacturers. Each brings differing strengths: some excel at visit attribution and trade-area modeling, others at in-store conversion analytics and sensor accuracy, while platform incumbents contribute scale and integration breadth. Recent commercial activity illustrates the dynamic interplay between these groups:
-
Placer.ai (Webinar, March 2026) positioned its analytics as central to economic development and retail strategy, speaking to the practical needs of site selection and consumer behavior segmentation in a bifurcated retail environment.
-
Partnerships that embed foot traffic intelligence directly into commercial real estate platforms (e.g., a March 2026 integration announced between a mobility analytics provider and a major RE analytics firm) demonstrate demand for seamless asset-level insights at REIT and portfolio management layers.
-
Product enhancements from specialist vendors continue to push depth in site selection modeling, cannibalization analysis and trade-area overlap: these improvements shrink time-to-insight for customers running competitive-location analyses.
Regulatory, technical and market dynamics that will shape 2026
-
Data sovereignty and cross-border data handling: Several jurisdictions are tightening requirements for storage and processing of personal and derived location signals. Enterprises must architect for local processing where required or select vendors with compliant, localized infrastructures.
-
Law and access regimes: Extraterritorial law enforcement access frameworks have implications for vendors headquartered in certain jurisdictions. Legal exposure can influence vendor selection and contract negotiations, particularly for multinational customers.
-
Spectrum and wireless ecosystem changes: Ongoing regulatory attention to dynamic spectrum management and improved sharing frameworks opens new technical pathways for sensor networks and reduces some constraints on wireless-based sensing—but also introduces new compliance and interoperability requirements for device makers and network operators.
-
Technology evolution: Advances in AI-powered video analytics and sensor fusion increase the accuracy and utility of indoor and storefront measurement, while anonymized mobile tracing continues to excel at macro-level mobility flows. The best outcomes for enterprises come from combining modalities and validating against ground-truth sources.
Strategic implications and recommended executive actions for 2026
-
Plan for a hybrid data architecture: Combine edge-enabled sensors for in-store accuracy with anonymized mobility and POI datasets for market-level context. Design for modularity so you can swap suppliers without re-architecting core systems.
-
Prioritize governance and privacy-by-design: Adopt contractual and technical controls that can flex to regional data sovereignty requirements and withstand legal scrutiny across jurisdictions.
-
Operationalize use cases with value gates: Deploy in iterative sprints tied to explicit KPIs (e.g., lift in conversion, reduction in vacancy days, improvement in campaign ROI). Avoid broad “capture everything” pilots that fail to translate into measurable outcomes.
-
Embed vendor evaluation into procurement: Use a scoring matrix that measures not just feature fit but also data lineage, legal exposure, professional services capability and roadmap alignment with your enterprise stack.
-
Invest in internal capabilities: Build small, cross-functional teams (data, ops, legal, commercial) to own the lifecycle of location intelligence from data ingestion to business outcome.
How to use this briefing — and what we’re intentionally withholding
This briefing is intended to orient senior leaders and procurement teams to the levers and risks that will determine the value of location intelligence investments made in 2026. It highlights the market scale, growth trajectory and practical content we provide. In keeping with PW Consulting’s “teaser” approach, we have deliberately not included the detailed segmentation tables, regional and application-level percentage breakdowns, or vendor scorecard scorecards in this public summary. These granular datasets and company-level assessments are available in the full report and through our advisory engagements, where we tailor insights to client-specific geographies, verticals and tech stacks.
Next steps
-
For procurement teams: Request our vendor selection template and a short-list workshop tailored to your procurement cadence.
-
For business leaders: Use our ROI templates to stress-test near-term investments and quantify expected uplift in 12–24 months.
-
For investors and private equity: Consult our scenario forecasts and market concentration analysis to assess acquisition and partnership targets aligned to your portfolio thesis.
PW Consulting’s Worldwide Foot Traffic and Customer Location Intelligence Solution Market report is designed as an actionable resource for leaders who must convert location-derived signals into defensible business advantage. For access to the full dataset, regional and application-level segmentation, vendor scorecards and bespoke benchmarking services, please visit our report page or contact our advisory team to arrange a tailored briefing.
— PW Consulting, Global Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com