

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Automotive Clamp Market to Expand at 4.6% CAGR as Asia‑Pacific Emerges Dominant

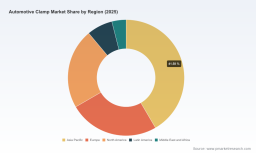
Worldwide Automotive Clamp Market — Strategic Outlook to 2032
Executive preview from PW Consulting
The global market for automotive clamps is on a steady, engineering-driven growth path that matters to OEM procurement teams, tier‑one suppliers, private equity investors, and manufacturing strategists planning for 2026 and beyond. Our new report — Worldwide Automotive Clamp Market (base year 2025, forecast 2026–2032) — synthesizes historical performance, supply‑chain fragilities, regulatory pressures, and competitive moves into an actionable playbook. In aggregate terms, the market has continued to expand through the mid‑2020s and is projected to grow at a mid‑single‑digit compound annual growth rate (CAGR) through 2032, elevating the total market size materially by the end of the forecast window.
Worldwide Automotive Clamp Market
Why this matters for 2026 decisions
- Procurement certainty: With steel and stainless‑steel inputs comprising the majority of production cost for clamps, raw material price volatility can materially alter supplier economics in 12–24 months. Buyers who lock in flexible cost‑pass clauses or secure hedged sourcing will preserve margin and reduce supply risk.
- Manufacturing footprint choices: Automation and capacity investments made in 2024–2025 are already shifting competitive dynamics; suppliers with recent capacity expansions are positioned to capture short‑cycle OEM awards in 2026. Our scenario modelling shows near‑term capacity readiness is a distinguishing factor in supplier selection.
- Product architecture and vehicle programs: Lightweighting and thermal performance are not peripheral: clamp choices influence vehicle mass budgets and thermal integrity across powertrain, cooling, and exhaust systems. Decisions on clamp type and material should be integrated into early vehicle architecture trade‑offs to avoid late‑stage rework.
Market trajectory — concise numbers, strategic implications
Using 2025 as our analytical base, PW Consulting’s baseline forecast anticipates continued market expansion through 2032 at roughly a 4.6% CAGR. That trajectory reflects a combination of steady OEM production volumes, incremental electrification (which redistributes but does not eliminate clamp demand), rising thermal management complexity in both ICE and EV platforms, and ongoing replacement/aftermarket activity. For 2026 specifically, the market grows modestly from the 2025 base — a near‑term continuation of recent recovery and investment cycles rather than a structural inflection.
Worldwide Automotive Clamp Market
Competitive landscape — what buyers and investors need to know
The clamp sector exhibits moderate concentration: the top three suppliers account for a significant share of global revenue, and the top five increase that share materially. This concentration profile creates both risk and opportunity for buyers and private capital. On the one hand, scale players offer reliability, engineering depth, and global footprints; on the other, mid‑tier and regional specialists provide localized agility and tailored product innovations.
Worldwide Automotive Clamp Market
- NORMA Group (Germany): A benchmark for engineered joining technologies, NORMA’s extensive portfolio across worm‑drive, V‑band, and high‑temperature profile clamps positions it strongly for OEM programs requiring integrated sealing solutions. Recent investments in automated clamp production increase scale and cost competitiveness.
- Oetiker Group (Switzerland): Known for single‑ear and multi‑ear solutions, Oetiker differentiates on low‑profile, vibration‑resistant designs favored in fast‑assembly lines and compact packaging environments.
- Ideal‑Tridon Group (US): With a century‑plus heritage, Ideal‑Tridon’s breadth across worm gear, T‑bolt, and constant‑tension clamps—and its expanded distribution network—makes it a reliable partner for both OEMs and heavy‑duty applications.
- Murray Corporation, Breeze (NORMA Americas), Clampco, Mikalor, Rotor Clip, Jolly Clamps, King Seal, Auto Clamp: This mix of global and regional players supplies differentiated strengths—custom engineering, performance exhaust clamps, high‑temperature solutions, and compliance‑focused production—that shape tender outcomes and aftermarket competition.
Recent industry movements underscore the strategic jockeying underway: examples include product launches that reduce component weight (directly supporting OEM lightweighting targets), expanded distribution footprints that shorten lead times, and capacity additions that de‑risk supplier bottlenecks. These are the operational signals procurement teams should monitor as part of supplier scorecards in 2026.
Key dynamics shaping supply and demand
- Raw material sensitivity: Steel and stainless steel represent the dominant input cost for clamps. Price volatility and supply disruptions can add a double‑digit percentage to manufacturing costs in stressed scenarios. Suppliers with diversified metal procurement, long‑term contracts, or alternative material capability (e.g., advanced alloys, coated steels) will be advantaged.
- Regulatory and specification pressures: Automotive clamps must align with industry quality standards such as IATF 16949, and specific types adhere to test protocols (for example, standards covering worm‑drive performance). Thermal and vibration resilience remains mission‑critical—particularly for exhaust and turbo systems where temperatures can exceed conventional limits.
- Design and materials innovation: Lightweighting is driving adoption of advanced materials and re‑engineered clamp geometries to shave component mass without compromising clamp torque and sealing integrity. High‑temperature profile clamps engineered for extreme exhaust environments are increasingly relevant for both high‑performance ICE vehicles and boosted combustion platforms.
- Functional complexity with electrification: EVs reconfigure fluid and thermal subsystems rather than eliminate them. Cooling loops for battery, inverter, and power electronics, plus e‑motor thermal management, create specialized clamp requirements—often favoring constant‑tension or spring-loaded designs to accommodate cyclic thermal expansion.
Practical, actionable contents of the PW Consulting report
The report is designed as a decision tool for 2026 strategy setting. It includes:
- Top‑down market sizing and time‑series growth analysis (historical 2020–2025 and detailed 2026–2032 forecast scenarios), with sensitivity modelling for raw‑material and vehicle production shocks.
- Segment‑level frameworks (by product architecture, application family, and geography) that help prioritize R&D and commercial focus — presented as decision matrices rather than raw granular disclosure in this preview.
- Supplier benchmarking, including capability maps, technology positioning, and go‑to‑market footprints for global, regional, and niche players.
- Supply‑chain stress tests that quantify the impact of metal price swings, lead‑time extensions, and tariff/regulatory shifts on cost structures and supplier viability.
- Commercial playbooks for OEMs and suppliers: sourcing strategies, near‑shoring vs. low‑cost location trade‑offs, contract structures to share raw material risk, and integration checklists for early vehicle program phases.
- Technology deep dives on lightweight materials, high‑temperature profiles, constant‑tension designs, and assembly automation — with engineering performance considerations and typical cost‑benefit timelines.
- M&A and partnership pipeline analysis highlighting value creation levers for scale consolidation, capability acquisition, and regional roll‑ups.
How executives should use this intelligence in 2026
- Supply strategy: Revise supplier scorecards to weight capacity readiness and raw‑material sourcing strategies as highly as unit price. Where possible, secure optionality through approved‑vendor lists rather than single‑source commitments.
- Product integration: Treat clamp selection as an early systems decision in vehicle architectures — especially for thermal and exhaust systems. Bring clamp engineers into vehicle program gating to avoid late cost and performance corrections.
- Investment focus: Prioritize investments in automation and high‑temperature manufacturing capability if targeting premium powertrain or performance segments. For financial sponsors, target firms with proprietary clamp geometries or materials know‑how that enable higher margin retrofit or aftermarket products.
- Risk management: Build inflationary scenarios into supplier contracts and consider collaborative hedging for critical metal inputs. Evaluate near‑term inventory strategies for high‑risk commodities without creating excess obsolescence exposure.
Where the report adds unique value
PW Consulting’s analysis combines engineering sensitivity (thermal, vibration, and material science constraints) with commercial market modelling to bridge the common gap between product engineering and procurement decision‑making. Rather than present raw segment figures upfront, our study translates those internal data into prioritized action items — enabling executives to make faster, higher‑confidence choices in 2026 while preserving the granularity for licensed subscribers who need to execute tactical moves.
Next steps — get the full dataset and supplier dossiers
This preview highlights the strategic contours and decision imperatives. For procurement teams, investors, and OEM program leads seeking the underlying segment matrices, supplier scorecards, and full scenario outputs (including the granular product and regional splits not shown here), please visit the PW Consulting report page. The full report contains the detailed figures, appendices with supplier contact maps, and editable Excel models you can integrate directly into 2026 planning workflows.
PW Consulting remains available to brief executive teams, run bespoke supplier due‑diligence projects, and co‑develop procurement strategies keyed to 2026 program calendars. In a market where small design choices cascade into program costs and thermal reliability, the right intelligence now determines competitive position tomorrow.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com