

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Isononyl Acrylate Market Poised for 5.45% CAGR in 2026–2032, Unlocking Global Growth

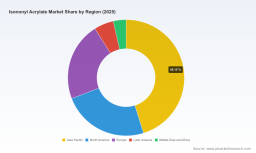
Worldwide Isononyl Acrylate Market: Strategic Intelligence for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market brief on Worldwide Isononyl Acrylate (INA) delivers forward-looking strategic intelligence tailored for executives making capital allocation, procurement, and M&A decisions in 2026. Our analysis synthesizes primary interviews, proprietary shipment and pricing models, and a detailed supply-demand baseline that values the global INA market at USD 218.45 Million in 2025 and projects growth to USD 316.72 Million by 2032, reflecting a 5.45% compound annual growth rate (CAGR) across the 2026–2032 forecast window. We have calibrated this outlook to current feedstock dynamics, regulatory developments, and evolving end-use markets—highlighting where value will emerge and where risk concentrations are likely to compress margins or trigger strategic responses.
Worldwide Isononyl Acrylate Market
Why INA matters in 2026
Isononyl Acrylate plays a pivotal role in formulations for pressure-sensitive adhesives, UV-curable resins, industrial coatings, and specialty elastomers. Its technical profile—combining flexibility, low volatility, and compatibility with radiation-curable systems—keeps the molecule at the intersection of performance-led product innovation and cost-sensitivity. That intersection is where procurement teams, product strategists, and investors must make trade-offs in 2026: secure reliable, low-carbon supply; defend margin against feedstock inflation; and extract value from formulation-led differentiation.
Worldwide Isononyl Acrylate Market
Market dynamics and macro drivers
Three macro forces are shaping INA strategy in 2026:
Worldwide Isononyl Acrylate Market
- Feedstock and upstream cost volatility: Short-term swings in isobutene and acrylic acid markets have direct pass-through effects on INA production economics. Recent spot observations show isobutene trading dynamics tightening and acrylic acid experiencing upward pressure, both of which matter to manufacturers who either vertically integrate or source monomers on the merchant market.
- Regulatory and carbon cost exposures: REACH updates through 2025 confirm INA’s current compliance status in the EU, removing a near-term regulatory overhang. However, new trade instruments like the EU Carbon Border Adjustment Mechanism (CBAM), effective from January 2026 for qualifying imports, introduce a cost dimension tied to embedded emissions—an input that will change supplier economics and buyer sourcing strategies for non-EU producers.
- Consolidation and concentration: The sector exhibits moderate concentration among the top participants. Market concentration metrics indicate meaningful market power resides with a handful of players, which affects pricing dynamics, contract terms, and the strategic calculus for new entrants or capacity expansions.
Supply chain pressure points
INA’s upstream feedstocks—principally isononyl alcohol (linked to isobutene availability) and acrylic acid—are subject to wider petrochemical cycles. In early 2026, isobutene spot levels reflected tighter petrochemical balances; acrylic acid showed month-on-month increases in Asia driven by propylene tightness. Producers with backward integration into monomer production or long-term off-take agreements are better positioned to manage short-cycle price shocks; merchant-dependent processors face margin squeeze unless they implement dynamic pass-through or hedge strategies.
Regulatory overlay: compliance and carbon pricing
The regulatory landscape is bifurcating commercial risk. On one hand, INA’s REACH registration status is stable with no new Annex XVII restrictions as of the 2025 update, simplifying market access for compliant producers. On the other hand, carbon-related trade measures (notably EU CBAM) create a new cost vector for non-EU exporters whose embedded emissions exceed defined thresholds. Strategically, this means buyers in regulated jurisdictions will increasingly value low-carbon provenance and traceability—factors that influence long-term contracts, supplier qualification, and the premium paid for certified low-emission volumes.
Competitive landscape: who matters and why
The INA supplier set is populated by established specialty chemical groups and regional manufacturers. Key players we profile in the full report include:
- Sartomer (Arkema): A global specialty acrylates platform with deep technical capabilities in UV/EB-curable chemistries and a broad commercial footprint. Sartomer’s strength lies in formulation expertise, global customer relationships, and the ability to bundle product and application support—advantages that translate into differentiated value beyond spot pricing.
- Miwon Specialty Chemical: A South Korea–based producer with targeted product positioning in radiation-curable systems. Their strengths include regional cost competitiveness and established ties with Asia-based formulators, which make them an important supplier for companies optimizing regional supply chains.
- Sanfer Noury: An Italian specialty producer focused on European markets, leveraging proximity to end users in adhesives and coatings. Their value proposition centers on service responsiveness, regulatory familiarity, and local quality certainties.
- KOHC (Kumho Oil Chemical Industrial): Part of a broader industrial portfolio, KOHC supplies INA as a complement to its acrylic monomer offerings. Its industrial scale and integration can be an advantage for large-volume customers seeking stable throughput and single-vendor simplicity.
Collectively, the top three to five firms exert a measurable influence on pricing and availability, underscored by the market concentration ratios included in our analysis. That dynamic creates winners and losers depending on a buyer’s negotiation leverage, geographic exposure, and willingness to pay for ancillary services (technical support, low-carbon certificates, guaranteed delivery windows).
Strategic implications for manufacturers and buyers in 2026
- For producers: Prioritize feedstock security and decarbonization pathways. Options include long-term upstream contracts, selective backward integration, or investment in lower-emission production technologies. Consider strategic partnerships with formulators to co-develop low-carbon product grades that command a premium in regulated markets.
- For buyers (formulators, adhesive and coatings OEMs): Reassess supplier qualification criteria to incorporate embedded emissions and supply resilience. Move beyond price-only sourcing by introducing a two-track procurement strategy—spot coverage for flexibility and contracted volumes for security and traceability.
- For investors and M&A teams: Target assets that combine technical IP, regional logistical advantages, and decarbonization credentials. Given the moderate-to-high concentration in the industry, bolt-on acquisitions that expand technical capabilities or market access are likely to deliver higher value than purely capacity-driven plays.
Scenario planning: three plausible 2026–2028 trajectories
Our scenario framework—detailed in the full report—helps executives stress-test investments and contracts across three pathways: Baseline (gradual recovery and 5–6% CAGR), Feedstock Shock (sustained upstream tightness with margin pressure), and Low-Carbon Premium (policy-driven demand for certified low-emission volumes). Each scenario is mapped to actionable operational responses, pricing frameworks, and suggested contract structures to protect margin and market share.
What PW Consulting’s report delivers (practical contents)
The published study is designed as an operational toolkit for the 2026 planning cycle. Key deliverables include:
- Bottom-up market model with historical shipment series and a transparent forecasting engine (2020–2032) that supports sensitivity testing against feedstock and demand shocks.
- Supply-side database detailing producer footprints, capacity typologies, and qualitative capacity-addition timelines.
- Competitive profiles and capability matrices for leading and challenger suppliers, emphasizing formulation support, geographic reach, and decarbonization readiness.
- Procurement playbooks and sample contract clauses for volume security, pass-through mechanisms, and carbon attribution.
- Risk and opportunities matrix, including regulatory exposure mapping (CBAM implications) and feedstock vulnerability scoring based on recent market observations.
- Actionable M&A screening criteria with hypothetical deal scenarios, valuation sensitivities, and integration risk checklists.
- Appendices with primary research transcripts, methodology notes, and data tables—designed for executive and operational use.
How leading firms should use this intelligence in 2026
We recommend three immediate steps for senior executives:
- Initiate a supplier carbon audit and include carbon-cost forecast scenarios in budget planning to model CBAM impacts on supply economics.
- Lock in a portion of 2026–2027 volumes under dual-track agreements: fixed-price collars with an embedded carbon reconciliation clause and a flexible tranche priced to market, enabling tactical arbitrage during dislocations.
- Prioritize R&D and customer co-development on low-emission or differentiated INA-based formulations to capture margin upside as buyers pay a premium for sustainability and performance.
Conclusion — how this report creates strategic value
For decision-makers planning resource allocation, contractual commitments, or M&A activity in 2026, our INA market intelligence turns complexity into a structured set of choices. By quantifying the market trajectory (USD 218.45 Million in 2025 to USD 316.72 Million in 2032 at a 5.45% CAGR) and overlaying the latest supply, feedstock, and regulatory signals, PW Consulting gives you a defensible basis for negotiating supply, prioritizing investments, and designing risk-mitigating commercial terms. The full report elaborates the data, scenario outputs, and executable playbooks that operational teams can implement immediately.
Next steps
To access the complete dataset, granular segmentation tables, and our primary-source interview extracts that underpin these conclusions, visit the PW Consulting report page for the Worldwide Isononyl Acrylate Market. The full analysis is purpose-built to support 2026 planning cycles and will equip your team to convert market intelligence into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Isononyl Acrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com