

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Nursing Mannequin Market to Reach USD 1,264.08 Million by 2032, Growing at 8.12% CAGR in 2026–2032
By pmarketresearch, 2026-07-15
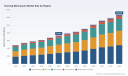
Worldwide Nursing Mannequin Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on the Worldwide Nursing Mannequin Market delivers a timely, actionable briefing for executives preparing budgets, product roadmaps, and M&A strategies for 2026. The report synthesizes a robust historical series (2020–2025) and a forward-looking forecast (2026–2032) showing a clear, sustained growth trajectory — the market is estimated at USD 731.86 Million in 2025 and is projected to reach approximately USD 1,264.08 Million by 2032, representing a compound annual growth rate (CAGR) of 8.12% across the forecast window. These headline metrics frame a market opportunity driven by growing demand for experiential nursing education, expanded use of simulation across clinical settings, and accelerating technology integration in training devices.
Worldwide Nursing Mannequin Market
Why this study matters for 2026 decision cycles
- Capital allocation: Institutional buyers and manufacturers alike need to align 2026 capex and R&D budgets with a market that is expanding at mid-single-digit to low-double-digit rates — not a commodity market, but far from a niche.
- Competitive dynamics: Market concentration metrics indicate a moderate incumbent advantage (CR3 ~48.6%, CR5 ~62.2%), which creates room for focused challengers and niche specialists to capture share through product differentiation and service models.
- Procurement timing: As simulation-based competency assessments become embedded in curricula and regulatory frameworks, the timing and structure of purchasing cycles (hardware vs. software, one-off vs. subscription) will materially affect total cost of ownership and adoption speed.
- Strategic positioning: Suppliers that convert one-time hardware sales into recurring revenue through digital platforms, content libraries, and service bundles will compound value over multi-year customer lifetimes.
What the report delivers — practical, operational intelligence
This report was designed as a decision-support tool, not simply an academic exercise. It combines market sizing and forecast models with operational playbooks for both buyers and sellers. Key deliverables include:
Worldwide Nursing Mannequin Market
- Validated market sizing and a transparent forecast methodology covering 2020–2032, with scenario and sensitivity analyses that reflect cost, adoption and policy risk vectors.
- Segmentation across region, product fidelity (high/medium/low), and end-user categories, each accompanied by demand drivers, adoption barriers, and normalized unit economics. (Note: detailed segment tables and line-item forecasts are reserved for the full report.)
- Competitive profiles and capability maps for leading vendors, including product portfolios, distribution models, R&D focus, and aftermarket support strategies.
- Procurement playbooks and TCO calculators that translate vendor quotes into multi-year value propositions — a practical tool for CFOs and directors of simulation centers.
- Regulatory, quality and standards briefing that highlights certification expectations (e.g., ISO-based quality systems) and training-program obligations that influence purchasing decisions.
- Implementation guides and learning-path templates to accelerate deployment and measurable learning outcomes for nursing schools, hospitals, and military trainers.
Industry context and product realities
End-users value realism, durability and reusability. Typical nursing patient care manikins are engineered for articulated limb movement, washable skin surfaces, injection practice areas and modular features that support a broad set of care procedures. Compliance and quality management remain central to manufacturer claims — ISO-aligned systems and vendor certifications are common differentiators. Separately, regulatory frameworks and training standards (including those tied to competency evaluation programs) are actively shaping product requirements and procurement checklists. Finally, suppliers and buyers must manage the perennial distinction that these devices are simulation tools for educational use and not clinical treatment devices.
Worldwide Nursing Mannequin Market
Competitive landscape: incumbent strengths and tactical openings
Our vendor review focuses on market leaders and strategically relevant challengers. Each firm brings a distinct set of capabilities and strategic options:
- Laerdal Medical (Stavanger, Norway): Deep expertise in scenario-based simulation and a track record of integrating advanced physiological simulation modules. Recent product-level integrations highlight the company’s emphasis on high-fidelity respiratory and critical-care scenarios, an advantage for clinical skills centers prioritizing advanced patient simulations.
- Gaumard Scientific (Miami, USA): Strength lies in multipurpose nursing simulators and a consistent program of catalog refreshes and educational packages that serve curriculum-driven buyers. Their product cadence supports institutions iterating on training programs rather than one-off purchases.
- Kyoto Kagaku (Kyoto, Japan): A reputation for manufacturing quality and certification alignment. Their products address day-to-day patient-care training with robust quality management systems that appeal to buyers prioritizing compliance and lifecycle reliability.
- 3B Scientific (Hamburg, Germany): Offers scenario-focused manikins with modular options useful in clinical skills training. Their strengths include an ecosystem approach that supports multiple use-cases across basic to advanced skills.
- Nasco Healthcare / Simulaids (Wisconsin, USA): Practical, value-oriented trainers and weighted care devices that serve high-volume, skills-practice environments — an important segment where affordability and robustness matter most.
- CAE Healthcare / Elevate (Montreal, Canada): Brings systems integration and software value propositions to nursing manikins, positioning for buyers seeking integrated simulation suites with advanced analytics and interoperability.
- Limbs & Things (Bristol, UK): Focuses on clinically realistic full-body solutions and a learning-design-centric portfolio that serves educators emphasizing hands-on fidelity.
Recent vendor activity points to three market realities: (1) ongoing product integration between physiological simulators and mannequin platforms; (2) continued catalog expansion and distribution partnerships; and (3) distributors consolidating product access through multi-brand catalogs. These dynamics favor vendors that can demonstrate system-level value — physical fidelity plus content, assessment and service — rather than hardware-only offerings.
Strategic recommendations for 2026 — for suppliers
- Shift to outcomes-based selling: Build curricula-linked content packages and prove impact through measurable competency outcomes to support premium pricing.
- Monetize software and services: Introduce subscription tiers for scenario libraries, performance analytics and remote instructor tools to stabilize revenue and reduce the sales cycle friction of capital approvals.
- Pursue modularity and upgrade paths: Design platforms with clear upgrade options (sensor packs, new physiology modules) so customers can protect their initial investment and vendors can capture repeat sales.
- Strengthen partnerships with educational networks: Co-develop pilot programs with large nursing schools and hospital systems to create reference clients and shorten adoption times for larger tenders.
- Operational resilience: De-risk supply chains for key components and build local service footprints where aftersales response times determine purchase decisions.
Strategic recommendations for buyers — for hospitals, schools and defense clients
- Adopt lifecycle budgeting: Evaluate equipment purchases on a five- to seven-year TCO basis, including consumables, software licenses and service-level agreements rather than only purchase price.
- Run structured pilots: Use short, measurable pilot programs to validate learning transfer and institutional fit before scaling procurement across campuses or networks.
- Prioritize interoperability: Select platforms that can integrate with LMS systems, performance analytics and existing AV infrastructure to avoid vendor lock-in and redundant spend.
- Bundle procurement with faculty development: Procurement success correlates with educator readiness; include instructor training and content adoption in RFPs.
Risks, scenarios and planning triggers
- Regulatory shifts: Changes in training standards or certification requirements can accelerate demand but may necessitate product modifications — monitor regulatory calendars closely.
- Technology obsolescence: Rapid advances in AR/VR and sensor technologies could reframe fidelity expectations; maintain a watchlist of adjacent technology providers for potential partnerships or acquisitions.
- Financial pressure: Capital-constrained buyers may favor lower-fidelity or used equipment, pressuring manufacturers on price — counter with service differentiation and outcome guarantees.
- Consolidation: Increased M&A among distributors or north-star vendors could alter channel economics; maintain flexible channel arrangements and direct relationships with end-users.
How to use this report in 2026 planning
Boardroom and operational teams should treat the report as a playbook for translating market momentum into executable initiatives. Recommended first steps for 2026:
- Executive brief: Use the report’s one-page market brief and scenario outputs to align the executive team on growth assumptions and investment priorities.
- Product roadmap alignment: Map your current and planned product capabilities against the report’s capability matrix and reallocate R&D funding to high-opportunity gaps.
- Procurement templates: Adopt the report’s RFP checklist and TCO model to standardize purchasing and reduce negotiation cycles.
- M&A screening: Leverage the vendor scorecard to identify tuck-in targets that fill capability gaps (e.g., software analytics, scenario libraries, regional service networks).
- KPIs: Track acquisition conversion, attach rate for services, customer NPS and churn for subscription elements as early indicators of strategic success.
PW Consulting’s analysis provides the strategic framing and the operational instruments needed to convert market growth into defensible commercial outcomes in 2026. For decision-makers seeking the granular, segment-level forecasts, vendor scorecards and the procurement playbooks referenced here, the full study contains the detailed tables and annexes that support execution planning. Accessing the full report will provide the data granularity required for vendor selection, budgeting and risk modeling.
Contact PW Consulting to request the comprehensive report and the custom briefing package that translates these insights into a 90‑day action plan tailored to your organization’s role in the nursing mannequin ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Nursing Mannequin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Omni‑channel & Warehouse Management Systems Market to Reach USD 12,459.13 Million by 2032, Driven by a 13.98% CAGR
By pmarketresearch, 2026-07-15
Worldwide Omni-channel and Warehouse Management Systems Market — Strategic Imperatives for 2026
PW Consulting today publishes an executive preview of our flagship market study, Worldwide Omni-channel and Warehouse Management Systems Market (Base Year 2025; Forecast 2026–2032). The analysis reconfirms that warehouse execution and omni-channel orchestration are no longer niche IT projects but strategic platforms shaping go-to-market agility, compliance resilience, and cost-to-serve across supply chains. Our modeled global market reached approximately USD 4,985 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 13.98% through the forecast horizon. By 2032 the market is expected to more than double from today’s baseline, underscoring the urgency of programmatic investment decisions in 2026.
Worldwide Omni-channel and Warehouse Management Systems Market
Why this report matters to executive decision-makers in 2026
- Timing and leverage: With the market accelerating, 2026 is a pivotal year for deciding whether to modernize incrementally or to fund transformational warehouse and omni-channel platforms. The pace of adoption—and the integration of WMS/WES with OMS, TMS and automation—will determine which players capture disproportionate operational value.
- Risk mitigation for compliance-heavy sectors: Strengthened traceability mandates (for example, drug and food safety directives) make advanced lot/serial tracking and automated audit trails mandatory capabilities. The report maps the regulatory vector and shows where investments produce compliance with minimal ongoing lift.
- Quantified operations impact: Leading WMS/WES deployments deliver measurable throughput and availability gains. Our synthesis of practitioner data shows typical throughput improvements of 15–25% and reductions in downtime up to 30%, metrics critical for ROI conversations with CFOs and COOs.
- Vendor consolidation dynamics: Market concentration is increasing—our analysis shows the top three vendors account for roughly one-third of market value while the top five approach half the market—creating competitive dynamics that influence pricing, integration ecosystems, and partner strategies.
What the PW Consulting report contains — practical, executable content
This study is designed to be operationally useful to CIOs, supply chain heads, and digital transformation sponsors. The deliverables include:
Worldwide Omni-channel and Warehouse Management Systems Market
- Proprietary market model (2020–2032) with scenario layers for adoption curves, cloud migration rates, and automation penetration.
- Vendor landscape and scorecard covering product capability, integration breadth, cloud maturity, vertical fit, and partner ecosystems—enabling shortlists for RFPs.
- Decision frameworks for build vs. buy vs. partner, including TCO and multi-year ROI templates tailored to enterprise, mid-market, and 3PL profiles.
- Implementation playbooks: phased migration roadmaps, data migration checklists, cutover sequencing, and KPI dashboards for continuous improvement.
- Automation and integration playbooks: WMS-to-WES-to-WCS/robot orchestration, API patterns, and best-practice conveyor/robot control strategies.
- Compliance and security annexes that translate evolving traceability and data-protection mandates into testable system requirements and audit procedures.
- Operational case studies and vendor-neutral sample contracts that accelerate procurement and reduce negotiation cycles.
To preserve the value of the full dataset for licensed subscribers, this release intentionally omits granular split data for regions, deployment models, and end-users. The full report contains those segment-level insights together with downloadable spreadsheets and an interactive scenario tool.
Worldwide Omni-channel and Warehouse Management Systems Market
Market dynamics shaping vendor selection and implementation
- Cloud-first economics: Cloud-native WMS/WES deployments have achieved material adoption—approximately half of new deployments in 2026—driven by lower upfront capital, elastic scaling for peak seasonality, and continuous functional updates. Buyers must weigh operational flexibility versus long-term hosting cost trajectories.
- Labor dynamics and productivity: Chronic labor shortages and rising wage pressure tilt investment calculus toward systems that materially lift throughput and reduce idle time. Buyers should demand validated productivity metrics and ensure SLAs reflect realized throughput gains.
- Compliance and traceability: Stricter global regulations (e.g., pharmaceutical serialization and food safety directives) have made built-in traceability and auditability baseline requirements. Systems that automate compliance updates and maintain immutable audit trails reduce recall and compliance risk.
- Security and data governance: As logistics platforms centralize operational data, security controls, role-based access, encryption, and continuous risk monitoring are core procurement criteria—especially for multi-tenant cloud offerings.
- Integration with automation and transportation: The most successful deployments are those where WMS/WES, WCS, TMS and OMS form a cohesive orchestration layer. Recent industry M&A and partnerships reflect a move toward tighter execution suites rather than point solutions.
Competitive landscape — what to expect from leading suppliers
The ecosystem is populated by established tier-1 suite vendors, specialized WMS providers, and regional champions. The CR3 and CR5 concentration metrics indicate a market in which scale provides negotiating and integration advantages, but midsize and niche vendors continue to win on vertical specialization and implementation speed.
- Manhattan Associates: A market-recognized leader with a cloud-native WMS that emphasizes omni-channel fulfillment, real-time visibility, and labor optimization. Recognized repeatedly in industry benchmarks, it remains a go-to for complex, global retailers and distributors.
- Blue Yonder: Offers mature WMS functionality paired with workforce and returns management, increasingly layering AI-based orchestration for highly dynamic distribution networks.
- SAP: SAP EWM is positioned for enterprises seeking deep ERP-supply chain alignment, enabling organizations to leverage a common master data fabric at scale.
- Oracle: Oracle’s cloud WMS and NetSuite options suit organizations prioritizing integrated ERP-to-WMS stacks and unified financial/operational reporting.
- Infor: Focuses on warehouse operations and 3PL capabilities with a cloud-first posture attractive to manufacturing and food & beverage customers.
- Körber Supply Chain (Infios): Following its rebrand and strategic acquisitions, the vendor is bundling WMS, WCS and TMS capabilities to reduce planning silos and support heavy automation footprints.
- Specialists & regional leaders: Firms such as Softeon, Tecsys, Deposco, Made4net, Mecalux and Generix Group offer strong vertical or regional propositions—particularly attractive for mid-market, healthcare, and 3PL-specialized use cases.
- Systems integrators & transformation partners: Logistics-focused consultancies and SI partners bring critical domain experience; their selection is often as decisive as the software choice itself.
Recent strategic moves validate these dynamics: Körber’s acquisition of MercuryGate (Oct 2025) underscores the convergence of transport and warehouse execution; Hardis’s expansion with cloud and automation partners (Jan 2026) demonstrates the premium on partner ecosystems; Honeywell’s launch of a cloud WES (Mar 2025) signals increased vendor focus on real-time orchestration.
Practical guidance for procurement and leadership teams
- Define outcome-based KPIs first: Begin with measurable outcomes—order cycle time, perfect order rate, cost-to-serve—then map functionality and integration needs to those KPIs.
- Pressure-test vendor claims: Require references with similar volume and automation profiles, and insist on performance-based acceptance criteria tied to throughput and availability.
- Adopt phased migration: Start with a controlled scope (select SKUs, a single DC, or a single fulfillment channel) to de-risk integration and accelerate time-to-value.
- Plan total-cost-of-ownership: Model multi-year cloud hosting, licensing, integration, and continuous improvement costs rather than comparing upfront license fees alone.
- Preserve flexibility: Architect for modularity—APIs, event-driven integrations, and container-friendly deployments preserve optionality as automation and robotics evolve.
Risks and scenario thinking for 2026
- Cloud hosting cost volatility: The economics of cloud are favorable for elastic scale, but buyers should stress-test projections for large data, edge-processing and peak seasonism to avoid surprise cost escalation.
- Regulatory shocks: Rapidly changing traceability and data residency rules can force unplanned remediation—choose solutions with rapid compliance update paths.
- Integration complexity: The promise of end-to-end orchestration is only realized where rigorous data governance and C-suite sponsorship are in place.
- Vendor concentration effects: Consolidation can reduce choice and increase integration lock-in; balanced procurement should combine strategic partnerships with competitive benchmarks.
Next steps — how PW Consulting helps
Our full report offers the granular, actionable intelligence that procurement, operations and IT teams need to make defensible investment decisions in 2026. Subscribers receive the market model, vendor scorecards, implementation templates, and country- and vertical-level forecasts to tailor programs to their risk profile.
For senior leaders preparing board-level business cases, our research provides the quantified rationale and implementation risk mitigation playbooks to accelerate approvals and ensure measurable outcomes. Note: this press release deliberately omits segment-level splits and detailed vendor financials to preserve the integrity of the licensed dataset—these are available in the full, downloadable report.
PW Consulting’s Worldwide Omni-channel and Warehouse Management Systems Market study is designed as a hands-on guide for executives who must translate market momentum into repeatable operational advantage. In a market growing at nearly 14% annually and reshaped by cloud, automation, and regulation, 2026 will be the year teams either secure durable competitive advantage or accept escalating operating costs and compliance risk. The choices you make now will define logistics performance for the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Power Energy Management System (EMS) Market Poised for Rapid Growth — 13.52% CAGR Forecast (2026–2032)
By pmarketresearch, 2026-07-15
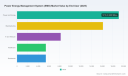
Worldwide Power Energy Management System (EMS) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting's latest market study on the Worldwide Power Energy Management System (EMS) market delivers a compact, high-conviction synthesis of the forces shaping procurement, investment, and competitive strategy entering 2026. This preview outlines the report’s strategic value for executive teams and investment committees while deliberately reserving full, granular segment and regional tables for the complete report. The intent is to equip leaders with the right questions, priority actions, and risk signals so they can act confidently while motivating deeper engagement with the underlying datasets.
Worldwide Power Energy Management System (EMS) Market
Executive snapshot: momentum, scale, and visibility
Between 2020 and 2025 the global EMS market experienced sustained expansion, reflecting the rapid adoption of digital grid controls, distributed energy resource (DER) orchestration, and asset-level optimization. On a headline basis, total market revenue expanded from USD 29,482.15 Million in 2020 to USD 54,318.94 Million in 2025. PW Consulting’s base-year analysis (2025) and scenario modeling across the 2026–2032 forecast window point to a compound annual growth rate (CAGR) of 13.52%, with total market size modeled through multiple macroeconomic, regulatory, and technology adoption trajectories. By the end of the forecast horizon, the market is projected to reach USD 131,964.75 Million—a scale that materially changes supplier economics, procurement levers, and M&A dynamics.
Worldwide Power Energy Management System (EMS) Market
Why this matters for 2026 strategic decisions
- Capex and procurement timing: The market’s rapid expansion compresses windows where technology choices are defensible for the long term. Organizations that delay standardization risk costly rip-and-replace cycles as interoperability norms consolidate.
- Vendor selection and partnerships: A moderate-to-high concentration among top suppliers shapes the bargaining landscape. Our concentration metrics show that top-three vendors command roughly one-third of the market while the top-five approach a majority share—an important input when assessing negotiation leverage and strategic partnerships.
- Regulatory runway: Recent code and policy movements are shifting functional requirements for EMS deployments, creating new compliance tasks and commercial opportunities for products that can certify to fresh standards.
- Service monetization: As systems scale, services and software monetization strategies (subscriptions, performance contracting, managed services) become central to total cost of ownership (TCO) and to recurring-revenue valuation models.
Market dynamics that will define winners and losers
- DER integration and virtual aggregation: National and regional policy updates—most notably roadmaps to large-scale virtual power plant aggregation—are raising functional requirements for EMS platforms. These platforms must now perform high-fidelity forecasting, secure bidirectional control, and market participation functions at scale.
- Standards and safety: The 2026 National Electrical Code update (relocating EMS provisions and clarifying distinctions between EMS and Power Control Systems) introduces compliance differentiation. Systems that clearly map to the updated Article 130 will gain procurement preference among regulated utilities and critical infrastructure operators.
- Grid modernization and transmission expansion: Transmission buildouts and utility-grade EMS upgrades (including approved upgrade projects at major ISOs) elevate demand for solutions that can ingest SCADA, phasor, and market data with low-latency analytics and deterministic control loops.
- Software-first architectures: Platforms that separate control-layer determinism from analytics and orchestration are preferred for scalability. This shift favors vendors with open APIs, edge-to-cloud strategies, and robust cybersecurity architectures.
- Economics of electrification: Rapid load growth in select geographies—driven by electrification of transport and digital infrastructure—creates asymmetric demand pockets that suppliers and system integrators must address with localized delivery models.
Competitive landscape — who to watch and why
The EMS vendor landscape remains a mix of global industrial conglomerates, specialized power-technology firms, and software-native challengers. PW Consulting’s strategic benchmarking flags a cohort of incumbent leaders and important innovators whose product portfolios and go-to-market footprints will shape 2026 outcomes. Representative profiles included in the report include:
Worldwide Power Energy Management System (EMS) Market
- Siemens AG (Munich, Germany) — Offers comprehensive grid-scale EMS solutions focused on transmission, generation optimization and renewables integration; a leader in utility-grade spectrum-level control capabilities.
- Schneider Electric SE (Paris, France) — Strength in facility- and grid-edge EMS platforms and extensive investments to expand digital service delivery across industrial and large commercial customers.
- ABB Ltd (Zurich, Switzerland) — Emphasizes real-time monitoring and control across industrial power applications; strong systems integration pedigree for large capital projects.
- GE Vernova (Boston, USA) — Focused on transmission and generation asset digitalization with solutions optimized for grid-scale operations and asset health analytics.
- Honeywell International Inc. (Charlotte, USA) — Targets industrial EMS and demand-response use cases with integrated service offerings.
- Eaton Corporation plc (Dublin, Ireland) — Known for power distribution, branch monitoring, and reliability-centered EMS deployments.
- Emerson Electric Co. (St. Louis, USA) — Focused on generation and process control platforms with deterministic control capabilities.
- Johnson Controls International plc (Cork, Ireland) — Strong presence in building-focused EMS and growing digital services revenue in North America.
- Rockwell Automation Inc. (Milwaukee, USA) — Integrates EMS capabilities with factory automation, optimizing energy in manufacturing operations.
- Mitsubishi Electric, Yokogawa, Hitachi Energy — Each brings regional strengths, deep control-systems experience, and differentiated offerings suited to specific utility and industrial applications.
PW Consulting’s competitive maps are built to support three strategic use-cases: supplier shortlisting, partner due diligence, and acquisition target screening. While the preview highlights vendor capabilities, the full report provides detailed vendor scorecards, capability matrices, and reference deployments.
Regulatory and policy tailwinds — implications for procurement and compliance
- Code renewal and functional clarity: The NEC 2026 relocation and clarifications for EMS vs. PCS functions introduces new compliance checkpoints that buyers must include in RFPs and test procedures.
- DER aggregation targets: Government-led VPP roadmaps place new performance obligations on EMS platforms to support grid services markets and aggregated resource participation.
- Standards alignment: ISO 50001 and other energy management standards continue to influence specification language for performance guarantees and energy savings verification.
What the PW Consulting report delivers — an action-oriented toolkit
Beyond market sizing and forecasts, the report is structured around the tactical needs of CFOs, CTOs, system integrators, and utility procurement teams. Key deliverables include:
- Scenario-based financial models to stress-test TCO across hardware, software, and services bundles under alternative adoption curves.
- Vendor evaluation frameworks with weighted scoring across technical fit, scalability, integration cost, cyber posture, and business model (license vs. SaaS vs. managed services).
- Implementation playbooks for pilots and rollouts—including test plans aligned to the updated NEC functional requirements and market participation criteria for VPPs.
- M&A and partnership pipelines highlighting adjacent technology providers where buy-build decisions materially affect time-to-market.
- Regulatory mapping and risk dashboards keyed to region-specific code changes, transmission expansion plans, and public-sector procurement windows.
- Cybersecurity and resilience requirements, including recommended control sets and third-party validation steps for mission-critical EMS deployments.
Practical guidance for 2026 boardroom decisions
- Prioritize interoperability and upgradeability: Choose EMS architectures that separate control determinism from cloud orchestration and provide open APIs to minimize lock-in and future integration costs.
- Embed compliance in procurement: Update RFP templates to require conformance evidence for the latest code revisions and DER-messaging standards—early compliance reduces retrofit costs.
- Shift from capex-only to lifecycle economics: Evaluate supplier offers on the basis of verified performance outcomes and revenue-sharing models tied to market participation and congestion-management revenues.
- Pilot with measurable KPIs: Run short, focused pilots with predefined KPIs (dispatch accuracy, net energy savings, resilience improvements) and staged rollouts to limit exposure and accelerate learning.
- Prepare for consolidation: Given the market concentration dynamics, prepare sourcing strategies that balance the resilience of incumbents with the innovation potential of specialized entrants.
Signals to watch in the next 12–18 months
- Major ISO/utility EMS upgrade approvals and awarded contracts—these will indicate which platforms are gaining super-regional traction.
- Standard and code implementation guidance tied to Article 130 and interoperability testing regimes; look for certified reference implementations.
- Corporate investment announcements and factory/service expansion programs—capital commitments by leading vendors signal supply-side readiness and competitive intent.
- Emergence of new commercial models—performance contracting, energy-as-a-service, and market-revenue share models will reframe project ROI calculations.
Concluding perspective — the strategic opportunity
The EMS market is transitioning from discrete control-system deployments to integrated platforms that unlock new value streams: market participation, resilience services, and operational optimization across distributed and central assets. For 2026 decision-makers, the opportunity lies in aligning procurement choices with long-horizon interoperability, regulatory-proof architectures, and partner ecosystems that can scale both geographically and functionally. PW Consulting’s full report contains the detailed segmentation, regional maps, and quantitative model outputs that underpin the strategic recommendations summarized here; those datasets are intentionally gated to ensure decision-makers access the validated inputs needed for transaction-grade planning.
For executives preparing budgets, negotiating supplier agreements, or evaluating M&A targets in 2026, this preview identifies where to focus due diligence and what trade-offs matter most. To access the complete dataset, vendor scorecards, and downloadable financial models that informed these findings, please consult the full Worldwide Power EMS Market report on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Worldwide Power Energy Management System (EMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide IT Market Tops USD 5.70 Trillion in 2025, Poised for 8.25% CAGR from 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Information Technology Market 2026: Strategic Signals for Decision‑Makers
As organizations plan capital allocation, talent strategies, and technology roadmaps for 2026, clarity on the macro trajectory of the global information technology market is indispensable. PW Consulting’s latest Worldwide Information Technology Market report synthesizes five years of historical dynamics (2020–2025) and delivers an analytically rigorous forecast across 2026–2032. With the global IT market returning to sustained momentum—recording a compound annual growth rate (CAGR) of 8.25% in our base forecast—this briefing outlines the strategic value of the report for executives preparing to act in the new market cycle.
Worldwide Information Technology Market
Why 2026 Is a Strategic Inflection Point
2025 closed with the global IT market at a multi‑trillion dollar scale, reflecting an investment wave driven largely by AI infrastructure, cloud migration, and a broad hardware refresh cycle. Independent market trackers have corroborated this momentum: IDC flagged a strong 2025 with double‑digit growth in worldwide IT spending, and Gartner projects semiconductor revenues to accelerate into 2026. For enterprise leaders, 2026 therefore represents a transition from exploratory investment in nascent capabilities to scaling and operationalizing new platforms. That transition raises three imperative questions:
Worldwide Information Technology Market
- Which technology investments should be scaled now versus piloted further?
- How should sourcing and vendor strategies adjust to both supply‑chain uncertainty and accelerating compute demand?
- What organizational and operating model changes will convert technology investments into differentiated business outcomes?
Our report is written to help decision‑makers answer these questions with pragmatic, data‑driven guidance while preserving the granular commercial intelligence needed for execution.
Worldwide Information Technology Market
What the Report Delivers — Actionable, Practical, and Executable
Beyond topline market sizing and growth trajectories, the report is intentionally operational. It is designed as a decision support toolkit for CIOs, CFOs, corporate strategists, and investors:
- Scenario-based forecasts that translate macro growth (annualized at 8.25% in our central scenario) into realistic investment envelopes and capacity planning windows for 2026–2028.
- Vendor positioning frameworks and vendor selection playbooks that marry technical fit, commercial terms, and geopolitical risk considerations—so procurement can move from RFIs to negotiated contracts with confidence.
- M&A and partnership scouting models that prioritize capability gaps and accretive targets across cloud, AI, and datacenter infrastructure domains.
- Implementation roadmaps and TCO/ROI calculators calibrated to current cost curves—enabling finance and IT to evaluate multi‑year programs with scenario sensitivities to commodity cycles and tariff exposures.
- Regulatory and supply‑chain risk matrices that map regional policy trends to sourcing decisions and contractual clauses, helping mitigate the operational impact of tariffs and export controls.
- Organizational blueprints for scaling AI and cloud native capabilities—covering governance, data platforms, skill buffers, and vendor co‑engineering models.
These deliverables are deliberately balanced: we provide the frameworks, assumptions, and directional metrics required to act, while preserving detailed subsegment data behind the report paywall to encourage direct engagement with our full dataset and client advisory services.
Market Structure and Concentration — Fragmented, Yet Opportunity‑Rich
The global IT market remains broadly diverse. Our concentration analysis highlights that the upper tier of vendors capture a modest share of overall revenue, indicating a competitive landscape where specialization and scale both create opportunities. For buyers, this structure means choices—large platform consolidation versus best‑of‑breed stack assembly—must be made based on technology fit and speed to value rather than on market share alone. For investors and acquirers, it underscores the potential for bolt‑on consolidation in specific capability niches.
Competitive Landscape: What the Leading Players Are Prioritizing
The report’s competitive analysis focuses on how large incumbents and global integrators are positioning across cloud, AI, hardware, and services. Key themes include platform extensibility, verticalization, and ecosystem orchestration:
- Microsoft continues to leverage an integrated cloud and productivity stack to embed enterprise workflows, while investing heavily in AI model operationalization and hybrid cloud tooling.
- Apple’s strategy remains centered on a proprietary hardware‑software ecosystem, with investment in silicon and endpoint security shaping enterprise adoption patterns.
- Alphabet/Google is scaling its cloud and AI offerings with differentiated data and ML tooling aimed at data‑centric workloads and advertising revenue synergies.
- AWS maintains its leadership in elastic infrastructure, expanding services to support complex generative AI and large‑scale migration projects.
- NVIDIA’s compute platforms are increasingly at the heart of AI infrastructure strategies, re‑rating the economics of large language model training and inference.
- IBM and Oracle emphasize enterprise continuity—hybrid cloud, mission‑critical databases, and industry‑specific solutions—targeting regulated sectors that demand predictable SLAs.
- Accenture, TCS, Infosys, SAP and other services firms are consolidating transformation offerings—combining consulting, systems integration, and managed services to capture ongoing operational spend.
Our analysis details how these players compete across go‑to‑market levers—partner ecosystems, channel incentives, developer mindshare, and industry partnerships—and what that means for potential buyers and partners in 2026.
Near‑Term Dynamics to Watch
PW Consulting’s research synthesizes external indicators—IDC’s 2025 spending surge, Gartner’s semiconductor outlook for 2026, and CES 2026 technological signals—into a set of watchpoints that should inform strategy conversations this year:
- AI Infrastructure and Compute Scarcity: The push to scale domain‑specific models is stretching datacenter and accelerator capacity, creating a premium on timely procurement and reserved capacity strategies.
- Semiconductor and Hardware Supply Uncertainty: Continued geopolitical friction and tariff considerations require dual sourcing, localized build strategies, and contractual protections to avoid program delays.
- Cloud and Edge Economics: Organizations are re‑optimizing cloud footprints, blending hyperscaler services with on‑prem and edge deployments to manage latency, cost, and data sovereignty.
- Service Provider Investment in Datacenter Infrastructure: Elevated spending by service providers on servers, storage, and networking is reshaping supplier roadmaps and opens strategic supplier negotiation windows.
How Executives Should Use This Report in 2026 Planning
Translate the macro narrative into concrete actions across three horizons:
- Horizon 1 — De‑risk and scale (0–12 months): Lock down critical capacity commitments for AI and cloud, prioritize vendor SLAs and redundancy, and apply our procurement playbook to secure favorable commercial terms.
- Horizon 2 — Optimize and integrate (12–24 months): Rebalance the technology stack for total cost of ownership using our TCO models, consolidate tooling where scale drives measurable savings, and begin migrating pilots into production with robust observability.
- Horizon 3 — Differentiate and capture value (24+ months): Invest in verticalized capabilities and data moats that competitors cannot easily replicate, and use our M&A playbook to acquire targeted capabilities that accelerate time‑to‑market.
Each horizon is supported in the full report by actionable templates, decision matrices, and project plans designed for boardrooms and program teams alike.
Methodology and Credibility
PW Consulting’s forecast combines bottom‑up vendor and segment modeling with top‑down macro checks. We cross‑validate capacity, pricing, and adoption assumptions against independent industry sources and leading market trackers. Where public forecasts diverge—such as differing short‑term semiconductor demand signals—we present alternative scenarios and quantify their implications for capital planning and supply‑chain exposure.
Importantly, while this summary highlights our strategic findings and frameworks, the detailed datasets, segment tables, and vendor revenue models are reserved for the full report and client deliverables—ensuring competitive confidentiality and enabling tailored advisory engagements.
Next Steps and How to Access the Full Intelligence
For organizations preparing budgets and strategic programs in 2026, PW Consulting’s Worldwide Information Technology Market report is a practical asset: it converts macro momentum into executable plans and reveals where timing, procurement, and organizational design decisions will most materially affect outcomes.
To explore the full datasets, segmented forecasts, and customized advisory services—including supplier scorecards, country risk heatmaps, and ROI tools—visit the PW Consulting report page. Our research team is also available for executive briefings and tailored scenario workshops to help your leadership translate these market signals into decisive action.
In a market growing at an annualized clip of 8.25% and reshaped by AI, cloud, and infrastructure renewal, the right strategic posture in 2026 will separate those who merely adapt from those who capture disproportionate value. PW Consulting’s report is designed to make that distinction actionable.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Solenoid Reversing Valve Market Set to Grow at a 5.24% CAGR
By pmarketresearch, 2026-07-15
Worldwide Solenoid Reversing Valve Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s newest market study, WorldWide Solenoid Reversing Valve Market (base year 2025; historical 2020–2025; forecast 2026–2032), is designed as a decision‑grade briefing for executives, product leaders, supply‑chain managers and investors preparing strategies for 2026 and beyond. The global market reached approximately USD 962.5 million in 2025. Under the central scenario contained in our report, the market is projected to expand at a 5.24% compound annual growth rate (CAGR) over 2026–2032, surpassing USD 1.37 billion by 2032. This preview summarizes the strategic implications embedded in the full study and highlights where leadership teams must act during 2026 to capture durable value.
Worldwide Solenoid Reversing Valve Market
Why 2026 Is a Pivotal Inflection Point
-
Energy transition momentum: Accelerated adoption of heat pump technologies and tighter low‑GWP refrigerant mandates are changing valve design and qualification requirements. Reversing valves — especially four‑way designs used for seasonal switching — are now a critical system component, not a commodity accessory.
Worldwide Solenoid Reversing Valve Market -
Regulatory and safety thresholds: Product certification and pressure ratings are moving to the forefront of procurement decisions. Compliance with global recognition standards (UL and equivalents) and compatibility with higher maximum operating pressures for common HFC refrigerants are table stakes for access to mainstream HVAC and heat pump programs.
Worldwide Solenoid Reversing Valve Market -
Supply‑side volatility: Raw material cost swings are a material margin lever for valve producers. Our intelligence captured spot HRC (hot‑rolled coil) benchmarks across 2025–early‑2026 that demonstrate notable volatility, creating immediate procurement and hedging priorities for manufacturers and OEMs.
-
Concentration and consolidation pressure: The market exhibits high concentration among the top suppliers, shaping bargaining power, M&A incentives and partnership strategies in the near term.
What the Report Delivers — Practical, Transaction‑Ready Intelligence
PW Consulting’s report is structured around pragmatic use cases for commercial teams and C‑suite leaders. It is not an academic compilation; it is an implementation playbook. Core deliverables include:
-
Validated market sizing and a transparent forecasting model for 2026–2032 (scenario engines included) so you can stress‑test CAPEX and production plans against downside and upside cases.
-
Technology and product archetypes mapped to buyer needs (e.g., valve actuation methods, sealing materials and refrigerant compatibility) with engineering implications for NPI roadmaps.
-
Cost and margin benchmarking — Bill‑of‑material and conversion cost templates that enable quick margin sensitivity analyses under alternative steel and component price regimes.
-
Competitive landscaping with capability matrices and strategic positioning for the leading suppliers, plus an annotated timeline of recent product launches and go‑to‑market moves.
-
Supply‑chain vulnerability map and mitigation strategies: dual‑sourcing, contract hedges, and nearshoring implications for 2026 tactical plans.
-
M&A and partnership playbooks: prioritization criteria, integration checklists and value capture mechanisms for bolt‑on acquisitions or JV structures.
-
Commercial templates — pricing ladders, OEM qualification checklists and aftermarket service propositions designed to lift ASPs and extend lifetime value.
Key, Data‑Driven Takeaways for Corporate Strategy
-
Product portfolio focus: The ramp of high‑efficiency heat pumps increases commercial tailwinds for robust four‑way valve platforms that are refrigerant‑agnostic and can meet higher pressure requirements. Prioritize R&D investment where materials compatibility and cycle reliability intersect with regulatory conformity.
-
Cost management is non‑negotiable: Given recent volatility in steel markets and other input streams, manufacturers should deploy margin protection strategies now — negotiated long‑term purchase agreements, inventory optimization and selective vertical integration for high‑impact components.
-
Certification as a commercial lever: Achieving and advertising recognized approvals (e.g., UL recognition and validated max operating pressures) reduces friction in OEM qualification processes and expedites access to tier‑1 HVAC programs.
-
Aftermarket and services are underleveraged: Service contracts and reliability guarantees can differentiate offerings in a market with significant concentration among incumbents — build predictive maintenance and warranty models into commercial proposals.
-
Scenario planning for supply disruptions: The report’s forecast envelopes include upside and downside pathways that reflect potential raw material shocks and trade disruptions; procurement and production planners must operationalize trigger points for capacity and inventory adjustments.
Competitive Landscape — Profiles and Strategic Implications
The market is concentrated among a handful of strategic players; the combined market share of the top three and top five vendors underscores strong incumbency effects. PW Consulting’s CR metrics show a high three‑firm concentration and even greater dominance within a five‑firm cohort, implying limited room for low‑capital entrants to scale without partnership or niche specialization.
-
Sanhua Holding Group (Hangzhou, China) — A leading global supplier of four‑way reversing valves for HVAC and heat pumps, Sanhua’s SHF family and newly released stainless steel SHF‑G series position it strongly in programs prioritizing corrosion resistance and compatibility with both synthetic and natural refrigerants. Recent product launches and trade show activity in late‑2025/early‑2026 demonstrate an aggressive product cycle cadence and marketing push into intelligent controls.
-
Danfoss (Nordborg, Denmark) — A broad refrigeration and air‑conditioning component supplier whose solenoid portfolio and reversing valve solutions are deeply integrated into OEM platforms. Its global OEM relationships make it an essential partner for firms seeking scale in integrated systems.
-
Parker Hannifin & Bosch Rexroth — Both bring depth in hydraulic and pneumatic directional control valves and supply chains oriented to heavy industrial and mobile machinery. Their strengths lie in robustness and customization for non‑HVAC industrial applications.
-
Robertshaw & Wilspec — Specialized players focused on heat pump valve mechanisms and geothermal solutions respectively; they are differentiated by application know‑how and installation channel intimacy.
-
DunAn, SMC, ASCO (Emerson), Shandong Yikaide — These vendors reflect a mix of large OEM breadth, pneumatics expertise and regional manufacturing scale. Each occupies a specific niche in the ecosystem from automated pneumatic systems to price‑competitive valve bodies.
Recent developments — notably Sanhua’s SHF‑G stainless steel release and its RACC exhibition participation — illustrate how incumbents are accelerating product innovation and market visibility to capture wave demand from heat pump electrification programs.
Actionable Priorities for 2026 (Short‑Term) and 2026–2032 (Medium‑Term)
-
Immediate (0–12 months): Lock down supply of critical metals through contracts or localized sourcing, accelerate UL and equivalent certifications for core valve families, and pilot co‑development agreements with tier‑1 OEMs to secure early‑design wins in 2026 model years.
-
Near term (12–36 months): Invest in material and seal technologies that reduce lifetime leakage and broaden refrigerant compatibility; launch a services offering that monetizes installation validation and predictive maintenance; evaluate M&A targets to close capability gaps quickly.
-
Medium term (36–72 months): Build modular valve platforms that can be parametrically tuned for global regulatory envelopes, and pursue strategic partnerships that embed intelligent actuation and diagnostics into system architectures.
How to Use This Preview
This communication is intended as a strategic preview that demonstrates the depth and actionable orientation of PW Consulting’s full report. We intentionally withhold detailed regional and application segmentation tables and the full financial model in this release to preserve the integrity of our premium data package and encourage direct engagement. The complete study includes granular segmentation, downloadable modeling templates, supplier scorecards and executive‑ready slide material designed to accelerate your 2026 planning cycle.
Next Steps — For Executives Ready to Move
-
Procurement and operations leaders: request the model to run your own raw‑material sensitivity scenarios against the five forecast paths enclosed in the full report.
-
Product and R&D executives: engage with our product archetype mapping to accelerate specification updates required for low‑GWP refrigerant compatibility and higher operating pressures.
-
Strategy and corporate development teams: use our M&A playbook and vendor scorecards to prioritize targets and structure earn‑outs that preserve engineering know‑how during integration.
PW Consulting’s WorldWide Solenoid Reversing Valve Market report is a tactical resource for leaders who must convert 2026 market dynamics into executable plans. For immediate access to the full dataset, scenario models and supplier scorecards referenced above, please visit the full report page on PW Consulting’s website or contact our industry practice lead for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Silver Coated FEP Film Market to Surge from USD 144.13 Million in 2025 to USD 228.73 Million by 2032 at a 6.82% CAGR
By pmarketresearch, 2026-07-15
Worldwide Silver Coated FEP Film Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Silver Coated FEP Film Market is released with a clear purpose: to arm executive teams, procurement leaders, and product strategists with the macro-level intelligence and scenario-driven guidance they need to make high‑confidence decisions in 2026. Our analysis spans a six‑year historical baseline (2020–2025) and delivers a seven‑year forecast (2026–2032), using USD‑denominated revenue in Million as the reporting unit. The market has shown steady expansion through 2025 and, on the trajectory we model, is set to continue growing at a mid‑single digit pace (CAGR 6.82%) over the forecast period.
Worldwide Silver Coated FEP Film Market
Big Picture: Why silver coated FEP matters to aerospace, defense and cryogenic stakeholders in 2026
-
Material performance now underpins a broader set of strategic choices — from constellation economics and satellite thermal budgets to cryogenic system reliability and space-qualified optical assemblies. The silver coated FEP film market is small in absolute terms relative to mainstream polymers, but it sits at a critical intersection of high value engineering, constrained supply chains, and sensitivity to precious‑metal price dynamics.
Worldwide Silver Coated FEP Film Market -
Market scale has expanded meaningfully since 2020; PW Consulting’s topline sizing shows growth from the early‑decade base through 2025 and continued market scale by 2032 consistent with the stated CAGR. That trajectory matters: incremental volume demand will increasingly reward scale players and vertically integrated propositions, while creating opportunities for niche specialists that can prove value in thermal, optical and cryogenic performance.
Worldwide Silver Coated FEP Film Market -
For decision-makers in 2026, the primary strategic questions are no longer whether the market will exist, but how to lock in secure access to quality film, manage raw‑material cost exposure, and structure product roadmaps that capture improving ASPs while protecting margins.
What the PW Consulting report delivers — a practical playbook, not a parade of charts
This study is structured to be decision‑centric. Beyond detailed market sizing and trend analysis, the report contains tools and actionable outputs designed to be used in board decks, procurement negotiations, and R&D prioritization:
-
Executive synthesis and near‑term implications for 2026 planning cycles.
-
Top‑down market sizing and demand scenarios calibrated to aerospace program pipelines, defense procurement windows, and commercial satellite deployments.
-
Supplier mapping and capability matrices that highlight manufacturing technologies (e.g., ITO integration, dielectric overcoats, tape formats), lead times, and qualification footprints — presented in a way you can use for supplier selection and contingency planning.
-
Cost models with sensitivity analyses focused on silver price volatility, production waste, and coating yield; scenario outputs demonstrate margin pressure points and breakeven thresholds for pricing strategies.
-
Negotiation playbooks and contract templates for multi-year offtake, consignment inventory, and risk‑sharing clauses that protect both buyers and strategic suppliers.
-
Technology and substitution assessments, including the tradeoffs of ITO, dielectric overlays, and reclamation/recycling programs for used or scrap film.
-
Regulatory, sustainability and end‑of‑life pathways relevant to aerospace integrators and government contractors.
-
Scenario roadmaps — rapid shock (raw material price spike), steady growth, and accelerated program adoption — with decision gates and recommended tactical responses at each stage.
Competitive landscape: concentrated supply, differentiated technology
The supplier base is characterized by a mix of established specialty film manufacturers and focused aerospace suppliers. Our competitive review spotlights companies that have demonstrable heritage in producing silver coated FEP and related second surface mirror products, and it evaluates their capabilities along technical, commercial, and qualification axes.
-
Dunmore Aerospace — a decades‑long specialist recognized for full‑range silver coated FEP offerings (including variants with ITO and dielectric SiO2 overlays). The firm’s experience in aerospace thermal control and MLI applications places it among the primary technology leaders in the sector.
-
SQUID3 Space — an agile manufacturer oriented toward tape formats and flexible optical reflectors used in spacecraft thermal and optical systems; its focus on defense and space applications supports rapid qualification cycles for select end‑use markets.
-
Sheldahl — historically a known producer of single‑side silver coated FEP products, now integrated into broader operations; its legacy products remain relevant in certain MLI and thermal mirror contexts.
Two structural facts frame competition: first, market concentration limits the number of truly qualified suppliers; second, technology differentiation (coating process, adhesion, optical finish, cryo‑stability) creates persistent barriers to entry. PW Consulting’s concentration metrics indicate a market where the top three and top five suppliers together account for a material share of supply — a dynamic that both stabilizes quality availability and concentrates pricing power. These concentration dynamics should shape any supplier strategy you adopt in 2026.
Raw material dynamics: silver price volatility and the procurement imperative
Raw material exposure is the single most actionable risk identified in our analysis. External research and market reporting have shown silver price volatility in early 2026, with prominent forecasts and spot reports pointing to elevated levels relative to recent history. Those movements directly translate into cost pressure for silver coated films, given silver’s role in both optical reflectivity and electrical conductivity in some product variants.
-
Practical implications: procurement teams must treat silver as a strategic commodity. Short‑term fixes (e.g., passing costs through) are viable in some contracts, but longer‑term competitiveness will come from hedging, long‑dated supply agreements with indexation clauses, and investment in reclamation/recycling.
-
Technology levers: alternative coating architectures (ITO layers, dielectric stacks) or reduced silver loading can mitigate exposure but require qualification and often change thermal and optical performance. Our report provides systematic trade‑off matrices that quantify the impacts.
Strategic playbook for 2026 — prioritized actions
We recommend a three‑tiered approach aligned to timeframe and organizational complexity:
-
Immediate (0–9 months): implement hedging and indexation clauses for silver exposure; establish multi‑source pilots with at least one alternative qualified supplier; secure strategic inventory for critical programs to cover lead‑time shocks.
-
Near term (9–24 months): invest in qualification programs for lower‑silver architectures where program risk permits; execute supplier consolidation only where it yields demonstrable cost or qualification efficiencies; formalize recycling pathways for scrap and end‑of‑life return streams.
-
Medium term (24–48 months): consider vertical integration or equity stakes in key coating capability suppliers if volume growth materializes; prioritize R&D to reduce silver loading and improve process yields; embed market scenario triggers into contract renewal and product launch calendars.
How executives should use this report in 2026
This study is designed to be used as the foundation for: (a) procurement negotiation strategy documents; (b) capex planning for coating or lamination capacity; (c) supplier due diligence during M&A or partnerships; and (d) technology roadmaps for thermal and optical product teams. The report’s sensitivity models allow finance and commercial teams to stress‑test margin scenarios under different silver‑price paths and program adoption curves.
Importantly, PW Consulting has packaged our raw models so decision‑makers can run bespoke scenarios. That means you can adapt the topline market growth paths to your own program timelines and immediately see the impact on procurement spend and gross margins.
Trailer: what we are not publishing here — and why you need the full report
In this announcement we intentionally present a high‑level synthesis and curated insights designed to inform 2026 strategy. We do not publish the proprietary granular segmentation tables, regional or application‑level percentage breakdowns, supplier scoring matrices, or the full financial model in this release. Those items are core to our paid deliverable because they are the same elements that enable direct operational decisions — supplier selection, contract structuring, and capex justification.
If your 2026 decisions require executable data — for example, supplier‑level lead‑time distributions, granular thickness‑by‑application demand curves, or downloadable cost‑model templates calibrated to silver price inputs — PW Consulting’s full report and accompanying datasets are available for clients. The full deliverable includes a customizable Excel model, supplier due‑diligence worksheets, and a playbook for negotiating long‑term offtake and recycling agreements.
Final note — an invitation to act
For organizations that depend on predictable thermal and optical performance, the decisions you make in 2026 about supplier access, material strategy, and technology investment will have outsized consequences over the next five to seven years. PW Consulting’s Worldwide Silver Coated FEP Film Market report is structured to translate market intelligence into concrete actions: hedge where exposure is uncontrollable, qualify alternatives where feasible, and align procurement and R&D roadmaps to program milestones.
To learn how the report’s models apply to your portfolio — and to obtain the proprietary segmentation and supplier evaluation data omitted from this release — contact PW Consulting to access the full study and our scenario playbooks.
For detailed analysis of this topic, please visit the official page: Worldwide Silver Coated FEP Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Ferrite Cable Cores Market Valued at USD 750 Million in 2025, Set for Continued Expansion Through 2032
By pmarketresearch, 2026-07-15
Worldwide Ferrite Cable Cores Market — Strategic Briefing for 2026: Navigating Demand, Supply Risk, and Competitive Positioning
Executive summary
As the adoption of higher-speed data interfaces, electrified mobility, and dense power electronics accelerates, the ferrite cable cores market is entering a phase of steady expansion. Our latest PW Consulting study (base year 2025; historical window 2020–2025; forecast 2026–2032) finds the global market at approximately USD 750.0 Million in 2025, tracking a compound annual growth rate (CAGR) of 5.23% through the 2026–2032 horizon. By 2032, the market is projected to exceed the USD 1.0 Billion threshold under our baseline scenario.
Worldwide Ferrite Cable Cores Market
This briefing is written to support executive teams responsible for procurement, product engineering, and corporate strategy as they build 2026 action plans. It highlights the strategic levers that matter most — supply resilience, product differentiation for next‑generation interfaces, and competitive posture — while intentionally withholding granular segment-level figures to encourage direct engagement with the full report for transaction-ready intelligence.
Worldwide Ferrite Cable Cores Market
Market trajectory and what it means for 2026 decisions
The market recovery observed in the 2020–2025 period reflects a combination of cyclical recovery post-2020, rapid upgrades in consumer and enterprise connectivity, and the early electrification wave in automotive applications. The mid-single-digit CAGR we model suggests a market where incremental volume growth is coupled with rising technical demands: wider bandwidth EMI suppression, automotive-grade qualifications, and material-grade differentiation (e.g., NiZn vs. MnZn ferrites).
Worldwide Ferrite Cable Cores Market
- Strategic implication: Suppliers and OEMs should treat 2026 as a year to shift from tactical sourcing to capability-building — qualifying alternative materials, locking multi-year supply agreements, and embedding ferrites earlier in product architecture discussions.
- Risk implication: Moderate growth masks asymmetric risk — pockets of acute supply pressure (certain ferrite chemistries) and rapid price moves that can erode margins if left unhedged.
Supply chain dynamics: raw materials, tariffs, and lead times
Our sector analysis confirms concentration in upstream raw materials: iron oxide, manganese, and zinc feedstocks remain heavily sourced from a small number of exporting countries, with China accounting for well over four-fifths of global supply. This structural exposure has real consequences for 2026 procurement strategy:
- Tariff and trade policy: Recent trade measures have materially increased the landed cost of some ferrite components into key markets. Buyers should model landed-cost scenarios with sensitivity to tariff escalation and local content thresholds.
- Lead-time pressure: Specific chemistries have experienced extended lead times amid demand surges for EV and data center cabling. Our fieldwork documents supply-to-order cycles stretching multiple months for NiZn grades — a factor that should be integrated into inventory and NPI timelines.
- Price volatility: Benchmarked market data show notable price inflation in snap-on core products during the latest annual cycle. Pricing strategies must therefore include indexed clauses, multi-year purchase commitments, and vendor diversification plans.
Regulatory and standards headwinds
Regulatory compliance is non-negotiable. The EU RoHS framework and analogous global restrictions continue to constrain allowable concentrations of certain heavy elements, shaping material selection and qualification timelines. At the same time, accelerated performance requirements for 5G, USB4, PCIe Gen5 and automotive Ethernet drive tighter electrical and mechanical tolerances.
Strategic implication: Product teams must reconcile dual imperatives — material compliance and high-frequency performance — by investing in advanced material characterization and closer, co‑development relationships with ferrite manufacturers.
Competitive landscape: how major players are positioning
The market exhibits moderate concentration (CR3 ~38.45%; CR5 ~52.12%), indicating a mix of global leaders and regional specialists. Key incumbent capabilities include broad product portfolios, materials science IP, and certifications for automotive and industrial use. Our competitive assessment — synthesized from supplier disclosures, product roadmaps, and recent corporate developments — yields the following directional insights:
- TDK Corporation (Tokyo): Continues to push high‑permeability snap-on cores optimized for 5G and automotive Ethernet. Recent product introductions underscore their strategy of combining materials innovation with system-level qualification for next-generation cable standards.
- Murata Manufacturing (Nagaokakyo): Focuses on miniaturized ferrite beads and compact cores for high-speed data links. Their trade-show showcases and compact product lines favor OEMs prioritizing space-constrained applications.
- Laird Technologies (DuPont) (Chestnut Ridge, NY): Advancing automotive-grade portfolio through AEC-Q200 qualifications — a clear signal to EV supply chains and charging infrastructure OEMs that they intend to be a preferred supplier for automotive applications.
- Fair‑Rite Products (Wallkill, NY): Leverages a deep material-engineering catalog; recent catalog updates target USB4 and PCIe Gen5, aligning with the high-speed interface market’s needs.
- Ferroxcube (Yageo), Vacuumschmelze, Mitsubishi Materials, Samsung Electro‑Mechanics, Sunlord Electronics, and Epcos (TDK subsidiary): Each pursues a blend of regional strength and targeted technical differentiation — from toroidal power line filters to cost-optimized snap‑on assemblies for consumer cables.
Recent vendor activity — new high‑frequency products, automotive certifications, and catalog refreshes — reveals how incumbents are defending technical leadership while chasing adjacencies. For entrants and smaller suppliers, this dynamic increases the importance of niche specialization (e.g., custom formulations, rapid prototyping services, or local assembly) to avoid commoditization.
Where the opportunities are — and what we intentionally do not disclose here
Our full analysis identifies high-conviction opportunities across product development, procurement, and M&A. Examples include:
- Engineering partnerships to co-develop ferrite chemistries tuned for automotive Ethernet and high-speed data cables.
- Backward integration and local-sourcing strategies to mitigate tariffs and raw material concentration risk.
- Premiumization of cable assemblies by embedding certified, performance-grade cores as a differentiation point for OEMs targeting enterprise and automotive channels.
- Targeted acquisitions of regional specialists to accelerate market entry and secure faster time-to-market for automotive qualifications.
Following the “trailer” principle, this release highlights the strategic arcs above but withholds granular segment and regional datapoints — including the precise split of demand by region, core type, and application — to protect the report’s transaction-ready insights. These detailed slices, supplier scorecards, and scenario-based valuation models are accessible in the full PW Consulting report.
What the PW Consulting report provides — practical, implementation-ready modules
For teams preparing 2026 budgets and roadmaps, our report is structured to be operational from day one. It includes:
- Verified market sizing and demand model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity to pricing, tariff, and adoption curves.
- Supply chain heatmaps and a supplier risk index that quantifies raw-material dependency, geopolitical exposure, and lead-time variability.
- Material and performance matrixes that map ferrite chemistries to application-level electrical requirements and compliance constraints.
- Competitive benchmarking and vendor scorecards covering technology, certifications, capacity, and go-to-market reach.
- Procurement playbook: contract clauses, hedging constructs, multi-sourcing frameworks, and near-shore vs. on-shore decision criteria.
- M&A and partnership scouting lists with valuation frameworks and integration checklists tailored to strategic buyers.
- Roadmaps for product development: qualification timelines (incl. automotive standards), testing protocols, and cost-vs-performance trade-off calculators.
How to use this intelligence to shape your 2026 plan — a practical checklist
We recommend executives apply the following five-step sequence in Q1–Q2 2026:
- Quantify exposure: Run our supplier risk index against your bill of materials to identify single-source ferrite dependencies and tariff-sensitive nodes.
- Prioritize product roadmaps: For each SKU, score the value of upgrading to automotive/5G-capable ferrite cores vs. the incremental cost and qualification time.
- Lock strategic suppliers: Negotiate conditional multi-year contracts with capacity reservation and price-adjustment triggers tied to raw material indices.
- Pursue targeted partnerships: Co-design ferrite solutions with tier-1 suppliers for critical applications rather than relying solely on off-the-shelf parts.
- Prepare a contingency kit: Build inventory buffers for chemistries with the longest lead times and qualify second-source materials to avoid NPI delays.
Closing perspective and next steps
The ferrite cable cores market in 2026 is less about explosive volume growth and more about technical and supply-chain differentiation. Companies that invest now in materials know-how, procurement sophistication, and vendor co-development will capture disproportionate value as interfaces converge on higher frequencies and automotive electrification deepens.
PW Consulting’s full Worldwide Ferrite Cable Cores Market report delivers the granular segmentation, supplier scorecards, and scenario models that operational teams need to convert strategic intent into executable programs. To review the complete dataset, regional and application splits, and proprietary vendor rankings, access the full report via the PW Consulting portal.
For bespoke briefings, supplier workshops, or a tailored procurement stress‑test modeled on your BOM, contact the PW Consulting Industry Strategy team to schedule a 1:1 consultation.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ice Silk Sleeves Market Poised for 6.28% CAGR Through 2032, New Insight Report Says
By pmarketresearch, 2026-07-15
Worldwide Ice Silk Sleeves Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market intelligence on the Worldwide Ice Silk Sleeves market offers a focused, decision-oriented briefing crafted for executives, product leaders, and B2B buyers planning for 2026. This preview synthesizes headline dynamics, competitive posture, and tactical imperatives drawn from our 2025 base-year analysis and the 2026–2032 forecast run. It demonstrates the type of actionable insight contained in the full study while preserving the detailed segment-level models that subscribers rely on when executing market entry, pricing, or sourcing strategies.
Worldwide Ice Silk Sleeves Market
Headline Market Trajectory
After a solid recovery and expansion through the early 2020s, the global ice silk sleeves market reached a material scale in the base year 2025. Between 2020 and 2025 the market expanded from a clear niche into a mainstream accessory for outdoor sports, commuting, and light professional use, with overall revenues rising markedly. Our forecast anticipates continued steady expansion: the market is projected to grow through the forecast window and to attain a substantially larger global footprint by the end of the 2032 horizon, reflecting a compound annual growth rate (CAGR) of approximately 6.28% over 2026–2032.
Worldwide Ice Silk Sleeves Market
What this means for 2026 is twofold: (1) demand momentum remains intact and is broadening across adjacent use cases, and (2) competitive differentiation — not just pricing — will determine which suppliers capture the higher-margin pockets that are emerging as product complexity and consumer expectations increase.
Worldwide Ice Silk Sleeves Market
Why This Report Matters for 2026 Strategy
- Fast-track prioritization: We translate headline growth and SKU-level innovation trends into a short list of high-impact plays that procurement, product, and channel teams can execute within 6–12 months.
- Operational levers: The analysis isolates supplier cost drivers, manufacturing bottlenecks, and packaging/fulfilment sensitivities that materially affect landed cost and time-to-market.
- Commercial risk management: The study identifies three principal downside scenarios (raw-material volatility, regulatory tightening on performance claims, and platform-driven margin compression) and prescribes mitigation steps tailored to different business models.
Supply Chain and Input Dynamics — Practical Implications
Ice silk sleeves are functionally simple but technically nuanced. Most commercial products are constructed from microfiber blends that trade off cost, hand-feel, UV performance, and elasticity. In 2026, buyers must weigh fabric selection (and the additives used for UV blocking) more deliberately because supplier choices now drive measurable differences in perceived cooling, durability, and printing compatibility.
Key operational takeaways:
- Source diversification: Contracts with multiple qualified fabric mills reduce exposure to single‑supplier lead‑time spikes and permit tactical product segmentation (economy vs. premium SKUs).
- Quality gating: Implement mid-line sensory and UPF verification checks rather than rely solely on supplier certificates; this reduces returns and reputational risk as performance claims face growing scrutiny.
- Manufacturing flexibility: Suppliers offering on-demand customization (heat-transfer, sublimation, seamless construction) command premium placement with global sporting goods brands.
Demand Patterns and Channel Dynamics
Consumer adoption is driven by two complementary perceptions: functional sun protection and a cooling/comfort effect for warm-weather activity. In practice, these claims are anchored to standard UPF product positioning and to the garment’s sensory attributes. From a go-to-market perspective, the segments that grew fastest are closely linked to lifestyle use-cases (daily commuting, cycling, and casual sports) where an inexpensive accessory can be cross‑sold with apparel or equipment.
Channel dynamics in 2026 remain heterogeneous. Direct-to-consumer e-commerce continues to scale and is the fastest route for differentiated, branded SKUs; wholesale and OEM pathways are preferred by volume buyers and private-label accelerators. Retail partnerships still matter for specialty sporting segments where tactile evaluation and brand trust influence purchase.
Product and Innovation Priorities
- Design for dual use: Successful SKUs in 2025–26 blend sun protection with wearability — considerations such as seamless cuffs, heat management, and compression for sport use are recurring winning attributes.
- Theming and licensing: Seasonal and event-themed designs (sports tournaments, cycling events) are being used to unlock short-term uplift without heavy R&D investments.
- Customization at scale: Sports teams and corporate gifting continue to be predictable volume channels when printing options are supported at low minimums.
Competitive Landscape — Practical Read of Key Players
The market remains fragmented by design, with a mix of branded specialists, online-first merchants, and established apparel OEMs competing simultaneously for shelf space and contract wins. Our competitive scorecard in the full report evaluates financial scale, SKU breadth, channel footprint, and manufacturing depth. A snapshot of typical strategic positions follows:
- Achiou (China): Positioned as a cost-efficient exporter with mature e‑commerce distribution. Strengths include high catalogue breadth and competitive compression/sports lines for mainstream channels.
- Hikesity (online brand): Service-centric digital retailer; excels at lifestyle positioning and rapid design refresh for everyday and outdoor use-cases.
- Body Helix (USA): A U.S.-based specialist concentrating on active lifestyle sports applications; proximity to key customers and brand alignment with niche sports communities are competitive advantages.
- Arabella Clothing: Sportswear manufacturer with notable capability in custom printing — attractive to teams and promotional buyers seeking small-batch personalization.
- Shenzhen Eigday (Day Wolf), Yiwu An Jun (ALKINGLINE), Guangzhou Chenquan: Representative of Chinese OEM/ODM base — strong in cost-competitive volume manufacturing, rapid SKU development, and OEM partnerships.
Recent product moves observed in the supply base — such as the 2025 introduction of golf- and driving-specific sleeves and the 2026 model refreshes emphasizing seamless construction and extended UV protection — demonstrate a tilt toward use-case refinement rather than purely price-led competition. This is an important inflection: product feature differentiation is gradually replacing basic cost as the primary battleground.
Recommended Strategic Plays for 2026
- Prioritize portfolio segmentation: Maintain an economy line for distribution partners while investing in a premium lane with better fabrics, advanced prints, and enhanced fit to protect margin.
- Embed testing and certification into product launch cycles: Shorten commercial lead times by standardizing UPF and sensory checks as part of vendor onboarding.
- Leverage small-batch customization: Capture higher ASPs by offering team and corporate branding options with low minimums via regional fulfillment partners.
- Negotiate bundled sourcing: Combine sleeve orders with complementary apparel or accessories to secure better terms and reduce per-SKU logistics costs.
- Monitor platform economics: Protect margins against marketplace-driven price erosion through brand-building and exclusive product features.
Regulatory and Reputational Watch-Points
Performance claims (e.g., UPF ratings, “cooling” benefits) are increasingly scrutinized by platforms and regulators. Firms should preemptively document testing protocols and avoid unverified absolute claims. In parallel, sustainability expectations are rising — even for low-ticket accessories — and early movers that can demonstrate lower lifecycle impacts (e.g., recycled inputs, low-waste dyeing) are finding preferential listing and procurement treatment among larger retail partners.
What’s Inside the Full PW Consulting Report
The complete study builds on this strategic preview with the following practical components designed for execution teams:
- Detailed historical sizing and a transparent, line-item forecast model (2026–2032) with scenario toggles for input cost, demand elasticity, and channel mix.
- SKU-level margin simulations and landed-cost calculators that allow procurement teams to model vendor and freight choices.
- Supplier benchmarking and an OEM capability matrix covering manufacturing assets, lead times, and customization services.
- Commercial playbooks for DTC, marketplaces, and wholesale channels, including promotion calendars and suggested price architecture.
- Profiles and strategic assessments of the leading brands and manufacturers in the market, alongside a curated list of potential M&A/partnership targets for mid‑market consolidators.
Methodology and Credibility
Our analysis synthesizes primary interviews across the value chain, SKU audits on leading platforms, and a bottom-up supply-side model validated against observable shipment patterns and manufacturer disclosures. The 2025 base-year is built from an aggregated revenue approach and reconciled with global trade flows and retailer assortment data to ensure consistency with market realities.
Next Steps — How to Use This Preview
Use this briefing as a decision trigger: if your 2026 priorities include product line optimization, supplier re‑negotiation, or a channel expansion play, the full report will provide the granular inputs and scenario tools necessary to underwrite those decisions with confidence. For buy-side teams, the included vendor matrix accelerates supplier shortlisting; for product teams, the SKU-level guidance identifies the most efficient feature investments to maximize ROI.
To access the complete data tables, the vendor scorecard, and the forecast workbook that underpin these recommendations, please visit the PW Consulting research page for the Worldwide Ice Silk Sleeves Market report. The full study contains the segment detail, regional breakdowns, and price‑sensitivity analyses required for transaction-level planning.
— PW Consulting, Senior Strategy and Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Worldwide Ice Silk Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com