

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide IT Market Tops USD 5.70 Trillion in 2025, Poised for 8.25% CAGR from 2026–2032

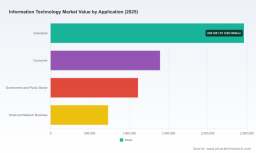
Worldwide Information Technology Market 2026: Strategic Signals for Decision‑Makers
As organizations plan capital allocation, talent strategies, and technology roadmaps for 2026, clarity on the macro trajectory of the global information technology market is indispensable. PW Consulting’s latest Worldwide Information Technology Market report synthesizes five years of historical dynamics (2020–2025) and delivers an analytically rigorous forecast across 2026–2032. With the global IT market returning to sustained momentum—recording a compound annual growth rate (CAGR) of 8.25% in our base forecast—this briefing outlines the strategic value of the report for executives preparing to act in the new market cycle.
Worldwide Information Technology Market
Why 2026 Is a Strategic Inflection Point
2025 closed with the global IT market at a multi‑trillion dollar scale, reflecting an investment wave driven largely by AI infrastructure, cloud migration, and a broad hardware refresh cycle. Independent market trackers have corroborated this momentum: IDC flagged a strong 2025 with double‑digit growth in worldwide IT spending, and Gartner projects semiconductor revenues to accelerate into 2026. For enterprise leaders, 2026 therefore represents a transition from exploratory investment in nascent capabilities to scaling and operationalizing new platforms. That transition raises three imperative questions:
Worldwide Information Technology Market
- Which technology investments should be scaled now versus piloted further?
- How should sourcing and vendor strategies adjust to both supply‑chain uncertainty and accelerating compute demand?
- What organizational and operating model changes will convert technology investments into differentiated business outcomes?
Our report is written to help decision‑makers answer these questions with pragmatic, data‑driven guidance while preserving the granular commercial intelligence needed for execution.
Worldwide Information Technology Market
What the Report Delivers — Actionable, Practical, and Executable
Beyond topline market sizing and growth trajectories, the report is intentionally operational. It is designed as a decision support toolkit for CIOs, CFOs, corporate strategists, and investors:
- Scenario-based forecasts that translate macro growth (annualized at 8.25% in our central scenario) into realistic investment envelopes and capacity planning windows for 2026–2028.
- Vendor positioning frameworks and vendor selection playbooks that marry technical fit, commercial terms, and geopolitical risk considerations—so procurement can move from RFIs to negotiated contracts with confidence.
- M&A and partnership scouting models that prioritize capability gaps and accretive targets across cloud, AI, and datacenter infrastructure domains.
- Implementation roadmaps and TCO/ROI calculators calibrated to current cost curves—enabling finance and IT to evaluate multi‑year programs with scenario sensitivities to commodity cycles and tariff exposures.
- Regulatory and supply‑chain risk matrices that map regional policy trends to sourcing decisions and contractual clauses, helping mitigate the operational impact of tariffs and export controls.
- Organizational blueprints for scaling AI and cloud native capabilities—covering governance, data platforms, skill buffers, and vendor co‑engineering models.
These deliverables are deliberately balanced: we provide the frameworks, assumptions, and directional metrics required to act, while preserving detailed subsegment data behind the report paywall to encourage direct engagement with our full dataset and client advisory services.
Market Structure and Concentration — Fragmented, Yet Opportunity‑Rich
The global IT market remains broadly diverse. Our concentration analysis highlights that the upper tier of vendors capture a modest share of overall revenue, indicating a competitive landscape where specialization and scale both create opportunities. For buyers, this structure means choices—large platform consolidation versus best‑of‑breed stack assembly—must be made based on technology fit and speed to value rather than on market share alone. For investors and acquirers, it underscores the potential for bolt‑on consolidation in specific capability niches.
Competitive Landscape: What the Leading Players Are Prioritizing
The report’s competitive analysis focuses on how large incumbents and global integrators are positioning across cloud, AI, hardware, and services. Key themes include platform extensibility, verticalization, and ecosystem orchestration:
- Microsoft continues to leverage an integrated cloud and productivity stack to embed enterprise workflows, while investing heavily in AI model operationalization and hybrid cloud tooling.
- Apple’s strategy remains centered on a proprietary hardware‑software ecosystem, with investment in silicon and endpoint security shaping enterprise adoption patterns.
- Alphabet/Google is scaling its cloud and AI offerings with differentiated data and ML tooling aimed at data‑centric workloads and advertising revenue synergies.
- AWS maintains its leadership in elastic infrastructure, expanding services to support complex generative AI and large‑scale migration projects.
- NVIDIA’s compute platforms are increasingly at the heart of AI infrastructure strategies, re‑rating the economics of large language model training and inference.
- IBM and Oracle emphasize enterprise continuity—hybrid cloud, mission‑critical databases, and industry‑specific solutions—targeting regulated sectors that demand predictable SLAs.
- Accenture, TCS, Infosys, SAP and other services firms are consolidating transformation offerings—combining consulting, systems integration, and managed services to capture ongoing operational spend.
Our analysis details how these players compete across go‑to‑market levers—partner ecosystems, channel incentives, developer mindshare, and industry partnerships—and what that means for potential buyers and partners in 2026.
Near‑Term Dynamics to Watch
PW Consulting’s research synthesizes external indicators—IDC’s 2025 spending surge, Gartner’s semiconductor outlook for 2026, and CES 2026 technological signals—into a set of watchpoints that should inform strategy conversations this year:
- AI Infrastructure and Compute Scarcity: The push to scale domain‑specific models is stretching datacenter and accelerator capacity, creating a premium on timely procurement and reserved capacity strategies.
- Semiconductor and Hardware Supply Uncertainty: Continued geopolitical friction and tariff considerations require dual sourcing, localized build strategies, and contractual protections to avoid program delays.
- Cloud and Edge Economics: Organizations are re‑optimizing cloud footprints, blending hyperscaler services with on‑prem and edge deployments to manage latency, cost, and data sovereignty.
- Service Provider Investment in Datacenter Infrastructure: Elevated spending by service providers on servers, storage, and networking is reshaping supplier roadmaps and opens strategic supplier negotiation windows.
How Executives Should Use This Report in 2026 Planning
Translate the macro narrative into concrete actions across three horizons:
- Horizon 1 — De‑risk and scale (0–12 months): Lock down critical capacity commitments for AI and cloud, prioritize vendor SLAs and redundancy, and apply our procurement playbook to secure favorable commercial terms.
- Horizon 2 — Optimize and integrate (12–24 months): Rebalance the technology stack for total cost of ownership using our TCO models, consolidate tooling where scale drives measurable savings, and begin migrating pilots into production with robust observability.
- Horizon 3 — Differentiate and capture value (24+ months): Invest in verticalized capabilities and data moats that competitors cannot easily replicate, and use our M&A playbook to acquire targeted capabilities that accelerate time‑to‑market.
Each horizon is supported in the full report by actionable templates, decision matrices, and project plans designed for boardrooms and program teams alike.
Methodology and Credibility
PW Consulting’s forecast combines bottom‑up vendor and segment modeling with top‑down macro checks. We cross‑validate capacity, pricing, and adoption assumptions against independent industry sources and leading market trackers. Where public forecasts diverge—such as differing short‑term semiconductor demand signals—we present alternative scenarios and quantify their implications for capital planning and supply‑chain exposure.
Importantly, while this summary highlights our strategic findings and frameworks, the detailed datasets, segment tables, and vendor revenue models are reserved for the full report and client deliverables—ensuring competitive confidentiality and enabling tailored advisory engagements.
Next Steps and How to Access the Full Intelligence
For organizations preparing budgets and strategic programs in 2026, PW Consulting’s Worldwide Information Technology Market report is a practical asset: it converts macro momentum into executable plans and reveals where timing, procurement, and organizational design decisions will most materially affect outcomes.
To explore the full datasets, segmented forecasts, and customized advisory services—including supplier scorecards, country risk heatmaps, and ROI tools—visit the PW Consulting report page. Our research team is also available for executive briefings and tailored scenario workshops to help your leadership translate these market signals into decisive action.
In a market growing at an annualized clip of 8.25% and reshaped by AI, cloud, and infrastructure renewal, the right strategic posture in 2026 will separate those who merely adapt from those who capture disproportionate value. PW Consulting’s report is designed to make that distinction actionable.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com