

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Omni‑channel & Warehouse Management Systems Market to Reach USD 12,459.13 Million by 2032, Driven by a 13.98% CAGR

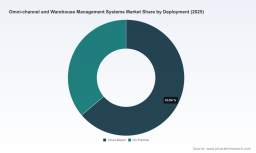
Worldwide Omni-channel and Warehouse Management Systems Market — Strategic Imperatives for 2026
PW Consulting today publishes an executive preview of our flagship market study, Worldwide Omni-channel and Warehouse Management Systems Market (Base Year 2025; Forecast 2026–2032). The analysis reconfirms that warehouse execution and omni-channel orchestration are no longer niche IT projects but strategic platforms shaping go-to-market agility, compliance resilience, and cost-to-serve across supply chains. Our modeled global market reached approximately USD 4,985 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 13.98% through the forecast horizon. By 2032 the market is expected to more than double from today’s baseline, underscoring the urgency of programmatic investment decisions in 2026.
Worldwide Omni-channel and Warehouse Management Systems Market
Why this report matters to executive decision-makers in 2026
- Timing and leverage: With the market accelerating, 2026 is a pivotal year for deciding whether to modernize incrementally or to fund transformational warehouse and omni-channel platforms. The pace of adoption—and the integration of WMS/WES with OMS, TMS and automation—will determine which players capture disproportionate operational value.
- Risk mitigation for compliance-heavy sectors: Strengthened traceability mandates (for example, drug and food safety directives) make advanced lot/serial tracking and automated audit trails mandatory capabilities. The report maps the regulatory vector and shows where investments produce compliance with minimal ongoing lift.
- Quantified operations impact: Leading WMS/WES deployments deliver measurable throughput and availability gains. Our synthesis of practitioner data shows typical throughput improvements of 15–25% and reductions in downtime up to 30%, metrics critical for ROI conversations with CFOs and COOs.
- Vendor consolidation dynamics: Market concentration is increasing—our analysis shows the top three vendors account for roughly one-third of market value while the top five approach half the market—creating competitive dynamics that influence pricing, integration ecosystems, and partner strategies.
What the PW Consulting report contains — practical, executable content
This study is designed to be operationally useful to CIOs, supply chain heads, and digital transformation sponsors. The deliverables include:
Worldwide Omni-channel and Warehouse Management Systems Market
- Proprietary market model (2020–2032) with scenario layers for adoption curves, cloud migration rates, and automation penetration.
- Vendor landscape and scorecard covering product capability, integration breadth, cloud maturity, vertical fit, and partner ecosystems—enabling shortlists for RFPs.
- Decision frameworks for build vs. buy vs. partner, including TCO and multi-year ROI templates tailored to enterprise, mid-market, and 3PL profiles.
- Implementation playbooks: phased migration roadmaps, data migration checklists, cutover sequencing, and KPI dashboards for continuous improvement.
- Automation and integration playbooks: WMS-to-WES-to-WCS/robot orchestration, API patterns, and best-practice conveyor/robot control strategies.
- Compliance and security annexes that translate evolving traceability and data-protection mandates into testable system requirements and audit procedures.
- Operational case studies and vendor-neutral sample contracts that accelerate procurement and reduce negotiation cycles.
To preserve the value of the full dataset for licensed subscribers, this release intentionally omits granular split data for regions, deployment models, and end-users. The full report contains those segment-level insights together with downloadable spreadsheets and an interactive scenario tool.
Worldwide Omni-channel and Warehouse Management Systems Market
Market dynamics shaping vendor selection and implementation
- Cloud-first economics: Cloud-native WMS/WES deployments have achieved material adoption—approximately half of new deployments in 2026—driven by lower upfront capital, elastic scaling for peak seasonality, and continuous functional updates. Buyers must weigh operational flexibility versus long-term hosting cost trajectories.
- Labor dynamics and productivity: Chronic labor shortages and rising wage pressure tilt investment calculus toward systems that materially lift throughput and reduce idle time. Buyers should demand validated productivity metrics and ensure SLAs reflect realized throughput gains.
- Compliance and traceability: Stricter global regulations (e.g., pharmaceutical serialization and food safety directives) have made built-in traceability and auditability baseline requirements. Systems that automate compliance updates and maintain immutable audit trails reduce recall and compliance risk.
- Security and data governance: As logistics platforms centralize operational data, security controls, role-based access, encryption, and continuous risk monitoring are core procurement criteria—especially for multi-tenant cloud offerings.
- Integration with automation and transportation: The most successful deployments are those where WMS/WES, WCS, TMS and OMS form a cohesive orchestration layer. Recent industry M&A and partnerships reflect a move toward tighter execution suites rather than point solutions.
Competitive landscape — what to expect from leading suppliers
The ecosystem is populated by established tier-1 suite vendors, specialized WMS providers, and regional champions. The CR3 and CR5 concentration metrics indicate a market in which scale provides negotiating and integration advantages, but midsize and niche vendors continue to win on vertical specialization and implementation speed.
- Manhattan Associates: A market-recognized leader with a cloud-native WMS that emphasizes omni-channel fulfillment, real-time visibility, and labor optimization. Recognized repeatedly in industry benchmarks, it remains a go-to for complex, global retailers and distributors.
- Blue Yonder: Offers mature WMS functionality paired with workforce and returns management, increasingly layering AI-based orchestration for highly dynamic distribution networks.
- SAP: SAP EWM is positioned for enterprises seeking deep ERP-supply chain alignment, enabling organizations to leverage a common master data fabric at scale.
- Oracle: Oracle’s cloud WMS and NetSuite options suit organizations prioritizing integrated ERP-to-WMS stacks and unified financial/operational reporting.
- Infor: Focuses on warehouse operations and 3PL capabilities with a cloud-first posture attractive to manufacturing and food & beverage customers.
- Körber Supply Chain (Infios): Following its rebrand and strategic acquisitions, the vendor is bundling WMS, WCS and TMS capabilities to reduce planning silos and support heavy automation footprints.
- Specialists & regional leaders: Firms such as Softeon, Tecsys, Deposco, Made4net, Mecalux and Generix Group offer strong vertical or regional propositions—particularly attractive for mid-market, healthcare, and 3PL-specialized use cases.
- Systems integrators & transformation partners: Logistics-focused consultancies and SI partners bring critical domain experience; their selection is often as decisive as the software choice itself.
Recent strategic moves validate these dynamics: Körber’s acquisition of MercuryGate (Oct 2025) underscores the convergence of transport and warehouse execution; Hardis’s expansion with cloud and automation partners (Jan 2026) demonstrates the premium on partner ecosystems; Honeywell’s launch of a cloud WES (Mar 2025) signals increased vendor focus on real-time orchestration.
Practical guidance for procurement and leadership teams
- Define outcome-based KPIs first: Begin with measurable outcomes—order cycle time, perfect order rate, cost-to-serve—then map functionality and integration needs to those KPIs.
- Pressure-test vendor claims: Require references with similar volume and automation profiles, and insist on performance-based acceptance criteria tied to throughput and availability.
- Adopt phased migration: Start with a controlled scope (select SKUs, a single DC, or a single fulfillment channel) to de-risk integration and accelerate time-to-value.
- Plan total-cost-of-ownership: Model multi-year cloud hosting, licensing, integration, and continuous improvement costs rather than comparing upfront license fees alone.
- Preserve flexibility: Architect for modularity—APIs, event-driven integrations, and container-friendly deployments preserve optionality as automation and robotics evolve.
Risks and scenario thinking for 2026
- Cloud hosting cost volatility: The economics of cloud are favorable for elastic scale, but buyers should stress-test projections for large data, edge-processing and peak seasonism to avoid surprise cost escalation.
- Regulatory shocks: Rapidly changing traceability and data residency rules can force unplanned remediation—choose solutions with rapid compliance update paths.
- Integration complexity: The promise of end-to-end orchestration is only realized where rigorous data governance and C-suite sponsorship are in place.
- Vendor concentration effects: Consolidation can reduce choice and increase integration lock-in; balanced procurement should combine strategic partnerships with competitive benchmarks.
Next steps — how PW Consulting helps
Our full report offers the granular, actionable intelligence that procurement, operations and IT teams need to make defensible investment decisions in 2026. Subscribers receive the market model, vendor scorecards, implementation templates, and country- and vertical-level forecasts to tailor programs to their risk profile.
For senior leaders preparing board-level business cases, our research provides the quantified rationale and implementation risk mitigation playbooks to accelerate approvals and ensure measurable outcomes. Note: this press release deliberately omits segment-level splits and detailed vendor financials to preserve the integrity of the licensed dataset—these are available in the full, downloadable report.
PW Consulting’s Worldwide Omni-channel and Warehouse Management Systems Market study is designed as a hands-on guide for executives who must translate market momentum into repeatable operational advantage. In a market growing at nearly 14% annually and reshaped by cloud, automation, and regulation, 2026 will be the year teams either secure durable competitive advantage or accept escalating operating costs and compliance risk. The choices you make now will define logistics performance for the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com