

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Power Energy Management System (EMS) Market Poised for Rapid Growth — 13.52% CAGR Forecast (2026–2032)

Worldwide Power Energy Management System (EMS) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting's latest market study on the Worldwide Power Energy Management System (EMS) market delivers a compact, high-conviction synthesis of the forces shaping procurement, investment, and competitive strategy entering 2026. This preview outlines the report’s strategic value for executive teams and investment committees while deliberately reserving full, granular segment and regional tables for the complete report. The intent is to equip leaders with the right questions, priority actions, and risk signals so they can act confidently while motivating deeper engagement with the underlying datasets.
Worldwide Power Energy Management System (EMS) Market
Executive snapshot: momentum, scale, and visibility
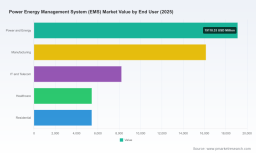
Between 2020 and 2025 the global EMS market experienced sustained expansion, reflecting the rapid adoption of digital grid controls, distributed energy resource (DER) orchestration, and asset-level optimization. On a headline basis, total market revenue expanded from USD 29,482.15 Million in 2020 to USD 54,318.94 Million in 2025. PW Consulting’s base-year analysis (2025) and scenario modeling across the 2026–2032 forecast window point to a compound annual growth rate (CAGR) of 13.52%, with total market size modeled through multiple macroeconomic, regulatory, and technology adoption trajectories. By the end of the forecast horizon, the market is projected to reach USD 131,964.75 Million—a scale that materially changes supplier economics, procurement levers, and M&A dynamics.
Worldwide Power Energy Management System (EMS) Market
Why this matters for 2026 strategic decisions
- Capex and procurement timing: The market’s rapid expansion compresses windows where technology choices are defensible for the long term. Organizations that delay standardization risk costly rip-and-replace cycles as interoperability norms consolidate.
- Vendor selection and partnerships: A moderate-to-high concentration among top suppliers shapes the bargaining landscape. Our concentration metrics show that top-three vendors command roughly one-third of the market while the top-five approach a majority share—an important input when assessing negotiation leverage and strategic partnerships.
- Regulatory runway: Recent code and policy movements are shifting functional requirements for EMS deployments, creating new compliance tasks and commercial opportunities for products that can certify to fresh standards.
- Service monetization: As systems scale, services and software monetization strategies (subscriptions, performance contracting, managed services) become central to total cost of ownership (TCO) and to recurring-revenue valuation models.
Market dynamics that will define winners and losers
- DER integration and virtual aggregation: National and regional policy updates—most notably roadmaps to large-scale virtual power plant aggregation—are raising functional requirements for EMS platforms. These platforms must now perform high-fidelity forecasting, secure bidirectional control, and market participation functions at scale.
- Standards and safety: The 2026 National Electrical Code update (relocating EMS provisions and clarifying distinctions between EMS and Power Control Systems) introduces compliance differentiation. Systems that clearly map to the updated Article 130 will gain procurement preference among regulated utilities and critical infrastructure operators.
- Grid modernization and transmission expansion: Transmission buildouts and utility-grade EMS upgrades (including approved upgrade projects at major ISOs) elevate demand for solutions that can ingest SCADA, phasor, and market data with low-latency analytics and deterministic control loops.
- Software-first architectures: Platforms that separate control-layer determinism from analytics and orchestration are preferred for scalability. This shift favors vendors with open APIs, edge-to-cloud strategies, and robust cybersecurity architectures.
- Economics of electrification: Rapid load growth in select geographies—driven by electrification of transport and digital infrastructure—creates asymmetric demand pockets that suppliers and system integrators must address with localized delivery models.
Competitive landscape — who to watch and why
The EMS vendor landscape remains a mix of global industrial conglomerates, specialized power-technology firms, and software-native challengers. PW Consulting’s strategic benchmarking flags a cohort of incumbent leaders and important innovators whose product portfolios and go-to-market footprints will shape 2026 outcomes. Representative profiles included in the report include:
Worldwide Power Energy Management System (EMS) Market
- Siemens AG (Munich, Germany) — Offers comprehensive grid-scale EMS solutions focused on transmission, generation optimization and renewables integration; a leader in utility-grade spectrum-level control capabilities.
- Schneider Electric SE (Paris, France) — Strength in facility- and grid-edge EMS platforms and extensive investments to expand digital service delivery across industrial and large commercial customers.
- ABB Ltd (Zurich, Switzerland) — Emphasizes real-time monitoring and control across industrial power applications; strong systems integration pedigree for large capital projects.
- GE Vernova (Boston, USA) — Focused on transmission and generation asset digitalization with solutions optimized for grid-scale operations and asset health analytics.
- Honeywell International Inc. (Charlotte, USA) — Targets industrial EMS and demand-response use cases with integrated service offerings.
- Eaton Corporation plc (Dublin, Ireland) — Known for power distribution, branch monitoring, and reliability-centered EMS deployments.
- Emerson Electric Co. (St. Louis, USA) — Focused on generation and process control platforms with deterministic control capabilities.
- Johnson Controls International plc (Cork, Ireland) — Strong presence in building-focused EMS and growing digital services revenue in North America.
- Rockwell Automation Inc. (Milwaukee, USA) — Integrates EMS capabilities with factory automation, optimizing energy in manufacturing operations.
- Mitsubishi Electric, Yokogawa, Hitachi Energy — Each brings regional strengths, deep control-systems experience, and differentiated offerings suited to specific utility and industrial applications.
PW Consulting’s competitive maps are built to support three strategic use-cases: supplier shortlisting, partner due diligence, and acquisition target screening. While the preview highlights vendor capabilities, the full report provides detailed vendor scorecards, capability matrices, and reference deployments.
Regulatory and policy tailwinds — implications for procurement and compliance
- Code renewal and functional clarity: The NEC 2026 relocation and clarifications for EMS vs. PCS functions introduces new compliance checkpoints that buyers must include in RFPs and test procedures.
- DER aggregation targets: Government-led VPP roadmaps place new performance obligations on EMS platforms to support grid services markets and aggregated resource participation.
- Standards alignment: ISO 50001 and other energy management standards continue to influence specification language for performance guarantees and energy savings verification.
What the PW Consulting report delivers — an action-oriented toolkit
Beyond market sizing and forecasts, the report is structured around the tactical needs of CFOs, CTOs, system integrators, and utility procurement teams. Key deliverables include:
- Scenario-based financial models to stress-test TCO across hardware, software, and services bundles under alternative adoption curves.
- Vendor evaluation frameworks with weighted scoring across technical fit, scalability, integration cost, cyber posture, and business model (license vs. SaaS vs. managed services).
- Implementation playbooks for pilots and rollouts—including test plans aligned to the updated NEC functional requirements and market participation criteria for VPPs.
- M&A and partnership pipelines highlighting adjacent technology providers where buy-build decisions materially affect time-to-market.
- Regulatory mapping and risk dashboards keyed to region-specific code changes, transmission expansion plans, and public-sector procurement windows.
- Cybersecurity and resilience requirements, including recommended control sets and third-party validation steps for mission-critical EMS deployments.
Practical guidance for 2026 boardroom decisions
- Prioritize interoperability and upgradeability: Choose EMS architectures that separate control determinism from cloud orchestration and provide open APIs to minimize lock-in and future integration costs.
- Embed compliance in procurement: Update RFP templates to require conformance evidence for the latest code revisions and DER-messaging standards—early compliance reduces retrofit costs.
- Shift from capex-only to lifecycle economics: Evaluate supplier offers on the basis of verified performance outcomes and revenue-sharing models tied to market participation and congestion-management revenues.
- Pilot with measurable KPIs: Run short, focused pilots with predefined KPIs (dispatch accuracy, net energy savings, resilience improvements) and staged rollouts to limit exposure and accelerate learning.
- Prepare for consolidation: Given the market concentration dynamics, prepare sourcing strategies that balance the resilience of incumbents with the innovation potential of specialized entrants.
Signals to watch in the next 12–18 months
- Major ISO/utility EMS upgrade approvals and awarded contracts—these will indicate which platforms are gaining super-regional traction.
- Standard and code implementation guidance tied to Article 130 and interoperability testing regimes; look for certified reference implementations.
- Corporate investment announcements and factory/service expansion programs—capital commitments by leading vendors signal supply-side readiness and competitive intent.
- Emergence of new commercial models—performance contracting, energy-as-a-service, and market-revenue share models will reframe project ROI calculations.
Concluding perspective — the strategic opportunity
The EMS market is transitioning from discrete control-system deployments to integrated platforms that unlock new value streams: market participation, resilience services, and operational optimization across distributed and central assets. For 2026 decision-makers, the opportunity lies in aligning procurement choices with long-horizon interoperability, regulatory-proof architectures, and partner ecosystems that can scale both geographically and functionally. PW Consulting’s full report contains the detailed segmentation, regional maps, and quantitative model outputs that underpin the strategic recommendations summarized here; those datasets are intentionally gated to ensure decision-makers access the validated inputs needed for transaction-grade planning.
For executives preparing budgets, negotiating supplier agreements, or evaluating M&A targets in 2026, this preview identifies where to focus due diligence and what trade-offs matter most. To access the complete dataset, vendor scorecards, and downloadable financial models that informed these findings, please consult the full Worldwide Power EMS Market report on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Worldwide Power Energy Management System (EMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com