

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Ferrite Cable Cores Market Valued at USD 750 Million in 2025, Set for Continued Expansion Through 2032

Worldwide Ferrite Cable Cores Market — Strategic Briefing for 2026: Navigating Demand, Supply Risk, and Competitive Positioning
Executive summary
As the adoption of higher-speed data interfaces, electrified mobility, and dense power electronics accelerates, the ferrite cable cores market is entering a phase of steady expansion. Our latest PW Consulting study (base year 2025; historical window 2020–2025; forecast 2026–2032) finds the global market at approximately USD 750.0 Million in 2025, tracking a compound annual growth rate (CAGR) of 5.23% through the 2026–2032 horizon. By 2032, the market is projected to exceed the USD 1.0 Billion threshold under our baseline scenario.
Worldwide Ferrite Cable Cores Market
This briefing is written to support executive teams responsible for procurement, product engineering, and corporate strategy as they build 2026 action plans. It highlights the strategic levers that matter most — supply resilience, product differentiation for next‑generation interfaces, and competitive posture — while intentionally withholding granular segment-level figures to encourage direct engagement with the full report for transaction-ready intelligence.
Worldwide Ferrite Cable Cores Market
Market trajectory and what it means for 2026 decisions
The market recovery observed in the 2020–2025 period reflects a combination of cyclical recovery post-2020, rapid upgrades in consumer and enterprise connectivity, and the early electrification wave in automotive applications. The mid-single-digit CAGR we model suggests a market where incremental volume growth is coupled with rising technical demands: wider bandwidth EMI suppression, automotive-grade qualifications, and material-grade differentiation (e.g., NiZn vs. MnZn ferrites).
Worldwide Ferrite Cable Cores Market
- Strategic implication: Suppliers and OEMs should treat 2026 as a year to shift from tactical sourcing to capability-building — qualifying alternative materials, locking multi-year supply agreements, and embedding ferrites earlier in product architecture discussions.
- Risk implication: Moderate growth masks asymmetric risk — pockets of acute supply pressure (certain ferrite chemistries) and rapid price moves that can erode margins if left unhedged.
Supply chain dynamics: raw materials, tariffs, and lead times
Our sector analysis confirms concentration in upstream raw materials: iron oxide, manganese, and zinc feedstocks remain heavily sourced from a small number of exporting countries, with China accounting for well over four-fifths of global supply. This structural exposure has real consequences for 2026 procurement strategy:
- Tariff and trade policy: Recent trade measures have materially increased the landed cost of some ferrite components into key markets. Buyers should model landed-cost scenarios with sensitivity to tariff escalation and local content thresholds.
- Lead-time pressure: Specific chemistries have experienced extended lead times amid demand surges for EV and data center cabling. Our fieldwork documents supply-to-order cycles stretching multiple months for NiZn grades — a factor that should be integrated into inventory and NPI timelines.
- Price volatility: Benchmarked market data show notable price inflation in snap-on core products during the latest annual cycle. Pricing strategies must therefore include indexed clauses, multi-year purchase commitments, and vendor diversification plans.
Regulatory and standards headwinds
Regulatory compliance is non-negotiable. The EU RoHS framework and analogous global restrictions continue to constrain allowable concentrations of certain heavy elements, shaping material selection and qualification timelines. At the same time, accelerated performance requirements for 5G, USB4, PCIe Gen5 and automotive Ethernet drive tighter electrical and mechanical tolerances.
Strategic implication: Product teams must reconcile dual imperatives — material compliance and high-frequency performance — by investing in advanced material characterization and closer, co‑development relationships with ferrite manufacturers.
Competitive landscape: how major players are positioning
The market exhibits moderate concentration (CR3 ~38.45%; CR5 ~52.12%), indicating a mix of global leaders and regional specialists. Key incumbent capabilities include broad product portfolios, materials science IP, and certifications for automotive and industrial use. Our competitive assessment — synthesized from supplier disclosures, product roadmaps, and recent corporate developments — yields the following directional insights:
- TDK Corporation (Tokyo): Continues to push high‑permeability snap-on cores optimized for 5G and automotive Ethernet. Recent product introductions underscore their strategy of combining materials innovation with system-level qualification for next-generation cable standards.
- Murata Manufacturing (Nagaokakyo): Focuses on miniaturized ferrite beads and compact cores for high-speed data links. Their trade-show showcases and compact product lines favor OEMs prioritizing space-constrained applications.
- Laird Technologies (DuPont) (Chestnut Ridge, NY): Advancing automotive-grade portfolio through AEC-Q200 qualifications — a clear signal to EV supply chains and charging infrastructure OEMs that they intend to be a preferred supplier for automotive applications.
- Fair‑Rite Products (Wallkill, NY): Leverages a deep material-engineering catalog; recent catalog updates target USB4 and PCIe Gen5, aligning with the high-speed interface market’s needs.
- Ferroxcube (Yageo), Vacuumschmelze, Mitsubishi Materials, Samsung Electro‑Mechanics, Sunlord Electronics, and Epcos (TDK subsidiary): Each pursues a blend of regional strength and targeted technical differentiation — from toroidal power line filters to cost-optimized snap‑on assemblies for consumer cables.
Recent vendor activity — new high‑frequency products, automotive certifications, and catalog refreshes — reveals how incumbents are defending technical leadership while chasing adjacencies. For entrants and smaller suppliers, this dynamic increases the importance of niche specialization (e.g., custom formulations, rapid prototyping services, or local assembly) to avoid commoditization.
Where the opportunities are — and what we intentionally do not disclose here
Our full analysis identifies high-conviction opportunities across product development, procurement, and M&A. Examples include:
- Engineering partnerships to co-develop ferrite chemistries tuned for automotive Ethernet and high-speed data cables.
- Backward integration and local-sourcing strategies to mitigate tariffs and raw material concentration risk.
- Premiumization of cable assemblies by embedding certified, performance-grade cores as a differentiation point for OEMs targeting enterprise and automotive channels.
- Targeted acquisitions of regional specialists to accelerate market entry and secure faster time-to-market for automotive qualifications.
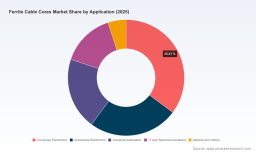
Following the “trailer” principle, this release highlights the strategic arcs above but withholds granular segment and regional datapoints — including the precise split of demand by region, core type, and application — to protect the report’s transaction-ready insights. These detailed slices, supplier scorecards, and scenario-based valuation models are accessible in the full PW Consulting report.
What the PW Consulting report provides — practical, implementation-ready modules
For teams preparing 2026 budgets and roadmaps, our report is structured to be operational from day one. It includes:
- Verified market sizing and demand model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity to pricing, tariff, and adoption curves.
- Supply chain heatmaps and a supplier risk index that quantifies raw-material dependency, geopolitical exposure, and lead-time variability.
- Material and performance matrixes that map ferrite chemistries to application-level electrical requirements and compliance constraints.
- Competitive benchmarking and vendor scorecards covering technology, certifications, capacity, and go-to-market reach.
- Procurement playbook: contract clauses, hedging constructs, multi-sourcing frameworks, and near-shore vs. on-shore decision criteria.
- M&A and partnership scouting lists with valuation frameworks and integration checklists tailored to strategic buyers.
- Roadmaps for product development: qualification timelines (incl. automotive standards), testing protocols, and cost-vs-performance trade-off calculators.
How to use this intelligence to shape your 2026 plan — a practical checklist
We recommend executives apply the following five-step sequence in Q1–Q2 2026:
- Quantify exposure: Run our supplier risk index against your bill of materials to identify single-source ferrite dependencies and tariff-sensitive nodes.
- Prioritize product roadmaps: For each SKU, score the value of upgrading to automotive/5G-capable ferrite cores vs. the incremental cost and qualification time.
- Lock strategic suppliers: Negotiate conditional multi-year contracts with capacity reservation and price-adjustment triggers tied to raw material indices.
- Pursue targeted partnerships: Co-design ferrite solutions with tier-1 suppliers for critical applications rather than relying solely on off-the-shelf parts.
- Prepare a contingency kit: Build inventory buffers for chemistries with the longest lead times and qualify second-source materials to avoid NPI delays.
Closing perspective and next steps
The ferrite cable cores market in 2026 is less about explosive volume growth and more about technical and supply-chain differentiation. Companies that invest now in materials know-how, procurement sophistication, and vendor co-development will capture disproportionate value as interfaces converge on higher frequencies and automotive electrification deepens.
PW Consulting’s full Worldwide Ferrite Cable Cores Market report delivers the granular segmentation, supplier scorecards, and scenario models that operational teams need to convert strategic intent into executable programs. To review the complete dataset, regional and application splits, and proprietary vendor rankings, access the full report via the PW Consulting portal.
For bespoke briefings, supplier workshops, or a tailored procurement stress‑test modeled on your BOM, contact the PW Consulting Industry Strategy team to schedule a 1:1 consultation.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com