

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Low‑Power Solid‑State Microwave Generator Market to More Than Double from USD 684.83 Million in 2025 to USD 1,663.76 Million by 2032 — 13.52% CAGR Fueled by GaN Adoption and Asia‑Pacific Demand
By pmarketresearch, 2026-07-15
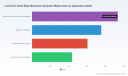
Worldwide Low-Power Solid State Microwave Generator Market: Strategic Intelligence Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Low-Power Solid State Microwave Generators synthesizes five years of historical data (2020–2025) and a seven-year forecast (2026–2032) to deliver actionable strategic intelligence for corporate leaders, R&D heads, and investors shaping 2026 priorities. The market is on a clear, high-growth trajectory—expanding from the low hundreds of millions (USD) in 2020 to well beyond the mid‑hundreds by the 2025 base year, and projected to surpass the billion-dollar threshold later in the forecast window—at an compound annual growth rate (CAGR) of approximately 13.5% over the study period. That pace and scale create both opportunity and complexity for players across the value chain.
Worldwide Low-Power Solid State Microwave Generator Market
Why this report matters for 2026 strategy
-
Fast-moving technology and materials dynamics: GaN (gallium nitride) and advanced LDMOS architectures are accelerating performance gains—efficiency, thermal density, and frequency agility—that shift competitive parameters away from legacy magnetron-based systems. For 2026 planning, understanding technology roadmaps and supply levers is table stakes.
Worldwide Low-Power Solid State Microwave Generator Market -
Regulatory and standardization pressure: Food safety regulators and other sectoral bodies are formalizing requirements that directly reward tighter frequency control and reproducible heating profiles—capabilities where solid-state designs excel. Firms must align product development and validation plans to these evolving compliance baselines to unlock industrial and medical contracts.
Worldwide Low-Power Solid State Microwave Generator Market -
Consolidating vendor landscape: Market concentration metrics indicate that the top-tier suppliers control a meaningful minority of market revenue, with an additional group of established and emergent specialists comprising a competitive second tier. For 2026 procurement and partnership strategy, this means a mix of negotiating power and niche supplier dependency.
-
Commercialization inflection: End markets such as laboratory, R&D, plasma processing, precision medical systems, and targeted industrial heating applications are moving from pilot projects to scaled deployments—creating revenue inflection points for vendors who can combine modular, serviceable hardware with systems-level controls and software.
Executive takeaways for boardrooms and product teams
-
Prioritize GaN-enabled roadmaps where short-term power efficiency and thermal density drive customer ROI. Invest in validation partnerships with early adopter integrators who can demonstrate lifetime throughput and energy savings under real-world operating cycles.
-
Embed regulatory compliance into product development lifecycles. For 2026 bids—especially in food and medical adjacent applications—compliance evidence and deterministic heating performance will be differentiators during procurement evaluations.
-
Design for modularity and field serviceability. Product families that allow rapid module swaps and in-situ diagnostics reduce downtime and increase appeal to system integrators and OEMs operating in production environments.
-
Develop multi-tier go-to-market plays: (a) direct enterprise sales for high-value industrial accounts, (b) channel partnerships for OEM integration, and (c) a developer ecosystem for third-party control and analytics platforms.
-
Manage supply chain and component risk—GaN wafer and compound semiconductor sourcing, and key passive and thermal-management suppliers—through dual-sourcing, strategic inventory, and long-term contracts to avoid bottlenecks as demand scales.
What the PW Consulting report contains (practical, operational sections)
-
Market sizing and forecasting methodology: transparent scenario modeling, sensitivity testing across material costs, adoption curves, and regulatory timelines, with downloadable model files for client use.
-
Technology and BOM analysis: component-level cost benchmarking, thermal and power-density trade-off matrices, and lifecycle TCO models for competing architectures (GaN vs. LDMOS vs. hybrid approaches).
-
Competitive benchmarking and supplier scorecards: capability maps covering product breadth, modularity, field serviceability, frequency agility, controls software, and warranty/service models—designed to inform vendor selection and M&A diligence.
-
Regulatory and standards compendium: a practical digest of country- and sector-specific requirements affecting acceptance testing, labeling, and safe operation—critical for market entry and certification planning.
-
Use-case playbooks and pilot templates: step-by-step engagement frameworks to run pilots in laboratory, R&D, medical, and targeted industrial heating applications, including KPI definitions, data capture templates, and ROI gate criteria.
-
Commercial and pricing playbooks: recommended margin stacks, recurring-service pricing models, and bundling strategies for hardware, integration, and analytics services to accelerate adoption while protecting margin.
Competitive landscape—how leading vendors are positioning for 2026
The market comprises a blend of specialized microwave OEMs, high-performance component manufacturers, and larger instrumentation companies bringing rack-scale, water-cooled systems. Across this field, several strategic patterns are emerging:
-
Specialists with focused product lines are pushing modular, field-serviceable units optimized for plasma, R&D, and medical applications. These firms emphasize repairability, compact form factors, and ISM-band centric designs—features attractive to production and lab customers seeking uptime and predictable maintenance economics.
-
Larger instrumentation companies are leveraging scale to offer higher-power rack-mount solutions with integrated cooling, networked control, and long-term service contracts—positioned for industrial deployments and research institutions demanding turnkey reliability.
-
New entrants with GaN-native platforms are accelerating frequency agility and efficiency claims, and seeking to displace legacy magnetron-based installations where reproducibility and emissions controls are key selling points.
Representative vendors covered in the report include established European and North American specialists, agile US-based GaN innovators, and Asia-based module suppliers. Our company dossiers profile product ranges, technology differentiators (e.g., patented auto-tune algorithms, field-repairable modular designs, and liquid versus air cooling trade-offs), recent product launches, and go-to-market signals—enabling buyers and partners to assess fit quickly.
Recent industry developments shaping 2026 priorities
-
Product line expansions from GaN-focused vendors have broadened the addressable use cases from R&D into higher-throughput industrial and test applications—raising the bar on integration and software control expectations.
-
Modular 1 kW-class generator modules with distributed software architectures have been introduced by several OEMs, signaling an industry shift toward scalable hardware building blocks that reduce time-to-market for systems integrators.
-
Peer-reviewed technical literature published in 2026 highlights measurable improvements in heating uniformity and energy efficiency enabled by pulsed, frequency-agile solid-state approaches—supporting adoption in sensitive applications such as food and biomedical processing.
-
Regulatory guidance and food-safety mandates in key markets are tightening requirements for predictable cold-spot behavior and repeatable thermal profiles, tilting procurement preference toward systems that can demonstrate narrow frequency stability and deterministic control.
Strategic playbook — recommended actions for 2026
-
OEMs and system integrators: Rapidly iterate GaN-inclusive product variants and publish validated performance datasets for prospective customers. Establish pilot partnerships with target verticals to generate reference installations that de-risk purchasing decisions for large accounts.
-
Component suppliers: Lock down supply agreements and co-development relationships with generator OEMs to secure predictable demand for GaN wafers and thermally optimized packaging—factor in qualification cycles into 2026 capacity planning.
-
Investors and corporate strategists: Use the report’s scenario-based financial models to stress-test investment cases under different adoption speeds and regulation rollouts. Prioritize companies demonstrating field-serviceable designs, strong IP in control algorithms, and validated regulatory pathways.
-
Procurement and operations leaders: Require deterministic performance metrics and service-level agreements in 2026 RFPs. Integrate pilot acceptance criteria focused on repeatability of thermal outcomes and ease of in-field maintenance.
How to use the report to de-risk 2026 decisions
The PW Consulting study is designed as an operational toolbox: model files to stress-test unit economics, vendor scorecards to accelerate shortlists, pilot templates to reduce proof-of-concept timelines, and regulatory checklists to preempt certification delays. For executives who must decide on capital allocation, product prioritization, or M&A in 2026, the report turns abstract growth projections into executable workstreams.
Accessing the full intelligence
This briefing highlights the strategic narrative and operational themes from our full market study. For clients and decision-makers who require the granular datasets, proprietary segment models, vendor scorecards, and downloadable financial templates referenced here, the full report and accompanying analytical workbench are available on PW Consulting’s report portal. The PW team also offers tailored briefings and scenario workshops to convert this intelligence into concrete 2026 action plans.
PW Consulting — strategic clarity for technology-led markets. Engage with our analysts to align your 2026 roadmap with the dynamics reshaping low-power solid-state microwave systems.
For detailed analysis of this topic, please visit the official page: Worldwide Low-Power Solid State Microwave Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automatic Cosmetic Powder Pressing Machine Market to Grow at 6.78% CAGR, Reaching USD 273.05 Million by 2032
By pmarketresearch, 2026-07-15
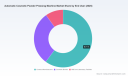
Worldwide Automatic Cosmetic Powder Pressing Machine Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research—the Worldwide Automatic Cosmetic Powder Pressing Machine Market report (base year 2025)—arrives at a pivotal moment for cosmetic manufacturers, equipment OEMs, contract packers and private equity investors. Our study synthesizes multi-year historical performance, forward-looking scenario analysis and practical implementation tools to convert market intelligence into executable choices for 2026. This briefing highlights the report’s strategic value and the immediate implications for capital allocation, sourcing strategy, and product roadmaps—while reserving the granular segment tables and dashboards for the full report.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
Why 2026 Is a Turning Point
The industry’s macro trajectory is unambiguous: the market is expanding at a robust compound annual growth rate of 6.78% through 2032, reflecting steady demand for automation and consistent product quality in color cosmetics manufacturing. In absolute terms, the global market size climbed through 2025 and is forecast to continue expanding into the next planning cycle. That expansion is driven by a trifecta of forces: regulatory tightening around manufacturing practices, intensifying pressure on labor availability and input-cost inflation, and the premiumization and SKU-proliferation trends within color cosmetics.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
For executives and procurement leads, 2026 represents a year to transition from exploratory pilots to scaled deployment. Investments made now in modern automatic powder pressing equipment are not only about throughput; they are investments in margin preservation, regulatory compliance and faster New Product Introduction (NPI) cycles.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
Strategic Themes Emerging from the Report
- Automation as a compliance and margin lever.
Regulatory developments such as the U.S. Modernization of Cosmetics Regulation Act have elevated Good Manufacturing Practice expectations. Our analysis demonstrates that automatic presses with repeatable compaction and integrated process controls materially reduce the batch-release risk window and downstream rework. For companies subject to new adverse-event reporting regimes, machine-level data capture becomes a compliance asset—one that can be monetized through faster lot-release and fewer recalls.
- Capital allocation must weigh TCO, not just CAPEX.
Procurement decisions in 2026 should move beyond headline price. Total Cost of Ownership (TCO) factors—downtime exposure, spare parts lead times, lifecycle service agreements, and software compatibility—drive long-term economics. Our report includes a practical TCO model and scenario-based ROI templates that help operators compare hydraulic, servo and rotary platforms across relevant plant layouts and SKU mixes.
- Modularity and Industry 4.0 compatibility are table stakes.
OEMs that have invested in modular tooling, PLC/servo architectures and Industry 4.0-ready telemetry are winning specification reviews. This trend favors vendors whose platforms enable faster changeover between compact formats, easier integration into MES/ERP and remote diagnostics—features that materially shorten NPI timelines.
- Supply-chain resilience influences choice of partners.
Raw-material and component cost signals—such as the observed stabilization (with modest upward pressure) in key steel inputs—mean OEMs and buyers should stress-test supplier roadmaps for sourcing concentration and alternative-material readiness. The report’s supplier-risk matrix and procurement playbook arm buyers with the right questions for RFQs and long-term service contracts.
What the Report Delivers: Practical, Actionable Intelligence
- Executive dashboards that translate top-line market growth into plant-level production scenarios and capacity planning matrices.
- Decision-ready TCO and ROI calculators with customizable inputs for labor, downtime risk and depreciation schedules.
- Procurement playbooks and RFQ templates tailored for hydraulic, servo and rotary press technologies, including test protocols for compaction consistency and powder handling.
- Regulatory compliance checklist aligned to evolving GMP expectations and adverse-event reporting requirements—designed to be incorporated into supplier evaluation and site-audit routines.
- Technology adoption roadmaps mapping component-level upgrades (PLC/servo, AI-enabled vision, integrated suction and dust control) to expected payback windows.
- Strategic M&A and partnership screening criteria, including a shortlist of acquisition-friendly targets, capability gaps and integration risk indicators.
Competitive Landscape: Who Matters—and Why
The market is neither a commodity race nor a closed oligopoly; it sits in a medium-concentration state where established OEMs coexist with specialized regional suppliers. This creates attractive opportunities for fast-follower manufacturers and platform consolidators. Our competitive landscaping sections blend capability assessments, recent product moves and go-to-market behavior into procurement-ready vendor profiles.
- GIENI (Shanghai GLENI Industry Co., Ltd.)
Positioning itself around full automation and modular servo platforms, GIENI has demonstrated a clear product cadence in 2025–2026 toward more user-friendly, PLC-controlled bottom-up presses with integrated powder management. Their recent product feature release and trade-show activity indicate an OEM pursuing global cosmetic manufacturers with a reliability and service-oriented pitch.
- Eugeng International Trade Co., Ltd.
Eugeng’s presence at major trade shows and its mix of automatic and laboratory hydraulic models make it a credible partner for both scale-up manufacturing and R&D facilities. Their portfolio is particularly attractive for firms seeking flexible capacity expansion without fully retooling their production strategies.
- Lorenzato S.r.l.
With decades of rotary press experience and a foothold in Industry 4.0-compatible systems, established European vendors such as Lorenzato are frequently selected where precision and integration with advanced production execution systems are prioritized.
- Specialist and regional suppliers
Several China-headquartered and other regional manufacturers compete on cost-effectiveness, rapid customization and local service footprints. Semi-automatic and lab-scale suppliers remain important for smaller brands and R&D centers that require nimble platforms for prototyping.
Collectively, the top-tier suppliers concentrate a material share of the market—our concentration metrics are included in the full report to help buyers assess the competitive risk of single-supplier dependence and the strategic opportunities for supplier consolidation or partnership.
Recent Signals and What They Imply for Buyers
- Product feature releases and showings in 2025–2026
OEMs that debuted user-centric features and showcased solutions at major expos signal a readied supply pipeline. For buyers, this indicates that lead times for modern platforms will begin to normalize as manufacturers ramp series production for upgraded models—an important timing consideration for 2026 capex plans.
- Input-cost and labor dynamics
Steel price behavior and rising input-cost expectations, combined with survey-reported labor-cost pressures, reinforce automation’s near-term payback. Our sensitivity analyses show that automation’s ROI becomes more attractive when buyers incorporate realistic labor and cost escalation into their financial models.
- Regulatory-driven demand for controlled processes
Enhanced regulatory scrutiny materially changes specification checklists for new lines. Manufacturers who proactively adopt automatic presses with integrated data capture gain both compliance resilience and a marketing advantage tied to quality assurance.
How Leaders Should Act in 2026
- Prioritize pilot-to-scale pathways.
Move beyond isolated pilots by defining a one- or two-line “scale demonstrator” that validates integration, maintenance cadence and SKU changeover times in a production setting. The full report provides a ready-to-use scale-demonstrator checklist.
- Negotiate service-forward contracts.
Seek multi-year, outcome-based service agreements that bundle remote diagnostics, spare-parts pooling and uptime guarantees. These reduce TCO volatility and are available as negotiation playbooks in our toolkit.
- Build supplier roadmaps, not one-off buys.
Rationalize equipment platforms across sites to reduce tooling proliferation and spare-parts complexity. Our vendor-matching framework helps align specific OEM capabilities with corporate product and manufacturing strategies.
- Factor regulation into procurement specs.
Embed GMP and adverse-event reporting readiness into RFQs. Doing so turns compliance from a cost center into a differentiator and speeds approval cycles for launches in regulated markets.
Where to Go from Here
PW Consulting’s report converts market momentum and competitive dynamics into concrete steps for 2026. We provide the numerical backbone (including market-size projections and concentration metrics), prescriptive procurement tools and vendor-risk assessments that allow leaders to operationalize decisions with confidence. To maintain the strategic benefit of the insights, the full dataset, interactive dashboards and downloadable playbooks are available through the report portal—designed to arm C-suite, manufacturing and procurement teams with what they need to execute in 2026 and beyond.
For a curated walkthrough of the findings and a tailored briefing for your program teams, contact PW Consulting to schedule a strategic session. The full report contains the exact segmentation breakdowns, regional scenarios, and vendor scoring matrices needed to finalize investment and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Cosmetic Powder Pressing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Photosensitive Resin Market to Expand from USD 6,750.5 Million in 2025 to USD 15,348.14 Million by 2032 at a 12.45% CAGR
By pmarketresearch, 2026-07-15
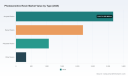
Worldwide Photosensitive Resin Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a preview of our forthcoming Worldwide Photosensitive Resin Market study, a hands-on strategic playbook designed to inform boardroom decisions throughout 2026. Built on a base year of 2025 and a forward-looking forecast to 2032, the report synthesizes primary market sizing, supply-chain mapping, regulatory sensitivity testing, and competitive intelligence to help manufacturers, OEMs, material suppliers, and investors navigate a market undergoing rapid technological, regulatory, and sustainability-driven change.
Worldwide Photosensitive Resin Market
Why this report matters for 2026 planning
The photosensitive resin market is at a strategic inflection point. After sustained compound annual growth through the early 2020s, the market reached a mature and investible scale in 2025 and is expected to more than double over the 2026–2032 forecast horizon at an underpinning CAGR of 12.45%. This trajectory is being driven by cross-industry adoption—from advanced additive manufacturing and electronics to regulated medical and dental applications—while supply-side dynamics (raw material volatility, capacity additions, and regional manufacturing shifts) continue to reshape cost and access.
Worldwide Photosensitive Resin Market
For executives preparing 2026 budgets, capital allocation, or M&A prioritization, our analysis layers quantitative scenario modeling on qualitative competitive assessment to answer the core question: where to place bets now to secure differentiated returns by 2030. This preview outlines the strategic takeaways; the full report contains the granular data tables, segment-level forecasts, and actionable worksheets that are intentionally withheld here to preserve the “trailer” experience and drive deeper engagement on our report page.
Worldwide Photosensitive Resin Market
What’s in the toolbox — practical deliverables included
- Actionable market-sizing and scenario models: Base-year calibration (2025) and three-tier scenario projections (conservative, base, upside) to stress-test investments under raw material shocks and regulatory shifts.
- Supply-chain and margin maps: Total-cost analyses from monomer and photoinitiator sourcing through formulation and surface finishing, including sensitivity to acrylate monomer price swings and photoinitiator availability.
- Regulatory and sustainability playbook: Pathways to certifications, compliance timelines for major jurisdictions, and ingredient substitution strategies to meet lower-toxicity and recyclability requirements.
- Commercial go-to-market templates: Channel strategies for industrial vs. medical/dental segments, pricing levers, and co-development levers with equipment OEMs.
- Competitive M&A & partnership screen: A prioritized list of potential bolt-on targets, capability gaps, and due-diligence checklists focused on IP, regulatory dossiers, and plant/warehouse footprints.
- Technology and product roadmaps: Comparative assessment of resin chemistries (acrylates, epoxies, polyesters and specialty formulations) and readiness timelines for high-value grades (high-temperature, flexible, biobased).
Market dynamics that will shape decision-making in 2026
- Demand acceleration with disciplined winners: Broad-based demand is projected to maintain strong double-digit growth rates; however, value accrues disproportionately to suppliers who can demonstrate regulatory compliance, formulation performance, and consistent supply.
- Raw-material volatility and procurement strategy: Acrylate monomer volatility—observed as material swings in recent years—remains a top tail-risk. Procurement teams must combine hedging, diversified sourcing, and strategic inventory buffers to avoid margin erosion.
- Capacity shifts and regional cost dynamics: Capacity expansions, especially in manufacturing hubs, have moderated some upstream input costs. Still, regional trade dynamics and local compliance obligations will influence where to site new plants or warehouses.
- Sustainability as a commercial filter: Regulators and buyers in developed markets are accelerating adoption of lower-toxicity and higher-recyclability formulations. Biobased and PCR-enhanced materials are migrating from R&D to commercial launches, creating both premium product opportunities and new cost implications.
- Productization and regulatory moats: Increasingly, regulatory clearances (e.g., medical/dental approvals) and validated formulation databases are becoming entry barriers. Suppliers with validated biocompatible portfolios or established certification pathways will command pricing power.
Competitive landscape — who to watch and what they signal
The competitive picture is a mix of specialized innovators, vertically integrated chemical majors, and equipment-aligned resin houses. Market concentration metrics show meaningful leaders but leave room for niche specialists and new entrants focused on performance or regulatory differentiation. Key players we profile include:
- Resione (Dongguan Godsaid Technology Co., Ltd.) — A China-based specialist focused on LCD/MSLA/DLP 3D printing resins. Their strategy highlights rapid iteration cycles and close OEM partnerships for desktop and industrial devices.
- UnionTech — Notable for releasing industrial-grade photopolymers tailored for orthodontics and footwear; their approach underscores the commercial edge of application-specific resins.
- Zicai Chemical and U-Sunny (Youyang Technology) — Regional suppliers emphasizing volume supply and formulation breadth, benefiting from proximity to regional manufacturing ecosystems.
- UpNano — A European innovator specializing in 2‑photon polymerization resins, representing the high-performance niche where material science drives system adoption.
- Formlabs, Liqcreate, 3D Systems — Equipment-aligned resin providers that leverage integrated hardware-software ecosystems, regulatory filings (notably for dental/medical grades), and captive distribution channels.
- Asahi Kasei, TOK, JSR, Shin-Etsu, Fujifilm Electronics Materials — Established chemicals and photoresist specialists with deep semiconductor and electronics footprints; these firms are expanding into advanced photosensitive resins and related high-margin segments.
Competitive themes to monitor: vertical integration into upstream monomers, specialization around regulatory-cleared medical and dental grades, and alliances with additive manufacturing OEMs to lock-in formulations. The report includes supplier scorecards and a negotiation playbook for buyer-side teams.
Recent industry signals and implications
- Channel expansion and specialty premium capture: Recent corporate disclosures indicate expanded UV-curable resin sales channels and growth in specialty segments, suggesting increasing segmentation between commodity grades and premium, performance-tested formulations.
- Circularity and recycled-content momentum: Reported sales growth in PCR-derived materials highlights viability of recycled inputs in photosensitive portfolios, creating both cost advantages and new compliance narratives.
- Biobased innovation: Developments in biomass-derived photoresists for semiconductor applications exemplify how sustainability mandates can seed new IP-driven product lines.
- Regulatory wins translate to commercial advantage: FDA clearances for dental resins demonstrate the asymmetric payoff of investing in regulatory dossiers; companies that secure such clearances often see material uplift in channel access and pricing power.
Strategic recommendations for 2026 (executive checklist)
- Adopt a dual-sourcing procurement strategy for critical monomers and photoinitiators; model margin impact across a range of price-volatility scenarios.
- Prioritize development or acquisition of regulatory‑cleared formulations if entering medical/dental segments—expected payback horizon shortens materially when certification is in place.
- Invest selectively in product-grade differentiation (heat resistance, flexibility, biobased content) tied to targeted end-markets rather than broad ‘portfolio expansion’.
- Explore co-development agreements with additive manufacturing OEMs to secure formulation lock-ins and bundled sales pathways.
- Evaluate bolt-on M&A within two strategic buckets: (a) capacity and regional footprint for supply resilience; (b) specialty IP and regulatory dossiers for margin capture.
- Build a quantified sustainability case that links recycled/biobased inputs to commercially relevant KPIs (cost delta, certification timeline, buyer preference scoring).
- Deploy an adaptive inventory policy that blends just-in-time with strategic safety stock tied to input criticality indices.
About report coverage and how to access full intelligence
This preview is intended to illustrate the strategic depth of our analysis while preserving the commercial value of the full dataset. The complete Worldwide Photosensitive Resin Market report provides the following (among other elements): detailed segment-level forecasts by application and region, supplier revenue models, pricing and cost curves, full competitive scorecards, proprietary M&A target screens, downloadable scenario models, and templates that executives can operationalize in 2026 planning cycles.
Note: To maintain the “trailer” experience, we have not disclosed segment-level revenue splits or disaggregated regional and application dollar amounts in this release. Those granular figures, including downloadable spreadsheets and sensitivity dashboards, are available in the full report on our website.
Next steps for decision-makers
Executives, strategy teams, and investment committees seeking to convert the market’s growth trajectory into defensible, profitable positions in 2026 should request the full report and model package. PW Consulting’s advisory team is prepared to deliver bespoke briefings, scenario workshops, and acquisition diligence support tailored to your strategic priorities.
Contact PW Consulting to schedule a confidential briefing and obtain access to the complete Worldwide Photosensitive Resin Market report and accompanying decision-support tools.
For detailed analysis of this topic, please visit the official page: Worldwide Photosensitive Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saddle Chairs Market to Reach USD 462.27 Million by 2032, Growing at 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
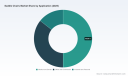
PW Consulting: Strategic Brief — Saddle Chairs Market Outlook to 2032
Executive synopsis
PW Consulting today publishes an actionable industry brief derived from our full Saddle Chairs Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The global saddle chairs market has moved from a modest base in 2020 to a materially larger opportunity set by 2025, and our model projects continued expansion through 2032 at a compound annual growth rate (CAGR) of 5.85%. By 2032 the market is expected to reach the upper end of our forecast envelope as demand drivers — from hybrid-workenabled offices to healthcare and industrial ergonomics — intersect with supply-side dynamics that will shape pricing, availability and route-to-market choices in 2026 and beyond.
Saddle Chairs Market
Why this brief should inform your 2026 decisions
- Timing and resource allocation: The market’s mid-single-digit CAGR signals steady growth that rewards early investments in product-led differentiation and supply chain resilience but penalizes slow movers in procurement and channel expansion.
- Procurement and supplier risk: Early 2026 raw material disruptions (notably polyurethane foam) have shown how quickly unit cost and lead-time assumptions can erode margin plans; our brief translates these disruptions into tactical mitigation steps for purchasing and sourcing teams.
- Product and R&D prioritization: End-user demand for active sitting solutions and sit-stand compatibility means product roadmaps must balance biomechanical performance, material cost and regulatory compliance — a trade-off we quantify and model for executive teams.
- Go-to-market and channel strategy: Hybrid work and new healthcare delivery models create white space for subscription, rental and aftermarket service propositions; the report shows how to size those opportunities and prioritize routes-to-customer for 2026 rollouts.
- M&A and corporate strategy: The market concentration is moderate — our concentration analysis shows a market where top-three players account for less than a third of value while the top-five fall well below majority control — creating opportunities for consolidation plays, bolt-on acquisitions and platform investments.
What the full report delivers (practical, executable content)
PW Consulting’s Saddle Chairs Market report was developed to be a practitioner’s tool, not an academic exercise. Beyond headline sizing and macro forecasts, the deliverable includes:
Saddle Chairs Market
- Transparent market sizing and demand-model methodology with build-ups for major demand channels and cross-checks against shipment and manufacturing capacity data.
- Segment-level dynamics and buyer archetypes — with practical persona maps for procurement managers, clinic owners, industrial buyers and corporate real estate planners.
- Supply-chain and cost-model templates that convert material, labour and logistics inputs into unit-cost sensitivity analyses (including stress-tests for raw material shocks such as foam shortages).
- Actionable go-to-market playbooks (channel economics, sample distributor agreements, subscription pricing frameworks and lead-gen tactics tuned to 2026 realities).
- Regulatory and compliance checklist tailored to ergonomic seating — a concise reference for product teams to manage safety, labeling and materials compliance across multiple selling geographies.
- Competitive playbooks: vendor scorecards, capability matrices and an M&A playbook with valuation heuristics, integration risks and three prioritized acquisition targets by strategic rationale.
- Scenario planning models (base, upside and downside) that allow executives to stress-test investment plans against variations in demand, input-cost inflation and time-to-market.
To preserve strategic advantage for clients, this release omits the granular segment-by-segment values and application-region splits included in the full report. Those detailed tables and interactive models are available only through PW Consulting’s report portal.
Saddle Chairs Market
Competitive landscape: who to watch
The competitive set blends specialist ergonomic manufacturers, legacy office furniture brands, and newer entrants focused on sustainability or vertical markets. Key vendors covered in the report include:
- Salli Systems (Finland) — Renowned for split-seat designs aimed at posture, circulation and pain reduction across office and healthcare use-cases.
- Score BV (Netherlands) — A manufacturer-led model with an in-house factory producing ergonomic saddle seating for offices, dental practices and industrial settings.
- HÅG (Flokk, Norway) — Iconic designs that extend the saddle concept into dynamic, sit-stand friendly seating for professional environments.
- Humanscale (USA) — Offers saddle stool variants emphasizing natural movement and clinical ergonomics for office and healthcare customers.
- Bambach Saddle Seat (Australia) — The original saddle-seat lineage with options for backrests and a strong foothold in dental and clinical markets.
- Treston (Finland) — Focuses on industrial-grade saddle chairs with ESD protection and robust adjustability for production environments.
- Branch Furniture (USA) — Newer entrant pairing design partnerships with sustainable material choices for active sitting furniture.
- ProNorth Medical (Canada) — A medical-focused supplier that launched a new saddle stool in late 2024 targeted at clinical posture and productivity gains.
- RGP Dental (USA) — Specializes in anatomically tuned saddles for dental practitioners and allied healthcare users.
Recent vendor activity underscores two strategic themes: (1) product refinement for specific professional segments (medical/dental and industrial), and (2) content- and channel-driven demand capture — exemplified by manufacturer-led education initiatives for dental practice setup. These vendor moves alter the competitive calculus for 2026 buyers and investors.
Market dynamics and implications for strategy
- Material-disruption sensitivity: The polyurethane foam shortage in early 2026 is a case study in how commoditized inputs can create asymmetric supplier power. We translate this into procurement playbooks that include forward hedging, alternative material testing and strategic inventory buffers keyed to product family economics.
- Regulatory baseline: Ergonomic seating continues to be governed by general furniture safety and material standards. Our compliance matrix helps product and quality teams track the limited but critical set of obligations that affect market entry timelines.
- End-user behavior: The proliferation of hybrid work and standing-desk pairings has elevated demand for active sitting solutions. The report quantifies how adoption curves differ between office, healthcare and industrial buyers — and shows which value propositions (comfort, health outcomes, productivity metrics) win initial procurement competitions.
- Channel and service opportunities: Rental, subscription and service-led models are gaining traction in specific buyer segments. We provide unit-economics templates that demonstrate when a subscription model increases lifetime value versus a traditional sales model.
- Consolidation potential: With a market that is neither highly concentrated nor atomized, selective consolidation offers strategic upside. The report’s M&A playbook identifies how acquirers can capture synergies in manufacturing, distribution and aftermarket services.
Opportunities and risks to prioritize in 2026
- High-priority plays: product differentiation for healthcare ergonomics, retrofit solutions for sit-stand ecosystems, and service offerings that monetize replacement parts and maintenance.
- Operational imperatives: secure diversified raw-material sources, reprice with indexed supplier clauses, and accelerate inventory and logistics visibility to weather intermittent shortages.
- Commercial strategies: invest in training and educational content for channel partners, pilot subscription models with enterprise customers, and use data from service interactions to inform product improvements.
- Risks to monitor: input-cost inflation, extended lead times from key component suppliers, and any shifts in regulatory expectations that could affect materials or labelling requirements.
How executives should use the report
This brief is intended as a decision-support snapshot. The full PW Consulting Saddle Chairs Market report is structured for busy executives to extract immediately usable outputs:
- Board-ready slides with topline scenarios and investment implications for 2026–2028.
- Procurement checklists and supplier scorecards to accelerate sourcing decisions within 60–90 days.
- Product development prioritization matrices that convert ergonomic benefit hypotheses into MVP specifications and cost targets.
- M&A diligence templates with valuation ranges tuned to the market’s concentration profile and margin structure.
Next steps and access
PW Consulting’s full report contains the granular segment tables, regional and application splits, and downloadable financial models that are intentionally withheld from this release to protect client advantage. Organizations that require the complete dataset, vendor scorecards, and implementation templates for their 2026 strategy cycles can access the full report and advisory services via PW Consulting’s research portal.
For leadership teams preparing budgets, sourcing strategies, product roadmaps or M&A pipelines in 2026, this release outlines the strategic contours you need to make high-confidence decisions. The detailed numbers, scenario models and executable playbooks supporting these conclusions are available through PW Consulting’s full Saddle Chairs Market report.
For detailed analysis of this topic, please visit the official page: Saddle Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laxative Prune Juice Market to Reach USD 661.6 Million by 2032 at 3.5% CAGR; North America Leads with USD 199.4M (Base Year 2025)
By pmarketresearch, 2026-07-15
Laxative Prune Juice Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As consumer demand for functional beverages continues to mature, prune juice—long positioned at the intersection of natural remedies and mainstream beverage retail—has reasserted itself as a niche category with broader strategic significance. PW Consulting’s latest market study distills the operational intelligence, scenario analysis, and deal-level insight that senior executives, category chiefs, and investors need to act decisively in 2026. This brief highlights the report’s strategic value while reserving detailed segmentation tables and proprietary datasets for the full report.
Laxative Prune Juice Market
Market snapshot: what the headline numbers mean for strategy
The global laxative prune juice market is at an inflection point. Our base-year assessment for 2025 pegs the market at approximately USD 520 million, and our forecast through 2032 anticipates steady expansion to roughly USD 662 million—implying a compound annual growth rate (CAGR) of about 3.5% over the forecast horizon. Those headline metrics capture the combined effects of product repositioning (from legacy medicinal use toward everyday functional beverage), modest premiumization, and channel migration toward instant-purchase formats and e-commerce.
Laxative Prune Juice Market
Two simple takeaways flow from these numbers. First, growth is meaningful but measured—sufficient to justify targeted investments, not blanket expansion. Second, the category’s structural profile (moderate concentration, see below) creates both scale advantages for incumbent processors and opportunity windows for fast-moving challengers that can exploit product innovation or supply-chain agility.
Laxative Prune Juice Market
Why 2026 is a decision year
- Supply normalization and contract renegotiation: Companies should use 2026 to renegotiate multi-year supply agreements and to build optionality into concentrate sourcing as crop cycles normalize after recent volatility.
- Product and channel differentiation: 2026 will determine which players can transition prune juice from a functional niche into a repeat-purchase mainstream item via product reformulation (taste, sugar reduction, functional fortification) and channel-first packaging.
- Regulatory & trade positioning: Recent tariff and inspection developments mean market access opportunities for exporters and new compliance responsibilities for importers—both require immediate operational planning.
- M&A and capacity decisions: With moderate market concentration and surging interest in natural functional beverages, 2026 is optimal for targeted bolt-on acquisitions and capacity investments that secure upstream supply and margin capture.
What our full report contains (actionable modules)
- Market sizing & high-resolution forecasting: multi-scenario top-down and bottom-up forecasts to 2032 with sensitivity testing by price, channel, and supply shock assumptions.
- Practical go-to-market playbooks: store-level assortment recommendations, online conversion levers, shelf pricing tactics, and promotional mechanics tailored to retail partners and direct-to-consumer models.
- Supply-demand balancing and raw-material risk maps: crop-cycle monitoring, concentrate availability scenarios, and contingency plans for low-yield years.
- Cost-to-serve and margin modeling: SKU-level contribution analysis, ingredient cost pass-through frameworks, and dynamic pricing templates.
- Regulatory & trade dossier: compliance checklist and playbooks for importers and exporters, including inspection and grading standards and tariff monitoring.
- Competitive intelligence & M&A playbook: company dossiers, valuation benchmarks, and acquisition target screening using proprietary deal filters.
- ESG and operational transformation blueprints: energy-efficiency capex models, carbon abatement pathways, and supplier engagement programs that reduce scope-3 risk.
Competitive landscape — who matters and why
The category is shaped by a mix of vertically integrated cooperatives, multinational food companies, and specialist concentrate suppliers. Market concentration is moderate: the top three firms account for roughly a third of the market while the top five approach mid‑single‑digit additional share—meaning leaders enjoy scale benefits but cannot afford complacency.
- Sunsweet Growers Inc. — A grower-owned cooperative with vertical integration from orchard to shelf. Sunsweet’s 2025–2026 activity (a new PlumGood product, facility upgrades focused on energy and GHG intensity, and crop/supply updates) signals a dual strategy: defend core retail channels while investing in sustainability and taste-led innovation. Their supply-side communications and capital investments make them a natural anchor partner for strategic alliances around traceable concentrate sourcing.
- Del Monte Foods, Dole, Welch’s, Ocean Spray — These household brands leverage broad retail distribution and brand equity to maintain visibility in the category. Their advantages are scale in trade spend, retailer relationships, and cross-category merchandising; their constraints are legacy cost structures and slower product development cycles relative to niche innovators.
- Sun-Maid, Valley View Foods, California Prune Packing — These players emphasize ingredient supply, concentrate manufacturing, and bespoke formulations for industrial clients. They’re critical nodes for companies seeking custom specifications or private-label supply.
- Rauch Fruchtsäfte — As a European concentrate specialist, Rauch illustrates the importance of geographic diversification in sourcing and the role of ingredient suppliers in supporting new product extensions across geographies.
Supply-side dynamics and raw-material signals
Raw-material risk is the single most important strategic variable. Industry reporting for the 2025/26 cycle estimates global prune production around 193,000 metric tons—approximately 6% lower than the prior cycle—with California’s 2025 crop estimated in the mid‑tens of thousands of metric tons and described as good quality. At the same time, producer price indices for plums and fresh prunes are consistent with elevated nominal price baselines seen in the last two seasons.
Implications: companies that lock in supply under favorable terms in 2026 will gain cost and quality advantages. Conversely, those lacking upstream exposure should plan for both margin compression in low-yield scenarios and increased buyer competition for concentrate. Our report provides hedging and contract designs (index-linked, volumetric carve-outs, quality tiers) that senior procurement teams can deploy immediately.
Trade policy and regulatory context
Two examples illustrate the operational impact of policy: the UK government’s suspension (and extension) of an import tariff that had previously affected certain suppliers is a near-term demand stimulus for exporters who can move product without a cost shock. On the compliance side, U.S. import requirements for prunes (inspection and grading under federal standards) remain a binding operational constraint for inbound flows. These developments mean exporters and importers must align commercial plans with customs, inspection, and trade teams to avoid execution risk.
2026 strategic playbook — priorities for leadership
- Secure diversified concentrate pathways: negotiate multi-sourced contracts with flexible take-or-pay and quality-tier clauses; develop contingency capacity with regional concentrate suppliers.
- Invest in taste and format innovation: reformulate to reduce perceived sweetness and add functional benefits (fiber-forward positioning, low‑sugar options, convenient single-serve formats).
- Leverage channel economics: prioritize e-commerce and subscription models where lifetime value is higher; use retailer category captains to test premium SKUs and cross-promotions.
- Prepare for measured M&A: target bolt-ons that provide upstream control (concentrates, drying capacity) or channel access (digital-first brands and D2C capabilities).
- Operationalize sustainability: replicate proven facility upgrades that reduce energy intensity; build measurable Scope 3 programs tied to orchard-level practices to de-risk procurement.
- Embed regulatory monitoring: operational teams should incorporate trade and inspection triggers into supply planning to exploit short-term tariff windows or to mitigate inspection-led delays.
How PW Consulting helps
PW Consulting partners with executive teams to translate these insights into executable plans: from transactional diligence on potential acquisitions to the deployment of a category-specific pricing engine and to operational redesigns that capture cost and carbon efficiency. Our deliverables include scenario-ready financial models, commercial playbooks tailored to retailer partners, supplier negotiation scripts, and a bespoke risk dashboard integrating weather, crop, and price indicators.
This briefing is a strategic preview. For commercial teams, procurement leads, and dealmakers seeking to operationalize a 2026 plan, the full Laxative Prune Juice Market report contains granular segmentation, regional flows, channel breakdowns, SKU-level pricing intelligence, and the proprietary datasets underpinning our forecasts. Access to the full dataset and downloadable templates is available on our report page.
PW Consulting — actionable intelligence, confidential datasets, and hands‑on implementation support to turn category insight into competitive advantage. For the complete analysis, including the detailed segmentation and model outputs that inform 2026 decision-making, please consult the full report.
For detailed analysis of this topic, please visit the official page: Laxative Prune Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide SGP Interlayer Films Market Reaches USD 306.69 Million in 2025, Forecast to Grow at an 8.0% CAGR
By pmarketresearch, 2026-07-15
Worldwide SGP Interlayer Films Market — Strategic Imperatives for 2026
As capital allocation, procurement, and product roadmaps are reset for 2026, the SentryGlas (SGP) interlayer films market has reached an inflection point. PW Consulting’s new Worldwide SGP Interlayer Films Market report (base year 2025; forecast period 2026–2032) combines market-scale forecasting, competitive intelligence, and transaction-grade playbooks to convert market complexity into executable choices. Our model shows the global market expanding at a compound annual growth rate (CAGR) of 8.0% through 2032, rising from a 2025 baseline to a materially larger market by 2032 — a trajectory that transforms strategy from defensive cost management to proactive capability building.
Worldwide SGP Interlayer Films Market
Why this market matters for boardroom decisions in 2026
- Market momentum and timing: After steady growth through the early 2020s, aggregate market value accelerates in the 2026 planning horizon. The step-change in demand dynamics — driven by structural-glazing adoption, higher performance safety glazing, and transport glazing spec upgrades — creates windows for first-mover advantage in supply, product premiumization, and integrated system sales.
- Concentration and bargaining power: The SGP interlayer market exhibits high concentration at the top. A small number of global leaders capture the lion’s share of commercial volumes and intellectual property, which reshapes supplier negotiations, certification leadership, and aftermarket services playbooks.
- Input-cost and regulatory pressure: Feedstock volatility is no longer edge-case noise. Spot pricing for PVB and ionomer feedstocks rose materially in late 2024 — spot levels increased by roughly 8% to around USD 2.45/kg — compressing margins for unconsolidated laminators and raising the value of long-term offtake agreements and hedging approaches. At the same time, regulatory and standards updates (notably EU Construction Products Regulation pRAVE testing requirements and REACH restrictions on certain plasticizers) are tightening the compliance bar for load-bearing and overhead applications.
- Trade policy friction: Sustained tariff overlays in core markets (for example, Section 301 duties in the U.S. on some imported interlayers) materially change landed cost calculations and near-term reshoring economics. Strategic sourcing decisions in 2026 must therefore account for effective rates, not headline supplier quotes.
What this report delivers — practical, transaction-ready intelligence
PW Consulting’s report is constructed to move teams from signal to action. It is not an academic survey — it is a practitioner’s toolkit that includes:
Worldwide SGP Interlayer Films Market
- Top-down market-size and forecast model (2020–2032) with scenario runs (base, upside, downside) and sensitivity matrices that translate demand swings into revenue, utilization, and unit-margin impacts for producers and laminators.
- Competitive-scorecard and value-chain maps showing IP positions, product tiers (standard PVB vs. high-performance ionoplasts), and commercialization pathways for premium SGP offerings.
- Supply-chain risk heatmaps and procurement playbooks, including recommended hedging approaches, contract templates for fixed-price volumes, and a supplier qualification checklist tailored to load-bearing and seismic glazing specifications.
- Certification and compliance navigator that links testing regimes (CE/pRAVE, EN 16613, REACH) to product development checklists, lab-capacity needs, and certification timelines aligned to construction cycles.
- Commercial playbooks — pricing ladders, margin engineering, product-bundle constructs (pre-laminated panels, system warranties), and channel strategies for interfacing with architectural glaziers, façade integrators, and transport OEMs.
- M&A and capacity-planning guidance: target screening criteria calibrated to CR3/CR5 market concentration, expected payback under base forecasts, and post-merger integration templates focused on IP, quality control, and regulatory consolidation.
Competitive landscape — who to watch and how to position
The market’s top actors combine differentiated IP with manufacturing scale, distribution networks, and certification leadership. PW Consulting’s qualitative and quantitative benchmarking finds that incumbent leaders maintain both technology and go-to-market advantages, but there are tactical openings for regional processors and vertical integrators.
Worldwide SGP Interlayer Films Market
- Trosifol (Wiesbaden, Germany) — As the commercial face of SentryGlas offerings, the company’s emphasis on high-strength ionoplast films and recent product innovation (for example, decorative colored SGP variants launched in late 2024) underscores the premiumization pathway: customers will pay for demonstrable UV stability and aesthetic differentiation. For competitors and partners, the strategic implication is clear — compete on systems and service, not just commodity price.
- Kuraray (Tokyo, Japan) — Kuraray’s manufacturing depth and certification progress (notably EN 16613 accreditation updates in mid-2024) position it as the strategic supplier for high-clarity, ultra-thick ionoplasts used in blast-, seismic-, and overhead-glazing applications. Buyers seeking to de-risk large projects should prioritize suppliers with certified supply and documented performance in these use cases.
- Everlam (Halen, Belgium) — Recent capacity expansions in Europe signal that regional laminators can scale to meet project-driven spikes in structural glass demand. For investors, Everlam-style plays highlight the attractive returns on targeted capacity investments when paired with long-term offtake agreements.
- Glastrotech (Dallas, TX, USA) — As a regional processor and authorized distributor, Glastrotech exemplifies the business model of localized pre-lamination and value-added panel supply for North American façade markets. The strategic takeaway: controlling last-mile value-adds (pre-laminated panels, warranty services) is a viable route to margin capture even where upstream resin IP is concentrated.
Collectively, the recent product launches, certifications, and capacity moves we observed in 2024–2025 are not isolated events — they form a pattern of incumbents fortifying supplier locks, while processors and regional players chase integration and service differentiation.
Strategic implications and recommended 90–180 day actions
- Procurement and cost protection — Execute multi-year supply agreements with price collars or indexation clauses to limit exposure to feedstock swings. Prioritize dual-sourcing for high-value ionoplast grades and seek co-investment clauses for capacity expansion in exchange for preferred volume.
- Certification-first product development — Align R&D roadmaps with mandatory testing timelines (CE/pRAVE and EN standards). For customers in regulated markets, certification latency is commercial risk; lead-time must be explicitly modeled into go-to-market timelines.
- Commercial differentiation — Bundle product warranties, facade integration services, and design-assist capabilities to capture higher ASPs (average selling prices) and to create switching costs versus commodity PVB supplies.
- Regional trade strategy — Model landed cost under different tariff and logistical scenarios (including Section 301 overlays). Where duty inefficiencies are persistent, evaluate near-market lamination or toll-processing investments to reduce landed cost and delivery risk.
- M&A and capacity plays — Prioritize bolt-ons that offer immediate access to certification labs, lamination capacity, or proprietary surface treatments over greenfield builds if near-term demand is uncertain but strategic positioning is required.
- Commercial operations — Implement project-level pricing models for large façade contracts, factoring in warranty exposure, certification costs, and cascading margin risks from raw material spikes.
Scenario planning — volatility is the constant
Our scenario suite projects that, even under conservative demand pathways, the structural-glazing-led portion of the market will expand materially by late-decade. That said, margin compressions can be severe in short windows when feedstock prices spike or when tariffs re-apply. Boards should insist on two deliverables for 2026: (1) a “stress-tested” profitability dashboard by product and channel, and (2) a three-step operational contingency plan (inventory buffering, contract repricing triggers, and rapid certification fast-tracks).
What you will find in the full report and data pack
- Detailed bottom-up and top-down revenue models by segment and end-user with downloadable CSVs and scenario toggles.
- Supplier scorecards with manufacturing footprints, capacity data, IP ownership maps, and recent contract wins.
- Practical checklists for CE/pRAVE and EN certification processes with estimated timelines and typical failure modes.
- Procurement templates, cost-pass-through models, and CAPEX sizing tools calibrated to the 2026 budgeting cycle.
- An appendix of primary interviews with façade contractors, OEM specifiers, and procurement heads that underpin our demand assumptions and price elasticity estimates.
PW Consulting’s Worldwide SGP Interlayer Films Market report is intentionally structured as a decision-guidance product: it shows where value will accrue, where risks are concentrated, and where execution must be flawless. We deliberately limit publishable granular segmentation in this press summary to preserve the commercial integrity of the underlying dataset — the full segmentation (by application, end-user, and region), company-level revenue detail, and purchaser-level pricing matrices are available on the report page.
Next steps for executives and investors
- Download the full dataset and model to run bespoke stress tests against your 2026 budget scenarios.
- Schedule a strategy workshop with PW Consulting to align procurement, product, and M&A priorities to the forecasted pathways.
- Use our supplier scorecards to inform shortlists for offtake partnerships, and to set realistic timelines for certification-dependent rollouts.
For decision-makers preparing 2026 budgets, the question is no longer whether SGP interlayers matter — they do. The relevant choices are tactical: which contracts to lock, where to invest in capability, and how to price and package offerings to capture system-level value. PW Consulting’s report converts those tactical choices into a prioritized roadmap, balancing speed, compliance, and margin protection. To access the full report, the interactive model, or to arrange a briefing, visit PW Consulting’s Worldwide SGP Interlayer Films Market report page.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Foam Insulation Sheet Market Set to Expand at a 5.85% CAGR Through 2032
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief: Worldwide Phenolic Foam Insulation Sheet Market — Executive Trailer for 2026 Decision-Making
PW Consulting’s new market study on the Worldwide Phenolic Foam Insulation Sheet Market (base year 2025; forecast period 2026–2032) delivers an actionable, executive-grade intelligence package designed to shape commercial, operational, and M&A decisions in 2026. The market is on a clear upward trajectory: our proprietary model pegs the global market at approximately USD 1,590.8 Million in 2025 and projects sustained growth through the forecast window at a compound annual growth rate (CAGR) of 5.85%. By 2032 the market is anticipated to exceed USD 2.3 billion, subject to the macro and input-price scenarios outlined below.
Worldwide Phenolic Foam Insulation Sheet Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivotal year where regulatory tightening, construction recovery patterns, and raw-material volatility converge—creating both upside opportunities and downside risks for phenolic foam suppliers, fabricators, and downstream specifiers.
Worldwide Phenolic Foam Insulation Sheet Market -
Decision focus: Boards of directors, heads of supply chain, and product chiefs need a concise, executable playbook to align capacity, pricing, and product development with near-term demand and margin pressures.
Worldwide Phenolic Foam Insulation Sheet Market -
Actionability: The study translates market projections into scenario-driven playbooks—covering procurement hedging, manufacturing footprint optimization, product differentiation, and M&A target prioritization.
Market snapshot and trajectory
Phenolic foam sheets remain a specialty insulation solution prized for high thermal performance and fire resistance. The market recovered through 2023–2025 following uneven construction cycles and is expected to grow at a mid-single-digit CAGR through 2032 under our central forecast. This trajectory reflects persistent demand for higher-efficiency building envelopes, tightening fire-safety requirements in commercial and multi-family construction, and continuing uptake in industrial and HVAC applications where thin-profile, high-R-value materials deliver clear lifecycle cost benefits.
Key market dynamics that will shape 2026 choices
-
Regulatory push on emissions and safety: Standards and regulations—ranging from California CARB ATCM and EU REACH to EN 14314 and performance classifications such as Euroclass and ASTM metrics—are driving demand for low-emission formulations and documented compliance. These requirements are increasingly non-negotiable in tender specifications and public-sector procurement.
-
Raw-material cost and volatility: Phenolic resin is the dominant feedstock for phenolic foam production. Recent benchmark observations signal meaningful price levels and episodic volatility—examples include measured prices in key markets through 2025–2026—creating a direct and material impact on production cost curves. This is a live sensitivity in our margin-modeling and should be a primary factor in procurement and pricing strategies.
-
Fire safety as a value driver: Phenolic foam’s ability to meet stringent fire classifications sustains its competitive advantage in applications where safety-critical performance is required. Manufacturers that can couple low emissions with demonstrable fire performance are positioned to capture specification-driven premiums.
-
Sustainability innovation: Suppliers and resin producers are accelerating bio-based and lower-embodied-carbon resin initiatives. Notable industry moves—such as new bio-based phenolic resin introductions—signal a pathway for suppliers to credibly address sustainability mandates without sacrificing performance.
-
Concentration and fragmentation: The market shows a mix of large global manufacturers and regional fabricators. Our concentration metrics indicate material market shares at the top end of the supplier spectrum, with the top three players accounting for a meaningful share of the market and the top five nearing half of total market value—conditions that have important implications for competitive strategy, pricing power, and consolidation opportunities.
Supply chain and input-strategy imperatives
Phenolic resin pricing and availability are the single largest cost levers in sheet economics. Our report provides a granular procurement playbook: multi-sourcing scenarios, contractual hedging approaches (index-linked and fixed-price blends), regional sourcing trade-offs, and resin-substitute R&D sensitivity. We model the P&L impact of discrete resin-price shocks on EBITDA margins for representative plant profiles and recommend prioritized mitigation steps for producers and large specifiers.
Competitive landscape — who matters and why
Understanding competitor positioning is essential for 2026 strategy. Our vendor intelligence and benchmarking cover global leaders, regional champions, and specialized fabricators. Highlights include:
-
Kingspan Insulation (Ireland) — recognized for high-performance closed-cell phenolic boards with strong fire and thermal credentials and an established brand in Europe.
-
Jinan Shengquan Group (China) — a major Chinese producer with an expanding international footprint across construction and industrial markets.
-
Asahi Kasei (Japan) — chemical industry incumbent with phenolic solutions targeting fire-critical and high-performance applications.
-
Unilin / Xtratherm (Ireland) — offers rigid phenolic boards positioned for energy-efficient building envelopes.
-
LG Hausys (South Korea), Sekisui Chemical (Japan) — notable for product lines emphasizing fire safety and durability.
-
Regional fabricators and niche players — such as General Insulation Company (USA), MW Insulation (UK), Resolco (USA), and several China- and UAE-based manufacturers — who provide custom shapes, pre-finished panels, and local servicing advantages.
-
Resin suppliers such as Prefere Resins and major chemical firms are becoming strategic partners as bio-based resin launches and supply agreements gain importance.
For strategy teams, the report’s company profiles, capability maps, and sourcing matrices translate competitor footprints into tangible implications for pricing, specification capture, and partnership opportunities.
Strategic playbook — recommended moves for 2026
-
Secure resin supply through blended contracts: Combine short-term index-linked purchases with multi-year strategic take-or-pay agreements to smooth cost volatility.
-
Prioritize low-emission, high-fire-performance SKUs for public and institutional tenders; build compliance documentation into sales kits.
-
Invest selectively in capacity where lead times and logistics offer a clear customer-service advantage; otherwise, consider tolling or local fabrication partnerships to minimize capex risk.
-
Differentiate on systems, not merely sheets: offer integrated solutions (pre-insulated panels, fabricated duct sections, certified installation services) to capture value beyond raw cubic meters.
-
Pursue bolt-on M&A to accelerate capability (e.g., local fabrication, fire-testing labs, resin-secured JV), prioritizing targets that materially improve gross margins or open high-barrier specification channels.
-
Embed sustainability claims with third-party verification: leverage bio-based resin offerings and life-cycle assessment (LCA) data to win environmentally weighted specifications.
-
Use scenario-driven pricing: adopt tiered contracts that pass through resin-cost drivers while protecting volume commitment incentives.
What PW Consulting’s report contains (practical elements)
-
Executive summary and investment thesis tied to 2026 strategic windows.
-
Proprietary demand model (2020–2032) with central, upside, and downside scenarios, and sensitivity analyses to resin pricing, construction activity, and regulatory shifts.
-
Supply-side cost models including plant-level economics and margin sensitivity to feedstock movements.
-
Regulatory and standards matrix (CARB, REACH, EN 14314, Euroclass, ASTM), with compliance checklists and product development implications.
-
Competitive benchmarking and capability maps, including vendor profiles, strategic positioning, and contact points for due-diligence prioritization.
-
M&A target scoring tool and playbook for integration, capex savings, and route-to-market acceleration.
-
Commercial templates—procurement negotiation frameworks, resin hedging term-sheets, and specification-driven sales kits.
How to use this intelligence in 2026
Boards and executive teams should treat the study as both a strategic roadmap and an operations-to-market toolkit. Use the scenario outputs to set 2026 capex envelopes, to stress-test supplier contracts under probable resin-price paths, and to prioritize product SKUs for markets where fire- and emissions-compliance commands a premium. Business development and BD&I teams can use the vendor benchmarking and compliance templates to accelerate specification capture and reduce bid-to-win cycles.
Final note — a trailer, not the full film
This brief is intended to surface the strategic contours and the immediate decisions that matter in 2026. The full PW Consulting report contains the detailed tables, model outputs, and confidential benchmarking that underpin the recommendations above—information we reserve for report subscribers and licensed clients. For teams preparing strategic plans, procurement agreements, or transaction diligence in 2026, the full dataset and our interactive scenario model are essential to translate this guidance into executable programs.
To access detailed forecasts, sensitivity models, and the comprehensive competitive dossiers that accompany this brief, please visit the PW Consulting report page or contact our industry advisory team to arrange a briefing and demo of the forecasting model.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Foam Insulation Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Skin Care App Market Poised to Reach USD 876.93 Million by 2032, Backed by a 10.02% CAGR
By pmarketresearch, 2026-07-15
Worldwide Skin Care App Market: Strategic Playbook for 2026 — PW Consulting Market Release
As companies prepare budgets, partnerships and product roadmaps for 2026, the Worldwide Skin Care App Market is transitioning from experimental pilots to commercial-grade platforms that carry material revenue and regulatory risk. PW Consulting’s latest market intelligence — anchored on a 2025 base year and a 2026–2032 forecast horizon — provides the decision-grade context that executives in beauty, healthcare, tech and investment need to prioritize initiatives this calendar year.
Worldwide Skin Care App Market
Executive snapshot
PW Consulting’s analysis shows the global skin care app market at USD 450.0 Million (revenue unit: Million) in 2025, with a robust projected trajectory to reach approximately USD 876.9 Million by 2032. Our model indicates a compound annual growth rate (CAGR) of 10.02% across the forecast period (2026–2032). This momentum is driven by improved AI capabilities, broader consumer adoption of mobile-first skincare routines, and accelerating strategic activity from incumbent beauty and consumer-health players.
Worldwide Skin Care App Market
Why this matters for 2026 planning
- Prioritization of product investment: With double-digit CAGR and near-term revenue expansion, companies must decide whether to build proprietary AI experiences, partner with specialized platforms, or acquire capabilities to accelerate time-to-market.
- Regulatory compliance as a strategic constraint: Regulators in major jurisdictions are increasingly treating skin diagnostic features as high-risk technology. Compliance strategy is no longer a back-office task — it is a go/no-go commercial consideration that affects roadmap, go-to-market timing and legal exposure.
- Cost and operating model implications: Talent and compute are material line items. Our benchmarking indicates labor and cloud GPU costs account for meaningful percentages of development and OpEx; firms must optimize architecture and sourcing to preserve margin as products scale.
Report value: what PW Consulting delivers to decision makers
This new report is designed as a practical playbook for leaders who must make clear yes/no choices before the 2026 budgeting cycle closes. Highlights include:
Worldwide Skin Care App Market
- Validated market sizing and scenario-driven forecasts (2026–2032) that reconcile demand signals, platform monetization assumptions and regulatory overlays.
- Path-to-value frameworks for three strategic options: build (internal R&D and data strategy), buy (M&A and minority investments), and partner (SDKs, white-label, and channel agreements).
- Detailed cost models that isolate labor, cloud compute and data management line items so CFOs can evaluate incremental spend for feature roadmaps and commercialization ramps.
- Regulatory readiness checklists that map product claims to jurisdictional conformity requirements, including the practical steps to de-risk medical-like assertions and clinical-style validation claims.
- A deal playbook for corporate development and VCs, including valuation sensitivities, earnout structures, and integration pitfalls specific to AI-driven consumer health apps.
Competitive landscape — who’s shaping the market and why it matters
The market sits at the intersection of beauty brands, pharmaceutically anchored skincare lines, and specialist AI developers. Our competitive analysis focuses on leaders who combine brand reach, technical IP and distribution muscle — and on narrowly focused innovators that continue to move the performance frontier.
- Perfect Corp. (Hong Kong) — Developer of the YouCam suite, Perfect Corp. continues to push AI fidelity with features such as 3D facial mapping and hyper-localized diagnostics. Their strategy demonstrates how a platform-first approach can scale across makeup, skincare and retail activation, turning consumer selfies into commerce triggers.
- L’Oréal (Clichy, France) — Through its acquisition strategy and in-house investments, L’Oréal has embedded AI diagnostics into product discovery and personalized routines. Recent expansions to predict UV damage and broaden product compatibility illustrate the commercial payoff of integrating diagnostic insights with product catalogs.
- La Roche-Posay (L’Oréal Group) — A brand-led app strategy that links clinical heritage to digital triage and routine personalization, enabling direct product integration and a potential pathway to loyalty-first monetization.
- Neutrogena — Johnson & Johnson (Skillman, NJ, USA) — By integrating app metrics with broader health ecosystems (for example, through mobile health platforms), Neutrogena’s direction showcases the value of interoperability for longitudinal skin health tracking.
- Procter & Gamble (Cincinnati, OH, USA) — The Olay digital advisory and similar efforts leverage large product portfolios and customer data to convert diagnostic insights into tailored purchase recommendations across mainstream skincare lines.
- Cetaphil (Galderma) and specialty apps — Brands rooted in dermatological credibility are using digital triage to drive trust and conversion among consumers with sensitive skin or medical-adjacent needs.
- Vertical specialists (e.g., Think Dirty, Skinive) — Niche players continue to drive feature-led value: ingredient transparency and lesion detection are examples where single-purpose apps capture user attention and create potential acquisition targets.
Recent industry moves underscore the intensity of strategic activity: enhanced AI skin analysis with 3D mapping (Product update, October 2025), extension of diagnostic features into new markets and product catalogs (mid-2025), and integrations with health ecosystems (early 2025). These developments highlight that differentiation increasingly rests on data quality, model transparency and distribution partnerships.
Regulatory and operational dynamics you cannot ignore
- Regulation: The EU AI Act categorizes skin diagnostic apps under high-risk AI systems, which triggers conformity assessment regimes and creates significant pre-market obligations. Separately, US regulators have explicitly warned against consumer-directed AI apps that make unvalidated medical claims. These developments change development timelines and legal exposure.
- Data sovereignty and privacy: Biometric and facial-data regulations in several large markets mandate localized handling and explicit consent mechanics; compliance choices materially affect cloud architecture and partner selection.
- Cost structure realities: Talent costs in developed markets (e.g., average annual compensation for mobile/AI engineers) and cloud GPU billing for model training and inference are non-trivial. Our report quantifies these inputs and shows scenarios where per-user economics only become attractive after careful optimization of model complexity and inference strategy.
Strategic imperatives for 2026 — five high-conviction recommendations
- Adopt a compliance-first product roadmap: Treat regulatory classification as a gating factor for feature rollouts. Build a two-track validation plan — consumer-facing features vs. medically-adjacent diagnostics — with separate QA and legal sign-offs.
- Optimize for modular AI: Design models and pipelines that separate heavy-weight training from light-weight on-device inference. This reduces recurring cloud GPU costs and improves latency/privacy tradeoffs for global rolls.
- Pursue selective partnerships, not broad bet-the-company M&A: For companies lacking core AI talent, SDK partnerships and minority investments into niche specialists can accelerate capability without full integration risk.
- Monetize via a hybrid model: Combine free diagnostic features to drive acquisition with paid personalization and fulfillment (e.g., subscription routines, commerce flows, clinician consultations) to capture higher lifetime value per user.
- Use pilots as regulatory and technical proofs-of-concept: Pilot in constrained jurisdictions or cohorts to validate model performance, clinical claims and user experience before scaling into regulated markets.
How the full PW Consulting report supports execution
Our full report delivers the layer of detail that turns strategic direction into executable plans: proprietary topline forecasts, scenario-tested financial models, vendor and partner matrices, checklists for regulatory conformity, sample legal language for disclaimers, cost-per-user modeling templates, and an M&A playbook tailored to valuation drivers in this space. To preserve commercial exclusivity and to encourage the diligence required for high-stakes decisions, select granular segmentation and company-specific revenue breakdowns are available only in the full report and the accompanying data appendices.
Implications for investors and corporate development
Investors should expect asymmetric opportunities: the fastest returns will come from companies that can combine differentiated models with defensible data assets and clear regulatory strategies. For corporates, the pathway to scale favors a portfolio approach — incubate proprietary experiences for core brands while using partnerships to fill capability gaps. Our M&A scenarios quantify when tuck-ins make sense versus when full acquisitions are required to capture strategic IP.
Next steps — using the analysis in your 2026 planning
- Executive briefings: PW Consulting offers tailored sessions to map the report’s findings into your firm’s P&L and product roadmap.
- Workshops: We run collaborative sessions to convert the playbook into a 90-day execution plan with owner assignments and milestone-based compliance gates.
- Custom diligence: For prospective investments or partnerships, we supply deep-dive technical, regulatory and commercial diligence bundles.
Conclusion: The skin care app market is maturing fast. Our forecasted near-doubling of market size through 2032 at a 10.02% CAGR signals commercial opportunity, but the path to monetization is constrained by regulatory, cost and data governance realities. Companies that align product, legal and go-to-market strategies in 2026 — and that use partnerships judiciously to plug capability gaps — will set the performance baseline for the next wave of competition.
For full access to the granular segmentation, company-level revenue estimates, scenario models and the executable playbooks referenced above, consult the complete PW Consulting Worldwide Skin Care App Market report and data appendices. Our team is available to translate these insights into a tailored strategic plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com