

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Phenolic Foam Insulation Sheet Market Set to Expand at a 5.85% CAGR Through 2032

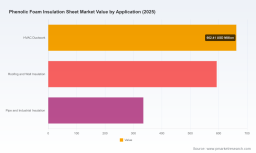
PW Consulting Strategic Brief: Worldwide Phenolic Foam Insulation Sheet Market — Executive Trailer for 2026 Decision-Making
PW Consulting’s new market study on the Worldwide Phenolic Foam Insulation Sheet Market (base year 2025; forecast period 2026–2032) delivers an actionable, executive-grade intelligence package designed to shape commercial, operational, and M&A decisions in 2026. The market is on a clear upward trajectory: our proprietary model pegs the global market at approximately USD 1,590.8 Million in 2025 and projects sustained growth through the forecast window at a compound annual growth rate (CAGR) of 5.85%. By 2032 the market is anticipated to exceed USD 2.3 billion, subject to the macro and input-price scenarios outlined below.
Worldwide Phenolic Foam Insulation Sheet Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivotal year where regulatory tightening, construction recovery patterns, and raw-material volatility converge—creating both upside opportunities and downside risks for phenolic foam suppliers, fabricators, and downstream specifiers.
Worldwide Phenolic Foam Insulation Sheet Market -
Decision focus: Boards of directors, heads of supply chain, and product chiefs need a concise, executable playbook to align capacity, pricing, and product development with near-term demand and margin pressures.
Worldwide Phenolic Foam Insulation Sheet Market -
Actionability: The study translates market projections into scenario-driven playbooks—covering procurement hedging, manufacturing footprint optimization, product differentiation, and M&A target prioritization.
Market snapshot and trajectory
Phenolic foam sheets remain a specialty insulation solution prized for high thermal performance and fire resistance. The market recovered through 2023–2025 following uneven construction cycles and is expected to grow at a mid-single-digit CAGR through 2032 under our central forecast. This trajectory reflects persistent demand for higher-efficiency building envelopes, tightening fire-safety requirements in commercial and multi-family construction, and continuing uptake in industrial and HVAC applications where thin-profile, high-R-value materials deliver clear lifecycle cost benefits.
Key market dynamics that will shape 2026 choices
-
Regulatory push on emissions and safety: Standards and regulations—ranging from California CARB ATCM and EU REACH to EN 14314 and performance classifications such as Euroclass and ASTM metrics—are driving demand for low-emission formulations and documented compliance. These requirements are increasingly non-negotiable in tender specifications and public-sector procurement.
-
Raw-material cost and volatility: Phenolic resin is the dominant feedstock for phenolic foam production. Recent benchmark observations signal meaningful price levels and episodic volatility—examples include measured prices in key markets through 2025–2026—creating a direct and material impact on production cost curves. This is a live sensitivity in our margin-modeling and should be a primary factor in procurement and pricing strategies.
-
Fire safety as a value driver: Phenolic foam’s ability to meet stringent fire classifications sustains its competitive advantage in applications where safety-critical performance is required. Manufacturers that can couple low emissions with demonstrable fire performance are positioned to capture specification-driven premiums.
-
Sustainability innovation: Suppliers and resin producers are accelerating bio-based and lower-embodied-carbon resin initiatives. Notable industry moves—such as new bio-based phenolic resin introductions—signal a pathway for suppliers to credibly address sustainability mandates without sacrificing performance.
-
Concentration and fragmentation: The market shows a mix of large global manufacturers and regional fabricators. Our concentration metrics indicate material market shares at the top end of the supplier spectrum, with the top three players accounting for a meaningful share of the market and the top five nearing half of total market value—conditions that have important implications for competitive strategy, pricing power, and consolidation opportunities.
Supply chain and input-strategy imperatives
Phenolic resin pricing and availability are the single largest cost levers in sheet economics. Our report provides a granular procurement playbook: multi-sourcing scenarios, contractual hedging approaches (index-linked and fixed-price blends), regional sourcing trade-offs, and resin-substitute R&D sensitivity. We model the P&L impact of discrete resin-price shocks on EBITDA margins for representative plant profiles and recommend prioritized mitigation steps for producers and large specifiers.
Competitive landscape — who matters and why
Understanding competitor positioning is essential for 2026 strategy. Our vendor intelligence and benchmarking cover global leaders, regional champions, and specialized fabricators. Highlights include:
-
Kingspan Insulation (Ireland) — recognized for high-performance closed-cell phenolic boards with strong fire and thermal credentials and an established brand in Europe.
-
Jinan Shengquan Group (China) — a major Chinese producer with an expanding international footprint across construction and industrial markets.
-
Asahi Kasei (Japan) — chemical industry incumbent with phenolic solutions targeting fire-critical and high-performance applications.
-
Unilin / Xtratherm (Ireland) — offers rigid phenolic boards positioned for energy-efficient building envelopes.
-
LG Hausys (South Korea), Sekisui Chemical (Japan) — notable for product lines emphasizing fire safety and durability.
-
Regional fabricators and niche players — such as General Insulation Company (USA), MW Insulation (UK), Resolco (USA), and several China- and UAE-based manufacturers — who provide custom shapes, pre-finished panels, and local servicing advantages.
-
Resin suppliers such as Prefere Resins and major chemical firms are becoming strategic partners as bio-based resin launches and supply agreements gain importance.
For strategy teams, the report’s company profiles, capability maps, and sourcing matrices translate competitor footprints into tangible implications for pricing, specification capture, and partnership opportunities.
Strategic playbook — recommended moves for 2026
-
Secure resin supply through blended contracts: Combine short-term index-linked purchases with multi-year strategic take-or-pay agreements to smooth cost volatility.
-
Prioritize low-emission, high-fire-performance SKUs for public and institutional tenders; build compliance documentation into sales kits.
-
Invest selectively in capacity where lead times and logistics offer a clear customer-service advantage; otherwise, consider tolling or local fabrication partnerships to minimize capex risk.
-
Differentiate on systems, not merely sheets: offer integrated solutions (pre-insulated panels, fabricated duct sections, certified installation services) to capture value beyond raw cubic meters.
-
Pursue bolt-on M&A to accelerate capability (e.g., local fabrication, fire-testing labs, resin-secured JV), prioritizing targets that materially improve gross margins or open high-barrier specification channels.
-
Embed sustainability claims with third-party verification: leverage bio-based resin offerings and life-cycle assessment (LCA) data to win environmentally weighted specifications.
-
Use scenario-driven pricing: adopt tiered contracts that pass through resin-cost drivers while protecting volume commitment incentives.
What PW Consulting’s report contains (practical elements)
-
Executive summary and investment thesis tied to 2026 strategic windows.
-
Proprietary demand model (2020–2032) with central, upside, and downside scenarios, and sensitivity analyses to resin pricing, construction activity, and regulatory shifts.
-
Supply-side cost models including plant-level economics and margin sensitivity to feedstock movements.
-
Regulatory and standards matrix (CARB, REACH, EN 14314, Euroclass, ASTM), with compliance checklists and product development implications.
-
Competitive benchmarking and capability maps, including vendor profiles, strategic positioning, and contact points for due-diligence prioritization.
-
M&A target scoring tool and playbook for integration, capex savings, and route-to-market acceleration.
-
Commercial templates—procurement negotiation frameworks, resin hedging term-sheets, and specification-driven sales kits.
How to use this intelligence in 2026
Boards and executive teams should treat the study as both a strategic roadmap and an operations-to-market toolkit. Use the scenario outputs to set 2026 capex envelopes, to stress-test supplier contracts under probable resin-price paths, and to prioritize product SKUs for markets where fire- and emissions-compliance commands a premium. Business development and BD&I teams can use the vendor benchmarking and compliance templates to accelerate specification capture and reduce bid-to-win cycles.
Final note — a trailer, not the full film
This brief is intended to surface the strategic contours and the immediate decisions that matter in 2026. The full PW Consulting report contains the detailed tables, model outputs, and confidential benchmarking that underpin the recommendations above—information we reserve for report subscribers and licensed clients. For teams preparing strategic plans, procurement agreements, or transaction diligence in 2026, the full dataset and our interactive scenario model are essential to translate this guidance into executable programs.
To access detailed forecasts, sensitivity models, and the comprehensive competitive dossiers that accompany this brief, please visit the PW Consulting report page or contact our industry advisory team to arrange a briefing and demo of the forecasting model.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Foam Insulation Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com