

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
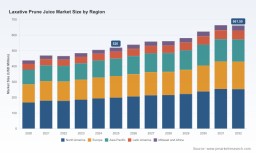
PW Consulting: Laxative Prune Juice Market to Reach USD 661.6 Million by 2032 at 3.5% CAGR; North America Leads with USD 199.4M (Base Year 2025)

Laxative Prune Juice Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As consumer demand for functional beverages continues to mature, prune juice—long positioned at the intersection of natural remedies and mainstream beverage retail—has reasserted itself as a niche category with broader strategic significance. PW Consulting’s latest market study distills the operational intelligence, scenario analysis, and deal-level insight that senior executives, category chiefs, and investors need to act decisively in 2026. This brief highlights the report’s strategic value while reserving detailed segmentation tables and proprietary datasets for the full report.
Laxative Prune Juice Market
Market snapshot: what the headline numbers mean for strategy
The global laxative prune juice market is at an inflection point. Our base-year assessment for 2025 pegs the market at approximately USD 520 million, and our forecast through 2032 anticipates steady expansion to roughly USD 662 million—implying a compound annual growth rate (CAGR) of about 3.5% over the forecast horizon. Those headline metrics capture the combined effects of product repositioning (from legacy medicinal use toward everyday functional beverage), modest premiumization, and channel migration toward instant-purchase formats and e-commerce.
Laxative Prune Juice Market
Two simple takeaways flow from these numbers. First, growth is meaningful but measured—sufficient to justify targeted investments, not blanket expansion. Second, the category’s structural profile (moderate concentration, see below) creates both scale advantages for incumbent processors and opportunity windows for fast-moving challengers that can exploit product innovation or supply-chain agility.
Laxative Prune Juice Market
Why 2026 is a decision year
- Supply normalization and contract renegotiation: Companies should use 2026 to renegotiate multi-year supply agreements and to build optionality into concentrate sourcing as crop cycles normalize after recent volatility.
- Product and channel differentiation: 2026 will determine which players can transition prune juice from a functional niche into a repeat-purchase mainstream item via product reformulation (taste, sugar reduction, functional fortification) and channel-first packaging.
- Regulatory & trade positioning: Recent tariff and inspection developments mean market access opportunities for exporters and new compliance responsibilities for importers—both require immediate operational planning.
- M&A and capacity decisions: With moderate market concentration and surging interest in natural functional beverages, 2026 is optimal for targeted bolt-on acquisitions and capacity investments that secure upstream supply and margin capture.
What our full report contains (actionable modules)
- Market sizing & high-resolution forecasting: multi-scenario top-down and bottom-up forecasts to 2032 with sensitivity testing by price, channel, and supply shock assumptions.
- Practical go-to-market playbooks: store-level assortment recommendations, online conversion levers, shelf pricing tactics, and promotional mechanics tailored to retail partners and direct-to-consumer models.
- Supply-demand balancing and raw-material risk maps: crop-cycle monitoring, concentrate availability scenarios, and contingency plans for low-yield years.
- Cost-to-serve and margin modeling: SKU-level contribution analysis, ingredient cost pass-through frameworks, and dynamic pricing templates.
- Regulatory & trade dossier: compliance checklist and playbooks for importers and exporters, including inspection and grading standards and tariff monitoring.
- Competitive intelligence & M&A playbook: company dossiers, valuation benchmarks, and acquisition target screening using proprietary deal filters.
- ESG and operational transformation blueprints: energy-efficiency capex models, carbon abatement pathways, and supplier engagement programs that reduce scope-3 risk.
Competitive landscape — who matters and why
The category is shaped by a mix of vertically integrated cooperatives, multinational food companies, and specialist concentrate suppliers. Market concentration is moderate: the top three firms account for roughly a third of the market while the top five approach mid‑single‑digit additional share—meaning leaders enjoy scale benefits but cannot afford complacency.
- Sunsweet Growers Inc. — A grower-owned cooperative with vertical integration from orchard to shelf. Sunsweet’s 2025–2026 activity (a new PlumGood product, facility upgrades focused on energy and GHG intensity, and crop/supply updates) signals a dual strategy: defend core retail channels while investing in sustainability and taste-led innovation. Their supply-side communications and capital investments make them a natural anchor partner for strategic alliances around traceable concentrate sourcing.
- Del Monte Foods, Dole, Welch’s, Ocean Spray — These household brands leverage broad retail distribution and brand equity to maintain visibility in the category. Their advantages are scale in trade spend, retailer relationships, and cross-category merchandising; their constraints are legacy cost structures and slower product development cycles relative to niche innovators.
- Sun-Maid, Valley View Foods, California Prune Packing — These players emphasize ingredient supply, concentrate manufacturing, and bespoke formulations for industrial clients. They’re critical nodes for companies seeking custom specifications or private-label supply.
- Rauch Fruchtsäfte — As a European concentrate specialist, Rauch illustrates the importance of geographic diversification in sourcing and the role of ingredient suppliers in supporting new product extensions across geographies.
Supply-side dynamics and raw-material signals
Raw-material risk is the single most important strategic variable. Industry reporting for the 2025/26 cycle estimates global prune production around 193,000 metric tons—approximately 6% lower than the prior cycle—with California’s 2025 crop estimated in the mid‑tens of thousands of metric tons and described as good quality. At the same time, producer price indices for plums and fresh prunes are consistent with elevated nominal price baselines seen in the last two seasons.
Implications: companies that lock in supply under favorable terms in 2026 will gain cost and quality advantages. Conversely, those lacking upstream exposure should plan for both margin compression in low-yield scenarios and increased buyer competition for concentrate. Our report provides hedging and contract designs (index-linked, volumetric carve-outs, quality tiers) that senior procurement teams can deploy immediately.
Trade policy and regulatory context
Two examples illustrate the operational impact of policy: the UK government’s suspension (and extension) of an import tariff that had previously affected certain suppliers is a near-term demand stimulus for exporters who can move product without a cost shock. On the compliance side, U.S. import requirements for prunes (inspection and grading under federal standards) remain a binding operational constraint for inbound flows. These developments mean exporters and importers must align commercial plans with customs, inspection, and trade teams to avoid execution risk.
2026 strategic playbook — priorities for leadership
- Secure diversified concentrate pathways: negotiate multi-sourced contracts with flexible take-or-pay and quality-tier clauses; develop contingency capacity with regional concentrate suppliers.
- Invest in taste and format innovation: reformulate to reduce perceived sweetness and add functional benefits (fiber-forward positioning, low‑sugar options, convenient single-serve formats).
- Leverage channel economics: prioritize e-commerce and subscription models where lifetime value is higher; use retailer category captains to test premium SKUs and cross-promotions.
- Prepare for measured M&A: target bolt-ons that provide upstream control (concentrates, drying capacity) or channel access (digital-first brands and D2C capabilities).
- Operationalize sustainability: replicate proven facility upgrades that reduce energy intensity; build measurable Scope 3 programs tied to orchard-level practices to de-risk procurement.
- Embed regulatory monitoring: operational teams should incorporate trade and inspection triggers into supply planning to exploit short-term tariff windows or to mitigate inspection-led delays.
How PW Consulting helps
PW Consulting partners with executive teams to translate these insights into executable plans: from transactional diligence on potential acquisitions to the deployment of a category-specific pricing engine and to operational redesigns that capture cost and carbon efficiency. Our deliverables include scenario-ready financial models, commercial playbooks tailored to retailer partners, supplier negotiation scripts, and a bespoke risk dashboard integrating weather, crop, and price indicators.
This briefing is a strategic preview. For commercial teams, procurement leads, and dealmakers seeking to operationalize a 2026 plan, the full Laxative Prune Juice Market report contains granular segmentation, regional flows, channel breakdowns, SKU-level pricing intelligence, and the proprietary datasets underpinning our forecasts. Access to the full dataset and downloadable templates is available on our report page.
PW Consulting — actionable intelligence, confidential datasets, and hands‑on implementation support to turn category insight into competitive advantage. For the complete analysis, including the detailed segmentation and model outputs that inform 2026 decision-making, please consult the full report.
For detailed analysis of this topic, please visit the official page: Laxative Prune Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com