

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide SGP Interlayer Films Market Reaches USD 306.69 Million in 2025, Forecast to Grow at an 8.0% CAGR

Worldwide SGP Interlayer Films Market — Strategic Imperatives for 2026
As capital allocation, procurement, and product roadmaps are reset for 2026, the SentryGlas (SGP) interlayer films market has reached an inflection point. PW Consulting’s new Worldwide SGP Interlayer Films Market report (base year 2025; forecast period 2026–2032) combines market-scale forecasting, competitive intelligence, and transaction-grade playbooks to convert market complexity into executable choices. Our model shows the global market expanding at a compound annual growth rate (CAGR) of 8.0% through 2032, rising from a 2025 baseline to a materially larger market by 2032 — a trajectory that transforms strategy from defensive cost management to proactive capability building.
Worldwide SGP Interlayer Films Market
Why this market matters for boardroom decisions in 2026
- Market momentum and timing: After steady growth through the early 2020s, aggregate market value accelerates in the 2026 planning horizon. The step-change in demand dynamics — driven by structural-glazing adoption, higher performance safety glazing, and transport glazing spec upgrades — creates windows for first-mover advantage in supply, product premiumization, and integrated system sales.
- Concentration and bargaining power: The SGP interlayer market exhibits high concentration at the top. A small number of global leaders capture the lion’s share of commercial volumes and intellectual property, which reshapes supplier negotiations, certification leadership, and aftermarket services playbooks.
- Input-cost and regulatory pressure: Feedstock volatility is no longer edge-case noise. Spot pricing for PVB and ionomer feedstocks rose materially in late 2024 — spot levels increased by roughly 8% to around USD 2.45/kg — compressing margins for unconsolidated laminators and raising the value of long-term offtake agreements and hedging approaches. At the same time, regulatory and standards updates (notably EU Construction Products Regulation pRAVE testing requirements and REACH restrictions on certain plasticizers) are tightening the compliance bar for load-bearing and overhead applications.
- Trade policy friction: Sustained tariff overlays in core markets (for example, Section 301 duties in the U.S. on some imported interlayers) materially change landed cost calculations and near-term reshoring economics. Strategic sourcing decisions in 2026 must therefore account for effective rates, not headline supplier quotes.
What this report delivers — practical, transaction-ready intelligence
PW Consulting’s report is constructed to move teams from signal to action. It is not an academic survey — it is a practitioner’s toolkit that includes:
Worldwide SGP Interlayer Films Market
- Top-down market-size and forecast model (2020–2032) with scenario runs (base, upside, downside) and sensitivity matrices that translate demand swings into revenue, utilization, and unit-margin impacts for producers and laminators.
- Competitive-scorecard and value-chain maps showing IP positions, product tiers (standard PVB vs. high-performance ionoplasts), and commercialization pathways for premium SGP offerings.
- Supply-chain risk heatmaps and procurement playbooks, including recommended hedging approaches, contract templates for fixed-price volumes, and a supplier qualification checklist tailored to load-bearing and seismic glazing specifications.
- Certification and compliance navigator that links testing regimes (CE/pRAVE, EN 16613, REACH) to product development checklists, lab-capacity needs, and certification timelines aligned to construction cycles.
- Commercial playbooks — pricing ladders, margin engineering, product-bundle constructs (pre-laminated panels, system warranties), and channel strategies for interfacing with architectural glaziers, façade integrators, and transport OEMs.
- M&A and capacity-planning guidance: target screening criteria calibrated to CR3/CR5 market concentration, expected payback under base forecasts, and post-merger integration templates focused on IP, quality control, and regulatory consolidation.
Competitive landscape — who to watch and how to position
The market’s top actors combine differentiated IP with manufacturing scale, distribution networks, and certification leadership. PW Consulting’s qualitative and quantitative benchmarking finds that incumbent leaders maintain both technology and go-to-market advantages, but there are tactical openings for regional processors and vertical integrators.
Worldwide SGP Interlayer Films Market
- Trosifol (Wiesbaden, Germany) — As the commercial face of SentryGlas offerings, the company’s emphasis on high-strength ionoplast films and recent product innovation (for example, decorative colored SGP variants launched in late 2024) underscores the premiumization pathway: customers will pay for demonstrable UV stability and aesthetic differentiation. For competitors and partners, the strategic implication is clear — compete on systems and service, not just commodity price.
- Kuraray (Tokyo, Japan) — Kuraray’s manufacturing depth and certification progress (notably EN 16613 accreditation updates in mid-2024) position it as the strategic supplier for high-clarity, ultra-thick ionoplasts used in blast-, seismic-, and overhead-glazing applications. Buyers seeking to de-risk large projects should prioritize suppliers with certified supply and documented performance in these use cases.
- Everlam (Halen, Belgium) — Recent capacity expansions in Europe signal that regional laminators can scale to meet project-driven spikes in structural glass demand. For investors, Everlam-style plays highlight the attractive returns on targeted capacity investments when paired with long-term offtake agreements.
- Glastrotech (Dallas, TX, USA) — As a regional processor and authorized distributor, Glastrotech exemplifies the business model of localized pre-lamination and value-added panel supply for North American façade markets. The strategic takeaway: controlling last-mile value-adds (pre-laminated panels, warranty services) is a viable route to margin capture even where upstream resin IP is concentrated.
Collectively, the recent product launches, certifications, and capacity moves we observed in 2024–2025 are not isolated events — they form a pattern of incumbents fortifying supplier locks, while processors and regional players chase integration and service differentiation.
Strategic implications and recommended 90–180 day actions
- Procurement and cost protection — Execute multi-year supply agreements with price collars or indexation clauses to limit exposure to feedstock swings. Prioritize dual-sourcing for high-value ionoplast grades and seek co-investment clauses for capacity expansion in exchange for preferred volume.
- Certification-first product development — Align R&D roadmaps with mandatory testing timelines (CE/pRAVE and EN standards). For customers in regulated markets, certification latency is commercial risk; lead-time must be explicitly modeled into go-to-market timelines.
- Commercial differentiation — Bundle product warranties, facade integration services, and design-assist capabilities to capture higher ASPs (average selling prices) and to create switching costs versus commodity PVB supplies.
- Regional trade strategy — Model landed cost under different tariff and logistical scenarios (including Section 301 overlays). Where duty inefficiencies are persistent, evaluate near-market lamination or toll-processing investments to reduce landed cost and delivery risk.
- M&A and capacity plays — Prioritize bolt-ons that offer immediate access to certification labs, lamination capacity, or proprietary surface treatments over greenfield builds if near-term demand is uncertain but strategic positioning is required.
- Commercial operations — Implement project-level pricing models for large façade contracts, factoring in warranty exposure, certification costs, and cascading margin risks from raw material spikes.
Scenario planning — volatility is the constant
Our scenario suite projects that, even under conservative demand pathways, the structural-glazing-led portion of the market will expand materially by late-decade. That said, margin compressions can be severe in short windows when feedstock prices spike or when tariffs re-apply. Boards should insist on two deliverables for 2026: (1) a “stress-tested” profitability dashboard by product and channel, and (2) a three-step operational contingency plan (inventory buffering, contract repricing triggers, and rapid certification fast-tracks).
What you will find in the full report and data pack
- Detailed bottom-up and top-down revenue models by segment and end-user with downloadable CSVs and scenario toggles.
- Supplier scorecards with manufacturing footprints, capacity data, IP ownership maps, and recent contract wins.
- Practical checklists for CE/pRAVE and EN certification processes with estimated timelines and typical failure modes.
- Procurement templates, cost-pass-through models, and CAPEX sizing tools calibrated to the 2026 budgeting cycle.
- An appendix of primary interviews with façade contractors, OEM specifiers, and procurement heads that underpin our demand assumptions and price elasticity estimates.
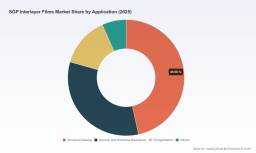
PW Consulting’s Worldwide SGP Interlayer Films Market report is intentionally structured as a decision-guidance product: it shows where value will accrue, where risks are concentrated, and where execution must be flawless. We deliberately limit publishable granular segmentation in this press summary to preserve the commercial integrity of the underlying dataset — the full segmentation (by application, end-user, and region), company-level revenue detail, and purchaser-level pricing matrices are available on the report page.
Next steps for executives and investors
- Download the full dataset and model to run bespoke stress tests against your 2026 budget scenarios.
- Schedule a strategy workshop with PW Consulting to align procurement, product, and M&A priorities to the forecasted pathways.
- Use our supplier scorecards to inform shortlists for offtake partnerships, and to set realistic timelines for certification-dependent rollouts.
For decision-makers preparing 2026 budgets, the question is no longer whether SGP interlayers matter — they do. The relevant choices are tactical: which contracts to lock, where to invest in capability, and how to price and package offerings to capture system-level value. PW Consulting’s report converts those tactical choices into a prioritized roadmap, balancing speed, compliance, and margin protection. To access the full report, the interactive model, or to arrange a briefing, visit PW Consulting’s Worldwide SGP Interlayer Films Market report page.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com