

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Solenoid Reversing Valve Market Set to Grow at a 5.24% CAGR

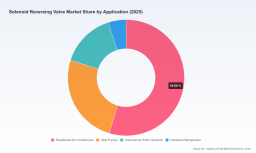
Worldwide Solenoid Reversing Valve Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s newest market study, WorldWide Solenoid Reversing Valve Market (base year 2025; historical 2020–2025; forecast 2026–2032), is designed as a decision‑grade briefing for executives, product leaders, supply‑chain managers and investors preparing strategies for 2026 and beyond. The global market reached approximately USD 962.5 million in 2025. Under the central scenario contained in our report, the market is projected to expand at a 5.24% compound annual growth rate (CAGR) over 2026–2032, surpassing USD 1.37 billion by 2032. This preview summarizes the strategic implications embedded in the full study and highlights where leadership teams must act during 2026 to capture durable value.
Worldwide Solenoid Reversing Valve Market
Why 2026 Is a Pivotal Inflection Point
-
Energy transition momentum: Accelerated adoption of heat pump technologies and tighter low‑GWP refrigerant mandates are changing valve design and qualification requirements. Reversing valves — especially four‑way designs used for seasonal switching — are now a critical system component, not a commodity accessory.
Worldwide Solenoid Reversing Valve Market -
Regulatory and safety thresholds: Product certification and pressure ratings are moving to the forefront of procurement decisions. Compliance with global recognition standards (UL and equivalents) and compatibility with higher maximum operating pressures for common HFC refrigerants are table stakes for access to mainstream HVAC and heat pump programs.
Worldwide Solenoid Reversing Valve Market -
Supply‑side volatility: Raw material cost swings are a material margin lever for valve producers. Our intelligence captured spot HRC (hot‑rolled coil) benchmarks across 2025–early‑2026 that demonstrate notable volatility, creating immediate procurement and hedging priorities for manufacturers and OEMs.
-
Concentration and consolidation pressure: The market exhibits high concentration among the top suppliers, shaping bargaining power, M&A incentives and partnership strategies in the near term.
What the Report Delivers — Practical, Transaction‑Ready Intelligence
PW Consulting’s report is structured around pragmatic use cases for commercial teams and C‑suite leaders. It is not an academic compilation; it is an implementation playbook. Core deliverables include:
-
Validated market sizing and a transparent forecasting model for 2026–2032 (scenario engines included) so you can stress‑test CAPEX and production plans against downside and upside cases.
-
Technology and product archetypes mapped to buyer needs (e.g., valve actuation methods, sealing materials and refrigerant compatibility) with engineering implications for NPI roadmaps.
-
Cost and margin benchmarking — Bill‑of‑material and conversion cost templates that enable quick margin sensitivity analyses under alternative steel and component price regimes.
-
Competitive landscaping with capability matrices and strategic positioning for the leading suppliers, plus an annotated timeline of recent product launches and go‑to‑market moves.
-
Supply‑chain vulnerability map and mitigation strategies: dual‑sourcing, contract hedges, and nearshoring implications for 2026 tactical plans.
-
M&A and partnership playbooks: prioritization criteria, integration checklists and value capture mechanisms for bolt‑on acquisitions or JV structures.
-
Commercial templates — pricing ladders, OEM qualification checklists and aftermarket service propositions designed to lift ASPs and extend lifetime value.
Key, Data‑Driven Takeaways for Corporate Strategy
-
Product portfolio focus: The ramp of high‑efficiency heat pumps increases commercial tailwinds for robust four‑way valve platforms that are refrigerant‑agnostic and can meet higher pressure requirements. Prioritize R&D investment where materials compatibility and cycle reliability intersect with regulatory conformity.
-
Cost management is non‑negotiable: Given recent volatility in steel markets and other input streams, manufacturers should deploy margin protection strategies now — negotiated long‑term purchase agreements, inventory optimization and selective vertical integration for high‑impact components.
-
Certification as a commercial lever: Achieving and advertising recognized approvals (e.g., UL recognition and validated max operating pressures) reduces friction in OEM qualification processes and expedites access to tier‑1 HVAC programs.
-
Aftermarket and services are underleveraged: Service contracts and reliability guarantees can differentiate offerings in a market with significant concentration among incumbents — build predictive maintenance and warranty models into commercial proposals.
-
Scenario planning for supply disruptions: The report’s forecast envelopes include upside and downside pathways that reflect potential raw material shocks and trade disruptions; procurement and production planners must operationalize trigger points for capacity and inventory adjustments.
Competitive Landscape — Profiles and Strategic Implications
The market is concentrated among a handful of strategic players; the combined market share of the top three and top five vendors underscores strong incumbency effects. PW Consulting’s CR metrics show a high three‑firm concentration and even greater dominance within a five‑firm cohort, implying limited room for low‑capital entrants to scale without partnership or niche specialization.
-
Sanhua Holding Group (Hangzhou, China) — A leading global supplier of four‑way reversing valves for HVAC and heat pumps, Sanhua’s SHF family and newly released stainless steel SHF‑G series position it strongly in programs prioritizing corrosion resistance and compatibility with both synthetic and natural refrigerants. Recent product launches and trade show activity in late‑2025/early‑2026 demonstrate an aggressive product cycle cadence and marketing push into intelligent controls.
-
Danfoss (Nordborg, Denmark) — A broad refrigeration and air‑conditioning component supplier whose solenoid portfolio and reversing valve solutions are deeply integrated into OEM platforms. Its global OEM relationships make it an essential partner for firms seeking scale in integrated systems.
-
Parker Hannifin & Bosch Rexroth — Both bring depth in hydraulic and pneumatic directional control valves and supply chains oriented to heavy industrial and mobile machinery. Their strengths lie in robustness and customization for non‑HVAC industrial applications.
-
Robertshaw & Wilspec — Specialized players focused on heat pump valve mechanisms and geothermal solutions respectively; they are differentiated by application know‑how and installation channel intimacy.
-
DunAn, SMC, ASCO (Emerson), Shandong Yikaide — These vendors reflect a mix of large OEM breadth, pneumatics expertise and regional manufacturing scale. Each occupies a specific niche in the ecosystem from automated pneumatic systems to price‑competitive valve bodies.
Recent developments — notably Sanhua’s SHF‑G stainless steel release and its RACC exhibition participation — illustrate how incumbents are accelerating product innovation and market visibility to capture wave demand from heat pump electrification programs.
Actionable Priorities for 2026 (Short‑Term) and 2026–2032 (Medium‑Term)
-
Immediate (0–12 months): Lock down supply of critical metals through contracts or localized sourcing, accelerate UL and equivalent certifications for core valve families, and pilot co‑development agreements with tier‑1 OEMs to secure early‑design wins in 2026 model years.
-
Near term (12–36 months): Invest in material and seal technologies that reduce lifetime leakage and broaden refrigerant compatibility; launch a services offering that monetizes installation validation and predictive maintenance; evaluate M&A targets to close capability gaps quickly.
-
Medium term (36–72 months): Build modular valve platforms that can be parametrically tuned for global regulatory envelopes, and pursue strategic partnerships that embed intelligent actuation and diagnostics into system architectures.
How to Use This Preview
This communication is intended as a strategic preview that demonstrates the depth and actionable orientation of PW Consulting’s full report. We intentionally withhold detailed regional and application segmentation tables and the full financial model in this release to preserve the integrity of our premium data package and encourage direct engagement. The complete study includes granular segmentation, downloadable modeling templates, supplier scorecards and executive‑ready slide material designed to accelerate your 2026 planning cycle.
Next Steps — For Executives Ready to Move
-
Procurement and operations leaders: request the model to run your own raw‑material sensitivity scenarios against the five forecast paths enclosed in the full report.
-
Product and R&D executives: engage with our product archetype mapping to accelerate specification updates required for low‑GWP refrigerant compatibility and higher operating pressures.
-
Strategy and corporate development teams: use our M&A playbook and vendor scorecards to prioritize targets and structure earn‑outs that preserve engineering know‑how during integration.
PW Consulting’s WorldWide Solenoid Reversing Valve Market report is a tactical resource for leaders who must convert 2026 market dynamics into executable plans. For immediate access to the full dataset, scenario models and supplier scorecards referenced above, please visit the full report page on PW Consulting’s website or contact our industry practice lead for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com