

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts Worldwide High‑Performance IMU Market to Reach USD 5,532.1 Million by 2032, Growing at a 5.72% CAGR
By pmarketresearch, 2026-07-15
Worldwide High-performance IMU Market — Strategic Insight for 2026 Decision-Makers
PW Consulting’s new market brief on the Worldwide High-performance Inertial Measurement Unit (IMU) market provides an executive-grade synthesis designed to inform executive decisions in 2026. Using 2025 as the report’s base year and a forecast window of 2026–2032, our analysis projects the market to expand from an estimated USD 3,750.0 Million in 2025 to approximately USD 5,532.1 Million by 2032, representing a compound annual growth rate (CAGR) of 5.72%. This release functions as a strategic “trailer”: it presents rigorous, decision-ready insight while preserving the granular breakdowns and proprietary segment detail that clients access through the full report.
Worldwide High-performance IMU Market
What the report delivers — practical, transaction-ready intelligence
-
Proven forecasting methodology: transparent assumptions, sensitivity analyses, and scenario outputs for near-term (2026) and medium-term (through 2032) capital planning.
Worldwide High-performance IMU Market -
Market sizing and topline growth drivers: demand drivers across defense, navigation, marine, industrial and space segments, and the macro forces shaping adoption curves.
Worldwide High-performance IMU Market -
Technology landscape and roadmap: comparative assessment of MEMS, FOG, RLG, HRG and hybrid approaches; maturity curves and innovation inflection points.
-
Vendor benchmarking and capability matrices: strategic positioning, product differentiators, scale advantages, and go-to-market models for the leading suppliers.
-
Regulatory and compliance playbook: export-control implications (ITAR, EAR, USML), certification pathways (MIL-STD et al.), and commercial/defense segmentation strategies.
-
Procurement & integration toolkit: technical checklists, RFx templates, TCO models, environmental/qualification criteria, and supplier-risk scoring.
-
M&A and partnership screening: acquisition target shortlist, valuation multipliers, integration risk factors, and playbooks for cross-border consolidation given export controls.
-
Stress-tested scenarios: alternative demand trajectories (accelerated autonomy adoption, defense modernization waves, GNSS-denied contingencies) and recommended tactical responses for each.
Why this matters for 2026 decisions
-
Capital allocation clarity: With an objectively modeled growth trajectory to 2032 and multiple sensitivity runs, boards and investment committees can prioritize R&D and production scale investments against quantifiable upside and downside cases for 2026–2028.
-
Procurement timing: Our short-term overlays identify windows when component lead-times, certification cycles, and production ramp constraints converge — enabling procurement teams to lock in suppliers or hedge via secondary sources.
-
Technology prioritization: MEMS-based innovation is compressing the performance differential to higher-cost architectures. The report outlines where incremental sensor performance justifies premium pricing versus where cost optimization should be the priority.
-
Regulatory-informed market access: Compliance constraints materially affect go-to-market choices. The brief highlights control regimes and provides a compliance decision-tree for choosing between ITAR-governed and ITAR-free product strategies.
Competitive landscape — what incumbents and challengers are doing
The market remains moderately concentrated, with the three largest firms capturing a meaningful leadership position (CR3 ≈ 42.5%) and the top five approaching majority share (CR5 ≈ 58.8%). That structure creates a dual-track competitive environment: scale players defend mission-critical, high-margin aerospace and defense contracts, while agile specialists and MEMS innovators drive disruption at the tactical and commercial edges.
-
Honeywell International Inc. (USA): executing a product-led strategy to migrate MEMS devices into near-navigation-grade territory. Recent product introductions emphasize reduced SWaP and endurance in GNSS-denied environments — a clear signal that legacy vendors are prioritizing MEMS performance improvements to protect adjacent market share.
-
Northrop Grumman Corporation (USA): maintains a differentiated focus on space- and defense-grade FOG and HRG architectures, leveraging long-term stability and qualification pedigree. The company’s portfolio is positioned to serve missions where endurance and drift characteristics are non-negotiable.
-
Safran Electronics & Defense (France, incl. Sensonor): combining MEMS and quartz-based solutions to address tactical defense and industrial automation, with an emphasis on MIL-grade qualification and environmental robustness.
-
Thales Group (France): continuing investment in resilient navigation systems for contested and denied environments, signaling strategic emphasis on integrated solutions rather than component-only sales.
-
Analog Devices Inc. (USA), VectorNav (USA), SBG Systems (France), KVH (USA), Silicon Sensing (UK), Collins Aerospace (RTX, USA), TDK Tronics (France), Advanced Navigation (Australia), and others: together they form an ecosystem of specialization — from precision MEMS to FOG, supply-scale manufacturers, and ITAR-free challengers.
Recent industry developments underscore these dynamics: Honeywell’s HG3900 launch (June 2025) signals tactical-grade MEMS encroachment; Thales and SBG launched resilient and compass-capable MEMS products in 2025, broadening non-GNSS-reliant capabilities; Silicon Sensing reported a major production milestone (October 2025), underscoring scale; and consolidation activity, including VIAVI’s acquisition of Inertial Labs (December 2024), demonstrates active strategic buy-side interest.
Technology trends and the primary hardware bottlenecks
-
Performance convergence: MEMS innovations are closing gaps in bias instability and noise floors, enabling lower-cost tactical solutions to perform closer to mid-tier systems. However, high-stability FOG/RLG/HRG architectures retain advantages in long-duration, high-drift-sensitivity applications.
-
Persistent bottlenecks: the industry’s principal hardware challenges remain achieving low bias instability and scale-factor stability in compact packages subject to vibration and wide temperature ranges. Overcoming these limits drives premium pricing for validated solutions.
-
System-level differentiation: sensor fusion, on-board processing, and algorithmic compensation are becoming as important as raw sensor performance. Firms that combine sensor hardware with validated fusion software create higher switching costs for customers.
Regulatory, standards and supply-chain implications
Export controls and standards materially shape strategy. High-performance IMUs with military-specific modifications are frequently captured by ITAR and may be subject to USML controls; the U.S. Bureau of Industry and Security also applies EAR controls to certain dual-use inertial technologies. Concurrently, MIL-STD and environmental qualifications remain mandatory in many defense procurements. These realities mean that market access, partnership models, and M&A must be evaluated through a compliance-first lens.
-
Strategic sourcing: dual-sourcing and ITAR-free product lines can mitigate geopolitical and licensing risk and enable broader commercial expansion.
-
Localization: for firms seeking to serve defense buyers in constrained jurisdictions, localized production and qualification pathways reduce friction but require early capital planning.
-
Standards investment: certification timelines (vibration, temperature, shock) can add months to product introduction — factor these into 2026 program schedules.
Practical recommendations for executives in 2026
-
Prioritize modularity: invest in sensor-agnostic integration layers and on-board fusion to extend product longevity as sensor generations evolve.
-
Balance portfolio exposure: maintain a mix of ITAR-governed capabilities for strategic defense contracts and ITAR-free lines for commercial/global growth.
-
Lock in supply where qualification is the barrier: secure long-lead components and partner with high-volume producers to avoid ramp delays.
-
Use M&A selectively: with market concentration meaningful among top players, bolt-on acquisitions can rapidly add capability, but must be screened for regulatory complexity.
-
Embed compliance early: integrate export-control impact assessments into product design and go-to-market planning to avoid costly retrofits.
How to use PW Consulting’s full report
The brief you are reading encapsulates the strategic judgments and headline forecasts critical for 2026 decision-making. The full Worldwide High-performance IMU Market report expands on these themes with proprietary segmentation, granular region- and application-level models, supplier scorecards, supplier financial overlays, and downloadable templates for procurement and compliance. For teams evaluating capital deployment, supplier selection, or M&A in 2026, the full dataset and appendices provide the operational detail required to execute with confidence.
PW Consulting’s market intelligence combines validated quantitative modeling with practitioner-led insights to reduce execution risk. If you are preparing budgets, drafting technical RFPs, or screening acquisition targets for 2026, the report is structured to accelerate decisions while preserving the due diligence rigour your stakeholders expect.
Next steps
-
Visit our report page to access the full dataset, vendor scorecards, and downloadable procurement templates (full access required for segmentation-level data and appendices).
-
Engage PW Consulting for a tailored workshop: we map the market forecast to your product roadmaps, procurement calendars, and compliance posture to create a 100-day action plan.
In an industry where sensor performance, production scale, and regulatory posture intersect to determine winning strategies, the right intelligence can be the difference between a timely product launch and a multi-quarter delay. Our 2026-focused guidance equips boards, product leaders, and procurement teams with the context and tactical levers to act decisively — while the full report supplies the granular evidence base to execute.
For detailed analysis of this topic, please visit the official page: Worldwide High-performance IMU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tributyl Citrate Market Poised for Robust Growth at 5.12% CAGR, New Insight Report Finds
By pmarketresearch, 2026-07-15
Worldwide Tributyl Citrate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global supply chains recalibrate and regulator-driven substitution accelerates, tributyl citrate (TBC) has emerged from niche status to a strategic raw material for manufacturers of flexible polymers, food-contact items, and medical-grade devices. PW Consulting’s latest market research — anchored on a 2025 base year and a historical review from 2020–2025 with forecasts through 2026–2032 — offers a forward-looking, actionable framework that senior executives and procurement leads must use to shape decisions in 2026.
Worldwide Tributyl Citrate Market
Market at a Glance: What the Numbers Tell Us
Our market sizing shows an evolving trajectory: after material volatility in the early 2020s, the global tributyl citrate market reached roughly USD 742 million in 2025. Under our base case modeling, the market is expected to expand at a compound annual growth rate (CAGR) of 5.12% over the 2026–2032 forecast window, approaching about USD 1.05 billion by 2032. That growth is neither linear nor uniform — it is shaped by regulatory shifts, raw material cycles, and structural demand changes across food, medical, and specialty polymer applications.
Worldwide Tributyl Citrate Market
Importantly, market structure analysis indicates a moderate level of concentration: a handful of global players hold disproportionate influence over technology, supply reliability, and regulatory compliance credentials. This creates both vulnerabilities and opportunities for market entrants, incumbent producers, and downstream buyers.
Worldwide Tributyl Citrate Market
Why This Report Matters for 2026 Decision-Making
- Timing: 2026 is the inflection year where regulatory substitution trends — particularly in response to phthalate restrictions — transition from early adoption to mainstream procurement requirements in several geographies. Companies that proactively align formulations and supply agreements in 2026 will capture premium access to food-contact and medical OEM programs.
- Risk Management: Our scenario-driven forecasts quantify exposure to raw material and logistics shocks, enabling procurement and operations teams to cost-effectively hedge supply and secure capacity commitments.
- M&A and CapEx Prioritization: With moderate market concentration and predictable mid-single-digit growth, targeted acquisitions and capacity expansions can deliver outsized returns if aligned to the right end-markets and regulatory certifications.
Key Strategic Dynamics Shaping 2026
- Regulatory Substitution: Policy measures restricting certain phthalates have materially increased interest in non-phthalate plasticizers. This regulatory momentum is particularly relevant for food-contact and medical applications, where certification and documentation are procurement gatekeepers.
- Raw Material Volatility: Citric acid — a primary upstream feedstock — experienced notable price spikes due to supply disruptions in late 2024. Our sensitivity modeling shows that feedstock cost pass-through and formulation optimization will be central to gross-margin preservation for producers in 2026.
- Trade & Tariff Pressures: Recent trade measures affecting imports from select origins have introduced short-term arbitrage and longer-term reshoring considerations for buyers, prompting re-evaluation of sourcing strategies and inventory buffers.
- Logistics Risk Premiums: Elevated chemical shipping rates and route disruptions have increased total landed costs. Multimodal routing and regional sourcing become economic imperatives for companies with thin margin tolerance.
- Sustainability & Bio-attribution: Demand for bio-based variants has moved beyond marketing rhetoric into procurement specifications. Firms able to document feedstock provenance and lifecycle benefits will enjoy differentiated access to certain OEMs and public tenders.
Competitive Landscape — Who Moves the Market
The competitive tableau combines multinational specialty chemical houses, regional industrial producers, and laboratory-grade suppliers. Leading firms bring differentiated capabilities:
- Large specialty producers have invested in scale and regulatory compliance to support global food-contact and medical applications. Capacity expansions and certification updates by these players have tightened premium-grade availability and raised the bar for new entrants.
- Regional manufacturers, particularly in high-volume growth corridors, offer competitive cost structures and export-ready volumes that influence spot-market dynamics and short-term pricing pressure.
- Laboratory and pharma-focused suppliers provide high-purity, USP/NF grades and play a vital role in R&D and niche medical applications where documentation and batch traceability matter most.
Recent corporate actions underscore these distinctions: notable capacity increases to meet non-phthalate demand, third-party certifications confirming food-contact compliance, and launches of bio-attributed grades that target sustainability-conscious buyers. Collectively, these moves suggest incumbents are shifting from volume playbooks to a blended strategy of compliance-led differentiation and targeted capacity investments.
Operational and Commercial Implications
- Procurement: Short-term spot exposure is rising. We recommend a mix of multi-year supply contracts for certified grades and tactical spot purchases for industrial applications to balance cost and availability.
- R&D and Product Strategy: Formulation roadmaps must prioritize substitution strategies where regulatory pressure is strongest, and embed bio-attribution where customer willingness to pay is validated.
- Supply Chain Resilience: Firms should stress-test portfolio profitability against a 10–20% citric-acid price shock and a 10–15% freight-rate increase. Scenario planning in 2026 will determine inventory policy and contingency routing investments for 2027–2028.
- Commercial Go-to-Market: Sales teams must pivot toward solution selling (regulatory dossiers, compliance documentation, supply continuity guarantees) rather than commodity-price negotiation when engaging food and medical OEMs.
What PW Consulting’s Report Delivers (Practical, Executable)
Our research package is engineered for direct use by strategy, procurement, and business development teams. Highlights include:
- Market-sizing and forecast model (2020–2032) with embedded scenario toggles to simulate regulatory, feedstock, and logistics shocks.
- Price-sensitivity and margin-impact dashboards that quantify how upstream cost changes translate to producer and buyer P&L — enabling rapid renegotiation playbooks.
- Competitive benchmarking and supplier scorecards covering technology, capacity, certifications, and geographic risk exposure — designed to support shortlists for sourcing and M&A diligence.
- Regulatory playbook and documentation templates tailored to food-contact and medical device procurement teams, including compliance checklists and audit-ready supplier qualification artifacts.
- M&A screening tool that identifies candidate targets by capability gaps, regulatory status, and scale economics — together with a transaction playbook and indicative valuation ranges for typical deal structures.
- Commercial strategies and segmented go-to-market approaches without revealing proprietary segmentation metrics in this preview — designed to swiftly convert technical compliance into revenue uplift.
Action Recommendations: 90-Day and 18-Month Horizon
- 90-Day: Run a cross-functional stress test on contracts for certified grades; prioritize supply agreements with suppliers that have proven certification trajectories and documented capacity expansion commitments. Lock in conditional contracts for high-priority OEM programs.
- 6–18 Months: Execute targeted supplier development (co-investment or offtake-linked financing) in regions that reduce tariff exposure and logistics complexity. Accelerate formulation approvals with top-tier customers by pre-submitting compliance dossiers and joint validation plans.
- M&A Window: Evaluate tuck-in opportunities in 2026 to secure regulatory-compliant capacity and shorten time-to-market for premium grades. Prioritize targets with validated documentation, traceable feedstock, and stable customer relationships.
Regulatory & Sustainability Watchlist
- Regulatory momentum away from certain plasticizers is creating durable demand for alternatives. Firms that secure early certifications and maintain audit-ready dossiers in 2026 capture disproportionate wallet share with conservative procurement teams.
- Bio-attributed product launches are shifting buyer expectations: sustainability claims must be verifiable and supported by lifecycle analysis to avoid commercial pushback.
- Trade measures and tariffs have altered the economics of global arbitrage; local production and regional supply chains are now strategic levers rather than cost centers alone.
How to Use This Preview — And Where to Go Next
This preview is intentionally strategic and integrative. It highlights the decisive variables that will govern success in the tributyl citrate value chain in 2026, but it does not disclose the granular segmentation and proprietary datasets that underpin our full-market intelligence. For procurement teams, R&D leads, and corporate strategists seeking the detailed models, supplier scorecards, and playbooks described above, the full PW Consulting report provides the calibrated inputs required to operationalize the strategies outlined here.
Accessing the complete report will provide: the full scenario model files, supplier-level benchmarking with certification timelines, a prioritized M&A target list (with supporting financials), and turnkey templates for supplier qualification and regulatory submission.
Final Thought
Tributyl citrate has evolved from an alternative plasticizer into a strategic commodity at the intersection of regulation, sustainability, and supply-chain resilience. The period beginning in 2026 will differentiate winners from laggards: organizations that integrate rigorous risk modeling, certify supply for regulated end-markets, and align commercial strategy to verified sustainability claims will capture the most value. PW Consulting’s Worldwide Tributyl Citrate Market report equips leaders with the insight and tools to make those decisions confidently — while the granular data necessary to execute those moves remains available in the full report.
To obtain the complete dataset, scenario models, and supplier playbooks, please visit our research portal (full access details and ordering information are available there).
For detailed analysis of this topic, please visit the official page: Worldwide Tributyl Citrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti‑Blue Ray Myopia Lenses Market to Expand at 8.15% CAGR — from USD 4,285.5 Million in 2025 to USD 7,416.29 Million by 2032, Led by Asia Pacific (USD 1,820.6M)
By pmarketresearch, 2026-07-15
Worldwide Anti-blue Ray Myopia Lenses Market: Strategic Insights for 2026 Decision-Makers
Executive snapshot
As the anti-blue ray myopia lenses market approaches a pivotal inflection, PW Consulting’s latest market study provides a practical, decision-ready map for executives planning 2026 strategies. Our analysis shows the global market reached a significant scale by the 2025 base year and is projected to grow at a compound annual growth rate (CAGR) of 8.15% across the 2026–2032 forecast horizon. This trajectory reflects the combined impact of clinical validation of myopia-slowing spectacle technologies, rising digital device use among children and adolescents, and faster adoption of integrated blue-light mitigation across lens portfolios.
Worldwide Anti-blue Ray Myopia Lenses Market
Why this report matters for 2026 planning
- Timing of regulatory and clinical signals is creating windows of opportunity for premium product launches, channel reconfiguration, and strategic partnerships.
- Market expansion at an >8% CAGR means capacity planning, supply-chain resilience and margin management should move from tactical to strategic planning in 2026.
- Increasing product convergence—myopia management optics combined with anti-blue light functions—requires coordinated R&D, IP strategy and clinical affairs investments to protect differentiation.
What the report delivers (practical, implementable content)
PW Consulting designed this report as an executable playbook for commercial, R&D and corporate development leaders. Key components include:
Worldwide Anti-blue Ray Myopia Lenses Market
- Proven forecasting model calibrated to five years of historical data (2020–2025) and stress-tested under three adoption scenarios for 2026–2032.
- Go-to-market frameworks tailored to different company archetypes (incumbent lens manufacturers, optical retailers, clinic chains, and digital-first e-commerce players).
- Pricing and margin models that translate material, coating and value-add features into SKU-level profitability guidance—with worked examples for trade-offs between premium coatings and high-index substrates.
- Regulatory roadmap templates and clinical evidence strategies to support market authorization and reimbursement conversations in major jurisdictions.
- Supply-chain diagnostics and mitigation playbooks covering resin suppliers, coating lines, and contract manufacturing capacity, with supplier-risk heatmaps and near-term contingency plans.
- A compact M&A and partner-screening matrix identifying target profiles, integration risks and value-creation levers for roll-up or bolt-on acquisitions.
- Executive scorecards and KPIs for 2026 implementation—covering adoption, channel performance, ASP trajectory, customer retention and R&D throughput.
Market dynamics and structural drivers
Several persistent forces are shaping the competitive landscape. First, clinical validation of spectacle-based myopia management has moved from academic debate into commercial reality, creating durable demand for spectacle-based solutions that can credibly claim to slow progression in pediatric populations. Second, the ubiquitous growth in screen time among children and adolescents is increasing demand for lenses that combine optical myopia-management functions with blue-light mitigation to address both progression risk and digital eye strain. Third, technology choices—substrate absorption vs. coating-based blue-light solutions and the selection of high-index resins—are now central to value propositions rather than peripheral manufacturing decisions.
Worldwide Anti-blue Ray Myopia Lenses Market
Competitive landscape: who matters and why
The market is neither a pure commodity nor a highly fragmented cottage industry; it displays clear leader positions alongside nimble regional specialists. Market concentration metrics indicate a meaningful presence of top-tier players, with the top three and top five firms together accounting for material shares of supply—an important consideration for suppliers, buyers and investors planning 2026 moves.
Key players profiled in the report include global incumbents and regional manufacturers with distinct strategic postures:
- EssilorLuxottica (Essilor): With Stellest lenses and the H.A.L.T. platform, Essilor now occupies a leading position in clinically validated spectacle myopia management. Recent regulatory milestones have strengthened its commercial credibility and provide a benchmark for competitors’ evidence strategies.
- HOYA Vision Care: HOYA’s MiYOSMART product family, enhanced by recent coating innovations (STX), highlights how incremental but high-impact product engineering—durable hydrophobic coatings, long-life AR and integrated blue-light filtering—can sustain differentiation in mature product lines.
- ZEISS: With MyoCare and myopia management optics, ZEISS is focused on optical design sophistication and professional channel partnerships, emphasizing optometrist- and ophthalmologist-led adoption paths.
- Regional manufacturers (China-based and other OEMs): A number of vertically integrated regional players supply a wide spectrum of anti-blue and myopia-control lenses, combining product breadth with local regulatory registration and cost-competitive manufacturing; these firms are critical partners for scale and serve as both competitors and suppliers to global chains.
- Optics specialists and tier-2 brands (Nikon, Shamir, and others): These players compete on precision optics, coating chemistry and channel relationships, often pursuing selective premiumization strategies or targeting niche clinical use-cases.
Recent developments that will shape 2026 strategies
- Regulatory validation: The U.S. FDA’s marketing authorization for Essilor Stellest as a spectacle lens indicated to slow pediatric myopia progression represents a watershed moment. This accelerates adoption among practitioners and sets new evidentiary expectations for alternatives.
- Product enhancements: HOYA’s rollout of the Smooth Touch Xtreme (STX) coating on its MiYOSMART line signals the importance of durability and surface performance as commercial differentiators—especially for child- and school-age users.
- Platform evolution: Continued product-line investments by major incumbents (e.g., Essilor’s platform expansions) underscore a move toward integrated platforms combining optics, coatings and service offerings (e.g., clinician training, digital adherence tools).
Technology and materials outlook
Commercial anti-blue ray myopia lenses today leverage two principal technical approaches: intrinsic substrate absorption (e.g., UV420 absorption factors built into lens monomers) and multi-layer coating systems applied to high-index resins. Each approach has trade-offs: substrate absorption provides persistent filtering without changing surface coatings but can complicate tinting and photochromic performance; coatings enable tunable spectral profiles and higher surface performance but raise durability and cost considerations. High-index resin grades and innovations in AR/hydrophobic coatings are the levers that will determine product ASPs and margin pools in 2026.
Channel and consumer behavior implications
Digital-native consumer behaviors, particularly among families with school-age children, are driving hybrid route-to-market strategies. Clinician endorsement remains a critical trust cue for myopia management products, while e-commerce channels accelerate reach and pricing transparency. For manufacturers and retailers alike, the 2026 priority is to design omnichannel strategies that preserve clinical routing for diagnosis and evidence-based fitting while enabling direct-to-consumer education and replenishment models for lens upgrades.
Supply chain, manufacturing, and risk management
Meeting growing demand without margin erosion requires a two-pronged approach: (1) tactical capacity upgrades in high-value production lines—coating cells, high-index polymer molding and precision surfacing—and (2) strategic partnerships with regional contract manufacturers to hedge geopolitical and logistics risk. Inventory strategies will need to balance SKU proliferation (due to combinations of index, coating and myopia designs) against working capital constraints.
M&A, partnership and go-to-market playbook for 2026
Our deal-screening logic in the report helps identify targets that can rapidly expand technical capability (coating, substrate technology), channel access (clinic chains, optical retail partnerships), or geographic footprint. Successful value creation will hinge on integration of clinical data assets and the ability to accelerate commercialization through clinician outreach programs and digital adherence tools.
Scenarios and KPIs
The report includes three plausible market scenarios—conservative adoption, baseline growth and accelerated diffusion—each paired with tailored KPIs (adoption velocity, clinician conversion rates, ASP evolution, channel mix metrics, and R&D time-to-evidence). These scenarios enable executive teams to stress-test capital allocation, production planning and sales incentives for 2026.
How senior executives should use this report in 2026
- CEOs & Boards: Use the scenario-based capital allocation guidance to set 2026 capex priorities (coating lines, clinical trials budget, digital platforms).
- Commercial leaders: Implement the go-to-market playbooks to sequence clinician engagement, retail promotions and digital campaigns that protect ASPs while maximizing penetration.
- R&D & Regulatory: Adopt the regulatory roadmap and evidence-generation templates to compress approval timelines in target jurisdictions and to design post-market surveillance strategies.
- M&A & Strategy teams: Apply the partner-screening matrix and integration playbook to prioritize acquisitions that fill capability gaps within a 9–18 month execution window.
What we intentionally withhold here—and why
This briefing is designed as a “trailer”: it demonstrates our analytical depth and practical orientation while intentionally omitting certain granular segmentation and price-matrix tables to preserve the report’s role as a commercial intelligence product. Detailed regional and application splits, SKU-level price elasticity matrices, and the full set of supplier-level forecasts are reserved for the full report and interactive dashboards available from PW Consulting.
Next steps
For executives who must convert 2026 uncertainty into advantage, our full Worldwide Anti-blue Ray Myopia Lenses Market report delivers the data, models and playbooks required to act confidently. The full deliverable includes downloadable scenario models, executive dashboards, supplier heatmaps and a confidential M&A target list—tools designed for fast, operational decision-making.
Contact PW Consulting to request access to the full report, schedule a tailored strategy workshop, or commission custom scenario modeling for your organization’s portfolio decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-blue Ray Myopia Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Gas & Liquid Argon Market Poised for 5.42% CAGR to 2032 as Asia Pacific Surges
By pmarketresearch, 2026-07-15
Worldwide Gas and Liquid Argon Market: Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market research — Worldwide Gas and Liquid Argon Market (Base Year: 2025) — provides a focused, decision‑grade vantage point for executives and investors preparing strategy in 2026. The global argon market has grown from roughly USD 3,324.5 Million in 2020 to USD 4,333.45 Million in 2025 and is forecast to expand to approximately USD 6,270.4 Million by 2032, implying a compounded annual growth rate of 5.42% across the 2026–2032 forecast window. Market concentration underscores a moderately consolidated landscape, with the top three suppliers controlling just over half of global supply and the top five approaching seven in ten dollars of revenue — a structural reality that shapes pricing, capacity investment and M&A calculus.
Worldwide Gas and Liquid Argon Market
Why this report matters for 2026
-
Timing: 2026 is the inflection year for many producers and end-users. Near‑term capital deployments (new ASUs, cryogenic logistics upgrades) announced in 2023–2024 arrive online and materially change local availability and pricing dynamics in target markets.
Worldwide Gas and Liquid Argon Market -
Risk management: Energy cost volatility and evolving transport regulations introduce execution risk into both production and distribution models. Understand where margin squeeze is likely, and where contract renegotiation or hedging is critical.
Worldwide Gas and Liquid Argon Market -
Opportunity capture: Semiconductor, advanced manufacturing and certain energy applications continue to be outsized demand drivers. Identifying the right product grade, delivery mode and commercial model in 2026 will determine who captures premium demand through 2032.
Key demand and supply dynamics shaping 2026 strategy
-
Energy intensity and cost structure: Argon is produced via energy‑intensive air separation; electricity represents the dominant portion of production costs (industry estimates range between 70–80% of cash operating cost). Recent electricity price trends — for example U.S. industrial prices averaging around USD 0.072/kWh in Q4 2023 and rising year‑on‑year — materially affect short‑run marginal costs, plant utilization decisions and contract pricing floors.
-
Capacity cycles: The market is entering a period where newly commissioned ASUs and expansions announced in 2023–2024 begin production. These supply additions have localized effects on liquid versus gaseous argon availability and can compress basis differentials between hubs.
-
Logistics and regulation: Cryogenic transport and storage are under tighter regulatory scrutiny. The EU’s F‑Gas measures and maritime IGC Code requirements for semiconductor‑grade cryogens increase compliance costs and influence modal selection for cross‑border movements.
-
Trade barriers and sourcing: Persistent tariffs and trade policy (including continued U.S. Section 301 measures on certain imports) alter sourcing economics and push both buyers and sellers to re‑evaluate regional sourcing, vertical integration and on‑shore capacity options.
Competitive landscape — what incumbents are doing
-
Linde plc (Woking, UK): A global industrial gases leader, Linde’s network of ASUs and recent European startups aim to secure high‑purity liquid argon supply for electronics and metallurgy clients. Their scale and integrated logistics footprint remain a competitive barrier for new entrants.
-
Air Liquide (Paris, France): With broad ASU coverage and recent multi‑hundred million euro investments targeted at rare gases, Air Liquide is doubling down on higher‑margin specialty flows for semiconductors and healthcare while optimizing regional supply chains.
-
Air Products and Chemicals (Allentown, USA): Large capacity expansions in the Americas reinforce their ability to supply ultra‑high purity argon. Recent ASU commissioning improves their flexibility to serve electronics and steel markets simultaneously.
-
Messer SE & Co. KGaA (Sulzbach, Germany): European‑focused with strength in technical gases for fabrication and emerging additive manufacturing, Messer competes on service models and last‑mile cylinder networks.
-
Iwatani Corporation (Osaka, Japan), Yingde Gases (Shanghai), Gulf Cryo (Dubai) and Norco Group (Brisbane): Regional leaders leveraging local logistics, cost structures and customer intimacy to defend industrial and specialty accounts; their presence matters for regional price formation and tactical sourcing.
Recent corporate moves illustrate the dynamic: Air Products commissioned a new ASU in Geismar (Feb 2024), Linde added capacity in Rotterdam (Oct 2023), and Air Liquide announced a significant ASU investment in Denmark (Jul 2023). These projects are not academic — they shift where and how quickly argon surpluses or tightness appear in 2026 and beyond.
What the PW Consulting report delivers (practical, commercial, executable)
-
Proprietary market model: A bottom‑up supply‑demand matrix and a transparent forecasting engine that supports scenario toggles for energy prices, regional ASU start dates and transport constraints. The model is calibrated to the 2020–2025 historical window and produces node‑level output for 2026–2032.
-
Scenario analysis and stress tests: Three policy and price scenarios illustrate outcomes under (a) energy cost shock, (b) accelerated semiconductor investment, and (c) tightened cryogenic transport regulation. Each scenario maps to P&L and utilization sensitivities for producers and buyers.
-
Commercial playbooks: Supplier selection scorecards, contract clause templates for volume/price flexibility, and negotiation checklists for spot versus long‑term liquid supply — designed for procurement teams to deploy immediately.
-
Investment due diligence kit: CAPEX/OPEX benchmarks for greenfield ASUs, payback matrices under alternate electricity pricing, and a regulatory risk heat‑map to support investment committees and private equity diligence.
-
Competitive intelligence and M&A flags: Company profiles, recent capacity moves, and acquisition opportunity filters that highlight where bolt‑on and transformational deals generate synergies.
-
Supply chain & logistics playbook: Cryogenic transport compliance checklist (including IGC Code considerations for semiconductor‑grade shipments), modal cost comparisons and capex options for on‑site storage versus third‑party bulk tanks.
How C‑suite leaders use this intelligence in 2026
-
Producers: Prioritize ASU projects with the highest geographic margin spread and lowest exposure to rising electricity costs; structure customer contracts with indexed clauses that reflect energy pass‑through elements identified in our model.
-
Downstream manufacturers (semiconductor fabs, steel mills, welding OEMs): Design dual‑sourcing strategies and grade rationalization roadmaps that preserve uptime while optimizing cost per effective delivered liter.
-
Investors/PE: Use the report’s scenario outputs and diligence kit to size equity returns under multiple energy and regulatory states; identify accretive consolidation targets where scale delivers distribution or grade premium advantages.
-
Policy and infrastructure planners: Understand where regulatory changes (e.g., cryogenic refrigerant restrictions) create supply bottlenecks or require logistic investments to maintain critical industrial activity.
Risks, blind spots and issues we model explicitly
-
Energy cost shocks: How a sustained rise in industrial electricity prices erodes margins and what hedging or demand‑side management can mitigate.
-
Transport and compliance shocks: The operational impact and cost of adhering to newer cryogenic transport rules and F‑Gas‑style restrictions on certain refrigerants used in cold‑chain equipment.
-
Trade and tariff volatility: Re‑routing of supply chains due to tariffs and the economic breakeven points for moving production onshore are quantified in our scenario outputs.
Accessing the full intelligence
This bulletin purposely highlights strategic takeaways while withholding detailed segment tables and node‑level forecasts to preserve the tactical value of the full dataset. Licensed subscribers receive the complete forecasting model, downloadable datasets (USD Million time series by node), supplier scorecards and the commercial playbooks referenced above — plus ongoing update briefings as 2026 unfolds.
For procurement leads, corporate strategists and investors who must make or approve capex and supply contracts in 2026, the report is structured to be immediately actionable: plug‑and‑play model inputs, red/amber/green decision triggers, and negotiation language that reflects real market mechanics.
Concluding perspective
The argon market is no longer a simple commodity story. It is a capital‑intensive ecosystem where energy prices, regulatory change and strategic capacity placement define who wins and who is exposed to structural margin erosion. For 2026, the imperative is clear: align capacity decisions, procurement strategy and regulatory compliance planning to the evolving supply topology. PW Consulting’s Worldwide Gas and Liquid Argon Market report offers the calibrated market view and operational toolset needed to execute those decisions with confidence.
To review the full report, model access options, and subscription tiers — and to arrange a bespoke briefing with our lead analysts — please visit the official product page referenced in PW Consulting’s release materials.
For detailed analysis of this topic, please visit the official page: Worldwide Gas and Liquid Argon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pharmaceutical Dyes Market to Grow at a 5.52% CAGR, According to 2025 Insights
By pmarketresearch, 2026-07-15
Worldwide Pharmaceutical Dyes Market: Strategic Imperatives for 2026 — PW Consulting Preview
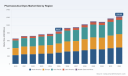
PW Consulting’s newest market intelligence brief, Worldwide Pharmaceutical Dyes Market: Strategic Outlook (base year 2025; historical analysis 2020–2025; forecast period 2026–2032), distills the actionable insights life‑science leaders need to shape decisions in 2026. The report documents a resilient industry that expanded through the first half of the decade and, under a set of near‑term scenarios, is projected to continue growing at a compound annual growth rate of 5.52% across the forecast window. In short: the industry is neither a backwater nor a breakout — it is a mature specialty market where operational execution, regulatory agility, and strategic positioning will determine winners.
Worldwide Pharmaceutical Dyes Market
Why 2026 Is a Strategic Inflection Point
Two parallel dynamics elevate the importance of decisions taken in 2026. First, cost and raw‑material volatility have tightened margins for manufacturers and suppliers alike. Notably, aniline — a primary feedstock for many azo dye chemistries — rose roughly 12% in Q4 2024 to near USD 1,850/MT, translating quickly into higher intermediate costs for synthetic colorants and pressuring procurement strategies.
Worldwide Pharmaceutical Dyes Market
Second, regulatory tightening and heightened import scrutiny are reshaping product compliance thresholds. Recent regional and pharmacopeial changes — for example, lowered permissible lead levels in iron oxide pigments and stricter light‑stability requirements for aluminum lakes — are forcing formulators and colorant suppliers to invest in reformulation, enhanced testing protocols, and traceable supply chains. Further, import alerts have materially increased rejection rates in certain trade lanes, and firms that fail to embed compliance into procurement and production risk market access disruptions.
Worldwide Pharmaceutical Dyes Market
Market Structure — Concentration and Competitive Dynamics
Our market structure analysis finds moderate concentration: the three largest players account for a meaningful but not overwhelming share of industry revenue, while the top five increase that share further. This leaves space for both established producers and specialized challengers to pursue growth through technical differentiation, niche positioning (e.g., natural, clean‑label colorants), and targeted M&A.
- Consolidation pressure: The industry’s CR3 and CR5 metrics indicate room for bolt‑on acquisitions to accelerate scale, broaden regulated product portfolios, and enhance geographic coverage.
- Specialist opportunity: Natural and clean‑label solutions have rising traction among formulators targeting end‑market differentiation, regulatory favorability, and marketing advantages in self‑care and consumer health segments.
- Vertical integration risk/benefit: Buyers with in‑house pigment blending or coating capability can capture margin and speed, but must weigh capital exposure against outsourced, compliance‑certified suppliers.
Competitive Landscape — What the Leading Suppliers Signal
The market’s competitive ledger is defined by a mix of global chemical majors, specialty pigment firms, natural‑ingredient specialists, and regional producers. Key strategic moves from recent quarters point to differentiated routes to capture value:
- Sensient Technologies Corporation (Milwaukee, WI) has doubled down on process‑robust color dispersions for high‑shear coating operations. Its recent product launch emphasizes stability in challenging manufacturing environments — a clear signal that coating reliability is a procurement priority for large formulators.
- Clariant AG (Muttenz, Switzerland) continues to leverage excipient branding and certification strategies (including expanded Halal coverage). Certification and monograph‑alignment remain decisive buying criteria for global supply chains.
- BASF SE (Ludwigshafen, Germany) has invested in capacity expansion for pharmaceutical‑grade iron oxides, anticipating renewed demand — a tactical bet on scale efficiency and assurance of supply amid upstream constraints.
- GNT Group (Mierlo, Netherlands) is the exemplar for natural, fruit‑ and vegetable‑derived colorants aimed at clean‑label formulations — an important growth vector for OTC and consumer health manufacturers seeking to differentiate on label claims.
- Kolor Jet Chemical Pvt Ltd (Vapi, India) and Sun Chemical Corporation (Parsippany, NJ) illustrate the sustained role of regional producers and pigment specialists that combine regulatory compliance (e.g., FD&C/D&C, Halal, Kosher) with competitive export models.
Taken together, these moves indicate an industry balancing product innovation (stability, natural alternatives) with certification and scale. For buyers, the emerging playbook is to treat colorants not as commodity inputs but as regulated, differentiating components of formulation strategy.
Regulatory and Supply Risk Dynamics
Regulatory changes in 2023–2024 are not academic; they are operationally material. Two examples illustrate the point:
- EU action lowering permitted lead in iron oxides tightened supplier specifications and testing regimes, requiring additional supplier validation and remediation timelines.
- USP’s updated monographs introduced more stringent photostability testing for aluminum lakes, which has immediate implications for product shelf‑life claims and packaging specifications.
Compounding these are trade‑lane enforcement actions: elevated FDA import scrutiny in certain source markets led to an observable spike in rejections during 2024, demonstrating that compliance gaps can abruptly remove supply options and force costly last‑minute sourcing shifts.
What PW Consulting’s Report Delivers — Practical, Executable Content
This report was designed to be operational from day one. Clients will find a structured suite of tools and analyses that move beyond descriptive narrative to enable decision execution in 2026:
- Market sizing and trend maps with scenario modelling (base, downside, upside) calibrated to raw‑material price scenarios and regulatory tightening timelines.
- Supplier scorecards that combine technical, regulatory, and commercial KPIs — designed for procurement RFPs and supplier rationalization exercises.
- Regulatory risk matrix with remediation playbooks mapped to product classes (e.g., aluminum lakes, iron oxides, azo derivatives) and to likely timeframes for compliance investment recovery.
- Go‑to‑market playbooks for both incumbent suppliers and new entrants: positioning, channel strategy, formulation partnerships, and pilot‑scale commercialization checklists.
- Procurement and hedging frameworks tailored to raw‑material volatility (including sensitivity analyses tied to aniline price paths and supplier concentration scenarios).
- M&A target shortlists and valuation heuristics for roll‑up strategies focused on technical depth, certified product portfolios, and regional logistics advantage.
We intentionally designed our deliverables to be usable by cross‑functional teams: R&D, regulatory affairs, procurement, and corporate development. The report couples quantitative scenarios with step‑by‑step implementation guidance.
2026 Priorities — Tactical Recommendations for Decision‑Makers
Based on our synthesis of market dynamics, the following priorities should guide executive agendas for 2026:
- Embed regulatory conformity at the start of sourcing: Restrict RFQs to suppliers with validated testing regimes for recent pharmacopeial updates and documented traceability to avoid import disruptions and costly reformulations.
- Hedge raw‑material exposure selectively: Use a mix of multi‑sourced contracts, short‑cycle inventory, and selective forward purchases for feedstocks like aniline to balance cost and availability without creating capital drag.
- Pursue clean‑label adjacencies when they align with brand strategy: For consumer health and self‑care portfolios, prioritize pilot programs with natural colorant specialists and conduct early stability trials to quantify tradeoffs.
- Prioritize suppliers with production scale and certified capacity expansion plans: Capacity commitments — and the ability to demonstrate compliant batch release — are a strategic insurance policy against supply shocks.
- Consider bolt‑on M&A to fill technical gaps: Targets with validated pharmacopeial alignment or proprietary natural‑extraction capabilities can accelerate market access and reduce time‑to‑market for reformulated SKUs.
Investor Lens — Where Value Will Be Created
Investors should watch three vectors where value is most likely to be created between 2026 and 2032:
- Regulatory arbitrage: Suppliers that invest early in upgraded testing and certification will be able to command quality premiums and defend margins.
- Technical differentiation: Proprietary dispersions, light‑stability formulations, and natural pigment extraction processes are defensible features that reduce price elasticity.
- Supply resiliency: Firms that can demonstrably manage feedstock volatility — through integrated sourcing, geographic diversification, or contracted capacity — will garner a valuation premium.
What We Are Not Releasing Here — And Why
Consistent with our “trailer” approach, this release highlights high‑value takeaways while intentionally preserving the granular segmentation tables, regional and application revenue splits, and individual supplier scoring data that form the most commercially sensitive elements of the report. Those appendices contain the precise data points needed to underwrite specific procurement, pricing, and acquisition decisions — and are available in the full report package.
Next Steps and How to Access the Full Intelligence
For teams preparing 2026 budgets, sourcing roadmaps, product roadmaps, or M&A pipelines, PW Consulting’s full report provides the detailed datasets, supplier scorecards, and executable playbooks needed to move from strategy to execution. The full deliverable includes the proprietary financial model (with scenario toggles), validated primary interview transcripts, and regulatory compliance checklists that are absent from this preview.
Contact PW Consulting to schedule a briefing with our senior analysts and to obtain the full Worldwide Pharmaceutical Dyes Market report, including the data appendices and implementation templates that will materially shorten decision cycles and reduce execution risk in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hill-Start Assist Systems Market Set to Reach USD 7,878.16 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Hill-Start Assist Systems Market: Strategic Insights for 2026 Decision Makers
Executive summary
As mobility architectures evolve and safety expectations rise, Hill-Start Assist Systems (HSAS) have transitioned from optional conveniences to near-mandatory safety enablers across multiple vehicle classes. PW Consulting’s latest market study — built on 2020–2025 historical data with a 2026–2032 forecast horizon — quantifies this structural shift and translates it into actionable guidance for C-suite and product leaders planning investments and program roadmaps for 2026 and beyond.
Worldwide Hill-Start Assist Systems Market
Market trajectory and headline metrics
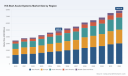
At a macro level, the worldwide HSAS market demonstrates robust expansion. From an estimated USD 3,450 Million in 2020, the market grew steadily through the first half of the decade, reaching USD 4,842.4 Million in the base year 2025. Under the report’s central scenario, the market is forecast to expand at a compound annual growth rate (CAGR) of 7.2% over 2026–2032, approaching roughly USD 7,878 Million by 2032. This growth profile reflects a blend of regulatory pressure, rising penetration of electronic braking and ADAS suites, and platform-level integration strategies by OEMs and Tier-1 suppliers.
Worldwide Hill-Start Assist Systems Market
Concentration metrics further underline competitive dynamics: the top three firms control a meaningful majority of the market (CR3 ~58.4%), while the top five command an even larger share (CR5 ~76.2%). For decision makers, these figures imply a market where scale, integration capability, and safety-system pedigree materially affect win rates for platform-level supply contracts.
Worldwide Hill-Start Assist Systems Market
Why this report matters for 2026 decisions
- Investment prioritization: With HSAS embedded in larger ESC/EPB/ADAS suites, capital allocation across sensor investments, ECU development, and software integration is now a cross-functional decision. The report maps where incremental investment shifts will deliver highest marginal returns.
- Program sourcing and supplier selection: The market’s concentration and the strategic moves by global Tier-1s change the calculus for dual-sourcing versus single-source strategies. Our supplier risk matrix and contract-playbook templates are tailored for 2026 sourcing cycles.
- Product roadmap alignment: OEMs balancing cost, weight, and perceived customer value can use our adoption curves to decide which HSAS architecture (mechanical/hydraulic augmentation vs. fully electronic/EPB-integrated solutions) to prioritize for forthcoming platforms without having to delay feature launch timelines.
- Regulatory & safety compliance planning: With ISO 26262, FMVSS requirements and evolving NCAP recognition increasingly factoring HSAS into overall vehicle safety scoring, the report provides compliance checklists and test-case matrices to de-risk homologation programs slated for 2026–2028.
Strategic levers and scenarios
Our scenario analysis identifies three practical levers for 2026 planning:
- Integration leverage: Prioritizing HSAS as part of an integrated brake/ESC/EPB module reduces system-level costs and accelerates validation efforts. The report quantifies trade-offs between modularity and integrated approaches across development timelines.
- Sensor and software differentiation: As inertial and brake-pressure sensing accuracy becomes a gating factor for advanced features and smoother driver experience, investments in sensor fusion and high-reliability software show outsized ROI — particularly in premium segments and commercial vehicles where driver-assist expectations are higher.
- Aftermarket and retrofit channels: In select markets, retrofit HSAS solutions and commercial-vehicle electronic parking brake (EPB) upgrades create near-term revenue pockets; our targeted market-entry playbooks identify viable go-to-market models without eroding OEM relationships.
Regulatory and safety dynamics shaping 2026 choices
Regulation remains a pivotal externality. HSAS implementations are designed and validated against ISO 26262 functional safety expectations, and electronic parking brake designs must satisfy vehicle braking standards that include holding-force and fail-safe criteria. Additionally, OEMs are increasingly attentive to NCAP and NHTSA recognition of hill-hold functionality within broader ADAS ratings. The report synthesizes these rules into compliance-ready design requirements, test protocols and a prioritized remediation roadmap for legacy platforms.
We also call out operationally relevant advisories from the technical record: for example, field service bulletins related to HSAS valve freezing in certain commercial vehicle builds underline the importance of supply-chain quality and chassis plumbing design choices. That episode — and how easily it could have been mitigated with revision controls and supplier escalation protocols — is used in the report as a case study for program risk management.
Competitive landscape — what the leading firms offer
Our company assessments combine public product disclosures, patent and supplier-intake signals, and recent integration announcements to map supplier capabilities against buyer use-cases. Highlights include:
- Robert Bosch GmbH: Known for integrating “Hill Hold Control” as a value-added function within broader ESP/ESC platforms, Bosch pairs brake-pressure and inertial sensing with rapid-pressure-hold logic to create short-duration hold functions. Their sensor portfolio and ADAS integration depth make them a frequent choice for OEMs seeking bundled safety architectures.
- Continental AG: Offers HSAS as part of a broader electronic braking and ADAS suite, with flexible architectures that can use rear-axle brake intervention or EPB-actuation to prevent rollback. Continental’s strength is in configurable system topologies that suit diverse vehicle platforms.
- ZF Friedrichshafen AG: Supplies integrated electronic braking and control systems that commonly bundle hill-start functionality with ESC and EPB solutions for both passenger and commercial vehicle segments; ZF emphasizes systems-level integration and supplier-to-OEM program management.
- Knorr-Bremse & Bendix: On the commercial-vehicle side, Knorr-Bremse (and its Bendix brand) markets Hill Start Aid capabilities within EBS/EPB portfolios, with recent product integrations addressing heavy-duty Class 8 and medium-duty trucks — a segment where hill-hold and rollaway prevention are mission-critical.
- Aisin, Denso, HELLA and Hyundai Mobis: These players augment braking and drivetrain platforms with HSAS-capable modules and sensor-ECU stacks, often targeting OEMs through direct platform packages or strategic supplier partnerships.
- BWI Group and Murata: Their value-add is component-level expertise — chassis, brake actuation and high-reliability sensor elements — that enable Tier-1 integrators to hit performance and cost targets.
Strategic takeaway: supplier selection is no longer a pure cost play. Certification pedigree, embedded software maturity, and systems-integration experience are the dominant determinants of long-term program success.
Recent industry signals and what they imply
- Vehicle integrations and product launches — for example, a notable full-vehicle rollout of an Intellipark EPB offering for medium and heavy trucks — illustrate continued demand within commercial vehicle segments for EPB-enabled hill-start prevention and rollaway mitigation. Such integrations validate the modular EPB route as a scalable approach for fleets.
- Earlier consumer EV launches that included HSAS highlight the function’s customer-perceived value in urban micro-mobility and small-vehicle segments; this offers OEMs a design opportunity to use smoother hill-start behaviour as a differentiator in crowded urban mobility markets.
- Regulatory bulletins addressing field failures emphasize that design-for-serviceability and environmental robustness must be core design requirements, not afterthoughts.
What’s in the report — practical deliverables for 2026 planning
Built for executives and technical leads, the PW Consulting report includes:
- Macro forecast and scenario suite (2026–2032) with sensitivity testing against commodity-price shocks, policy shifts and EV adoption pathways.
- Supplier capability maps and onboarding scorecards that allow program managers to rapidly qualify Tier‑1 partners by technical scope, safety certification, and integration readiness.
- Commercial templates — supplier negotiation playbooks, sample contract clauses for warranty and field-failure indemnities, and cost-estimation models tied to three HSAS architectures.
- Regulatory compliance checklists and test-sequence templates aligned to ISO 26262 and relevant FMVSS requirements, plus NCAP considerations for program-level safety scoring.
- Case studies on recent field events and product integrations, including root-cause analysis and recommended mitigation measures for future programs.
Note: while this article highlights market trajectory and supplier positioning, detailed segment-level breakdowns (by region, vehicle type or technology variant) and granular vendor share tables are intentionally withheld in this preview. Access to those core datasets and interactive models is available on our report landing page.
Actionable next steps for executives
- Immediate (0–3 months): Incorporate HSAS integration considerations into 2026 platform engineering kickoffs; require supplier evidence of ISO 26262 alignment and environmental robustness during RFQ stage.
- Near-term (3–9 months): Reassess sourcing strategy — evaluate whether to pursue integrated brake/ESC/EPB suppliers or to modularize through component suppliers, using our supplier scorecards as a decision input.
- Strategic (9–18 months): Allocate R&D funds to sensor fusion and software calibration capabilities that will unlock higher-value ADAS features and improved driver experience.
How to obtain the full intelligence
This analysis is a strategic preview designed to orient 2026 planning. The full Worldwide Hill-Start Assist Systems Market report includes the withheld segmentation matrices, interactive forecast models, supplier scorecards and executable templates mentioned above. For procurement teams, product leaders and investors seeking the granular data necessary to finalize 2026 spend and sourcing commitments, please follow the link to the official report page to download the complete dataset and schedule a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Hill-Start Assist Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Paper Release Liner Market at USD 9,261.46M in 2025 — Asia Pacific Leads with USD 3,566.46M as Market Eyes 4.2% CAGR to 2032
By pmarketresearch, 2026-07-15
Worldwide Paper Release Liner Market — Strategic Briefing for 2026 Decision Makers
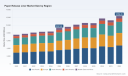
PW Consulting today publishes an executive briefing summarizing the strategic conclusions from our new Worldwide Paper Release Liner Market report (base year 2025, historical 2020–2025, forecast 2026–2032). The global market reached approximately USD 9.26 billion in 2025 and is projected to expand at a mid-single-digit compound annual growth rate (CAGR) through the forecast window. Our research combines plant-level capacity mapping, price and input-cost analytics, primary buyer and supplier interviews, and scenario modelling to translate market dynamics into concrete actions for corporates, investors, and policymakers in 2026.
Worldwide Paper Release Liner Market
Why this report matters in 2026
- Bridge strategy and operations. The report converts macro trends—demand complexion, raw-material pressure, regulatory shifts—into operational decisions: capacity timing, raw material sourcing, and product mix optimization.
- De-risk capital allocation. We model downside and upside scenarios for volumes, prices and margins to stress-test greenfield investment, brownfield debottlenecking and M&A targets.
- Accelerate sustainability compliance. The analysis quantifies implications of evolving packaging mandates and extended producer responsibility schemes on product portfolios, cost-to-serve and certification investments.
- Inform commercial playbooks. Detailed demand drivers and channel dynamics enable sharper pricing strategies, segmentation-led sales tactics, and margin remediation programs.
Scope, methodology and analytical rigor
- Timeframe and coverage: The study uses 2025 as the base year, examines 2020–2025 historical dynamics and provides probabilistic forecasts for 2026–2032.
- Quantitative backbone: Market sizing integrates demand-side flows with supplier capacity and trade balances; our long-form dataset includes annual market value series and a plant-level capacity register.
- Primary validation: More than a hundred interviews across converters, brand owners, liner producers and raw-material suppliers underpin supply‑chain elasticity assumptions and adoption rates of recyclable solutions.
- Price and input indices: Key input indicators—e.g., the US PPI for glassine (index 245.3, Feb 2025) and global bleached kraft pulp benchmarks (averaging roughly USD 780/tonne in late‑2024)—are incorporated into cost-modelled scenarios to stress-test margin sensitivity.
- Concentration and competition: The market exhibits moderate concentration with leading suppliers capturing a material, but not overwhelming, share—an environment that favors both scale plays and focused niches.
Topline market trajectory (high level)
After expanding steadily in the first half of the decade, the paper release liner market accelerated in 2024–2025, reaching roughly USD 9.26 billion in 2025. Under our baseline outlook, the sector grows at a mid-single-digit CAGR through 2032, driven by sustained demand in pressure-sensitive labels and industrial tapes, incremental uptake in medical and hygiene applications, and a widening set of specialty uses in graphics and electronics. The full report provides the complete time-series and scenario outputs; the executive summary and interactive dashboards enable rapid comparison of strategic alternatives.
Worldwide Paper Release Liner Market
Key strategic themes for 2026
- Sustainability as a reshape factor: Regulatory drivers—such as the European Union’s mandate for recycled content in paper packaging by 2030 and country-level EPR regimes—are changing acceptable product specifications and cost allocation across the value chain. Companies that align early with certification schemes and closed-loop designs will gain preferential access to large CPG and retail contracts.
- Input-cost volatility and margin management: Pulp price swings and specialty-paper cost inflation are immediate margin risks. Our cost-build models demonstrate where to prioritize fibre substitution, supplier diversification and pricing clauses to protect margins without sacrificing market share.
- Certification and product safety: For food-contact and hygiene applications, compliance frameworks (e.g., FDA 21 CFR 175.105 for silicone-coated paper) are non-negotiable. Preparing certification roadmaps and low-migration coating portfolios is a 2026 must for producers targeting higher-value segments.
- Innovation and product platforming: Innovations in low-migration silicones, recyclable adhesives and lighter grammage glassine are creating tiered product families. The report identifies which feature combinations command premium pricing and which are rapidly approaching commoditization.
- Regionalisation vs. global optimisation: Logistics and tariff dynamics have renewed interest in regional capacity. We map trade flows and lead times so executives can evaluate near‑shoring and hub‑and‑spoke strategies against total landed cost metrics.
- Consolidation and specialization playbook: With a moderate industry concentration, both scale-focused roll-ups and high-margin specialists have paths to value creation. Our M&A framework prioritizes targets by strategic fit, incremental EBITDA potential and integration risk.
Competitive landscape — what matters
The report profiles global suppliers across their strategic priorities, capacity footprints and innovation pipelines. Representative firms covered include:
Worldwide Paper Release Liner Market
- UPM Raflatac (Finland) — a global leader in sustainable label release liners with a strong paper‑based product portfolio.
- Mondi Group (Austria) — emphasizes recyclable silicone-coated liners and has recent ISCC PLUS certification for targeted lines.
- Sappi (South Africa) — offers premium glassine and coated kraft solutions with recent product showcases at major label events.
- Nippon Paper Industries (Japan) — focused on lightweight glassine for labels and medical tapes.
- Ahlstrom-Munksjö (France) — supplier of silicone release papers for industrial tapes and composites.
- Delfort Group (Austria), Lecta (Spain), Fedrigoni/Arconvert (Italy), Lintec Corporation (Japan) and Verso Corporation (USA) — each occupying differentiated positions across premium glassine, MG papers, and regional supply bases.
Recent corporate moves—product launches, certifications and trade-show unveilings—signal competing priorities: sustainability certifications (e.g., ISCC PLUS), low-migration coatings for food and hygiene, and product launches targeting recyclability and enhanced peel performance. The competitive chapter in the full report benchmarks players on technical capabilities, ESG readiness, customer concentration and cost position.
What the report delivers (practical, executable outputs)
- Decision-grade dashboards with baseline and three alternative scenarios (conservative, base, accelerated) for volume, price and total market value through 2032.
- Supplier scorecards and a plant-level capacity database enabling shortlisting for procurement and M&A diligence.
- Cost-to-serve and landed-cost models integrating pulp price, silicone and logistics inputs for comparative supplier negotiations.
- Regulatory and certification matrix: impacts and timelines for EU packaging rules, national EPR schemes and food-contact compliance.
- Commercial playbooks for premium segment penetration, channel strategies for converters and brand-owner migration paths to recycled-content liners.
- 90/180/360-day implementation roadmaps tailored to producers, converters and raw-material suppliers.
Using the research in 2026 — a tactical roadmap
- 0–90 days: Run a margin heat-map using our input-cost models; secure short-term pulp and silicone hedges; audit compliance exposure in food-contact and hygiene product lines.
- 90–180 days: Pilot recyclable-liner SKUs with anchor customers; pursue rapid certifications where required; implement pricing clauses tied to pulp or index movements.
- 180–360 days: Execute capacity adjustments—whether debottlenecking or targeted greenfield investment—based on the scenario that best matches your risk appetite; pursue M&A targets identified via our strategic fit matrix.
How PW Consulting’s analysis adds unique value
- Actionable, not academic: Each insight is mapped to a decision and an owner (commercial, procurement, R&D or corporate development) with estimated timelines and resource implications.
- Integrated risk modeling: We translate raw-material indices and regulatory shifts into P&L and cash-flow implications under multiple macro scenarios.
- Vendor-neutral diligence: Our supplier benchmarking is structured for use in both procurement negotiations and buy‑side diligence.
Next steps and access
This briefing outlines the strategic contours; the full Worldwide Paper Release Liner Market report contains the granular datasets, interactive visualisations and the confidential appendices that empower execution. Corporate subscribers receive a tailored 90‑minute briefing with scenario runs against their specific commercial footprint and a starter workbook for implementation. To access the complete intelligence, interactive tools and appendices, please visit the PW Consulting report page or contact your client engagement lead.
PW Consulting’s market team stands ready to co-develop a 2026 action plan that aligns your capital, operations and commercial engines to the structural changes reshaping the paper release liner value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Release Liner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Automatic Thermoforming Vacuum Machine Market to Expand at a Robust 5.4% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Automatic Thermoforming Vacuum Machine Market — Strategic Outlook for 2026 Decision-Making
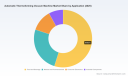
PW Consulting’s latest market study on the Worldwide Automatic Thermoforming Vacuum Machine market (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro growth trends, supplier dynamics, regulatory pressure points and operational levers that will determine winners and losers through the next strategic planning cycle. With the market growing at a projected 5.4% CAGR into the forecast window and an established trajectory from approximately USD 725 million in 2020 to roughly USD 950 million in 2025 — and a forecast that points to just under USD 1.38 billion by 2032 — the timing to translate insight into decisive capital and product strategy is now.
Worldwide Automatic Thermoforming Vacuum Machine Market
Why this report matters for 2026 corporate planning
- Evidence-based prioritization: 2026 budgets must reconcile rising input costs, regulatory obligations and the continuing push for packaging automation. Our analysis quantifies the relative impact of these drivers on capital allocation, product roadmaps and retrofit schedules.
- Risk-adjusted investment guidance: We convert market growth and concentration metrics into practical thresholds for greenfield purchases, capacity expansion and lease-versus-buy decisions, enabling CFOs and plant leaders to set hurdle rates that reflect current market dynamics.
- Competitive playbook: For commercial leaders, the report maps supplier capabilities, recent product trajectories and alliance opportunities so go-to-market strategies can be aligned with real supplier roadmaps and adoption cycles.
- Procurement and supply continuity: The study contains supply-chain stress tests and contingency planning templates that procurement teams can operationalize immediately to mitigate raw-material and semiconductor volatility.
Headline market dynamics
The market’s steady compound annual growth rate of 5.4% through the forecast window belies a landscape of asymmetric pressure points. Key macro-drivers include persistent labor shortages in food processing that are accelerating demand for automation, heightened regulatory and safety expectations in developed markets, and a rising cost base for key machine inputs.
Worldwide Automatic Thermoforming Vacuum Machine Market
- Automation imperative: Continued labor constraints are forcing processors to prioritize uptime, consistency and traceability — attributes where automatic thermoforming vacuum systems deliver measurable value. The report quantifies the payback windows under multiple throughput scenarios and workforce availability assumptions.
- Cost inflation and input volatility: Stainless steel frame costs and servo motor pricing have both shown meaningful increases in the most recent cycles, affecting BOMs and total installed cost. Our sensitivity analysis isolates the impact of raw-material and semiconductor-driven component inflation on purchase decisions and TCO modelling.
- Regulatory and energy considerations: Ongoing regulatory developments, including enhanced machinery safety interlock requirements and energy-management standards such as ISO 50001, are shifting specifications for new machine purchases and retrofits. The report includes a compliance-impact matrix to speed up CAPEX approvals and technical procurement specifications.
- Concentration and supplier influence: Market concentration data indicate moderate consolidation: the top three and top five suppliers account for a material share of market value, which has implications for pricing power, lead times and aftermarket service models. We provide negotiation playbooks calibrated to these concentration dynamics.
Practical contents you can act on
This is not an academic exercise. The report is designed as an operational toolkit for teams executing 2026 initiatives. Key deliverables include:
Worldwide Automatic Thermoforming Vacuum Machine Market
- An executable CAPEX decision framework that translates throughput, cycle-time, product-mix and labor-cost variables into projected payback timelines and IRR bands for new automatic thermoforming vacuum equipment.
- Supplier benchmarking templates that score vendors across performance dimensions: throughput, changeover speed, energy efficiency, integration friendliness and aftermarket support.
- Technical specification checklists tied to regulatory compliance (e.g., vacuum safety interlocks and energy management), enabling procurement to issue compliant RFQs that reduce rework and lead-time slippage.
- Scenario-based TCO models that incorporate raw-material and component price volatility, spare-part strategies, and the operational impact of energy-efficiency upgrades.
- An M&A and partnership playbook that maps inorganic opportunities and strategic alliances — useful for companies seeking to accelerate capability acquisition or secure critical supply lines.
- Field-proven retrofit and modernization roadmaps for installed bases, showing where targeted automation upgrades deliver the highest incremental throughput and lowest disruption.
Competitive landscape — what to watch in 2026
The supplier environment is a mix of global engineering houses and specialized regional manufacturers. PW Consulting’s competitive assessment focuses on capability clusters rather than absolute market shares, helping clients match their technical and commercial requirements to the right partner archetype.
- Global engineering leaders: Established multi-national OEMs continue to dominate high-throughput lines and integrated packaging systems. Their recent product introductions emphasize smart controls, AI-enabled servo tuning and higher output density — important if your strategy hinges on scale and turnkey integration.
- Specialist innovators: Several mid-sized European firms are advancing modular and compact thermoforming platforms aimed at flexible production and lower TCO for medium-run customers. These vendors can be preferred partners for strategies that prioritize agility and fast changeovers.
- Regional champions: Suppliers focused on regional service and rapid spare-part logistics remain attractive where uptime and proximity to service teams outweigh marginal differences in unit cost.
Notable recent vendor moves illustrate the competitive tempo: a leading German group showcased AI-enabled smart thermoformers at a European trade show in late 2024; a Spanish OEM revealed an active-roller thermoformer at a major North American expo in 2024; and product launches and certification updates from German and other European suppliers in early-to-mid 2025 demonstrate an industry-wide push on efficiency and compliance. PW Consulting evaluates these developments in the context of adoption curves and service economics so buyers can prioritize trials and pilot integrations.
Supply chain and cost implications
Two categories of supply pressure require immediate attention in 2026 procurement plans: material and electronic controls. Stainless-steel framing and precision sheet components have experienced meaningful upward pressure, while the availability and cost of servo motors and related controls remain sensitive to semiconductor supply cycles. Our procurement playbook prescribes hedging strategies, dual-sourcing templates, and lead-time buffers linked to specific procurement triggers.
- Adopt a component-level qualification process to accelerate substitute sourcing where semiconductor-driven lead times are a bottleneck.
- Incorporate indexed pricing clauses for long-lead contracts to balance supplier risk and avoid margin erosion.
- Evaluate energy-efficiency premiums against operational electricity rates and ISO 50001 alignment costs to determine true lifecycle economics.
Strategic recommendations for 2026
For executive teams preparing 2026 investments, our top-level guidance is focused, pragmatic and prioritized:
- Prioritize pilot-to-scale programs: Begin with limited pilots to validate integration and OEE improvements before committing to line-wide rollouts. Ensure pilot contracts include defined ramp metrics and performance SLAs.
- Design procurement for volatility: Use flexible contracting, component-level qualification and staged payments tied to delivery milestones to de-risk lead-time and cost uncertainty.
- Lock in aftermarket service frameworks: Given the role of uptime in ROI, secure multi-year service agreements with defined response times and spares commitments — even if that increases upfront cost modestly.
- Embed regulatory compliance in specs: Mandate safety interlocks and energy-management documentation in RFQs to avoid retrofits and compliance-related downtimes post-installation.
- Revisit portfolio and product-fit: Manufacturers of packaged goods should map product families to thermoforming typologies and evaluate whether continuous, single-station or rotary platforms best match required flexibility and cost profiles (the report offers evaluation templates for this exercise).
What the report does not disclose — and why
In line with the “trailer” principle, this public summary highlights the analytic frame, strategic recommendations and the operational toolset contained in the full report while deliberately withholding detailed proprietary segment-level allocations and exit-case financials that clients use to make transactional decisions. The full report contains granular regional and application-level forecasts, supplier scorecards with quantified capability indices, and downloadable TCO models that are essential for binding procurement and investment approvals.
How to use the report in your 2026 planning cycle
PW Consulting recommends a three-step adoption pathway:
- Executive briefing: Use the strategic summary and concentration analysis to align leadership on investment priorities and risk tolerance.
- Operational rollout: Deploy the procurement templates, compliance checklists and pilot frameworks to accelerate RFQ cycles and reduce spec rework.
- Continuous review: Re-run the report’s scenario models against your actual pilot outcomes to refine CAPEX sizing and rollout schedules before scaling.
For organizations evaluating supplier selection, capacity expansion or retrofit investments in 2026, PW Consulting’s study translates the broad market trajectory — from the market’s strong recovery post-2020 through the 2025 base year and an optimistic yet pragmatic 2026–2032 forecast — into actionable tactics that reduce installation risk, speed time-to-value and improve negotiating leverage with suppliers.
To access the full report, including the proprietary regional and application breakouts, the supplier scorecards, and the downloadable TCO and RFQ templates designed for immediate deployment in 2026 procurement cycles, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Thermoforming Vacuum Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com