

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hill-Start Assist Systems Market Set to Reach USD 7,878.16 Million by 2032

Worldwide Hill-Start Assist Systems Market: Strategic Insights for 2026 Decision Makers
Executive summary
As mobility architectures evolve and safety expectations rise, Hill-Start Assist Systems (HSAS) have transitioned from optional conveniences to near-mandatory safety enablers across multiple vehicle classes. PW Consulting’s latest market study — built on 2020–2025 historical data with a 2026–2032 forecast horizon — quantifies this structural shift and translates it into actionable guidance for C-suite and product leaders planning investments and program roadmaps for 2026 and beyond.
Worldwide Hill-Start Assist Systems Market
Market trajectory and headline metrics
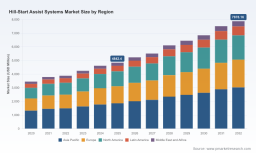
At a macro level, the worldwide HSAS market demonstrates robust expansion. From an estimated USD 3,450 Million in 2020, the market grew steadily through the first half of the decade, reaching USD 4,842.4 Million in the base year 2025. Under the report’s central scenario, the market is forecast to expand at a compound annual growth rate (CAGR) of 7.2% over 2026–2032, approaching roughly USD 7,878 Million by 2032. This growth profile reflects a blend of regulatory pressure, rising penetration of electronic braking and ADAS suites, and platform-level integration strategies by OEMs and Tier-1 suppliers.
Worldwide Hill-Start Assist Systems Market
Concentration metrics further underline competitive dynamics: the top three firms control a meaningful majority of the market (CR3 ~58.4%), while the top five command an even larger share (CR5 ~76.2%). For decision makers, these figures imply a market where scale, integration capability, and safety-system pedigree materially affect win rates for platform-level supply contracts.
Worldwide Hill-Start Assist Systems Market
Why this report matters for 2026 decisions
- Investment prioritization: With HSAS embedded in larger ESC/EPB/ADAS suites, capital allocation across sensor investments, ECU development, and software integration is now a cross-functional decision. The report maps where incremental investment shifts will deliver highest marginal returns.
- Program sourcing and supplier selection: The market’s concentration and the strategic moves by global Tier-1s change the calculus for dual-sourcing versus single-source strategies. Our supplier risk matrix and contract-playbook templates are tailored for 2026 sourcing cycles.
- Product roadmap alignment: OEMs balancing cost, weight, and perceived customer value can use our adoption curves to decide which HSAS architecture (mechanical/hydraulic augmentation vs. fully electronic/EPB-integrated solutions) to prioritize for forthcoming platforms without having to delay feature launch timelines.
- Regulatory & safety compliance planning: With ISO 26262, FMVSS requirements and evolving NCAP recognition increasingly factoring HSAS into overall vehicle safety scoring, the report provides compliance checklists and test-case matrices to de-risk homologation programs slated for 2026–2028.
Strategic levers and scenarios
Our scenario analysis identifies three practical levers for 2026 planning:
- Integration leverage: Prioritizing HSAS as part of an integrated brake/ESC/EPB module reduces system-level costs and accelerates validation efforts. The report quantifies trade-offs between modularity and integrated approaches across development timelines.
- Sensor and software differentiation: As inertial and brake-pressure sensing accuracy becomes a gating factor for advanced features and smoother driver experience, investments in sensor fusion and high-reliability software show outsized ROI — particularly in premium segments and commercial vehicles where driver-assist expectations are higher.
- Aftermarket and retrofit channels: In select markets, retrofit HSAS solutions and commercial-vehicle electronic parking brake (EPB) upgrades create near-term revenue pockets; our targeted market-entry playbooks identify viable go-to-market models without eroding OEM relationships.
Regulatory and safety dynamics shaping 2026 choices
Regulation remains a pivotal externality. HSAS implementations are designed and validated against ISO 26262 functional safety expectations, and electronic parking brake designs must satisfy vehicle braking standards that include holding-force and fail-safe criteria. Additionally, OEMs are increasingly attentive to NCAP and NHTSA recognition of hill-hold functionality within broader ADAS ratings. The report synthesizes these rules into compliance-ready design requirements, test protocols and a prioritized remediation roadmap for legacy platforms.
We also call out operationally relevant advisories from the technical record: for example, field service bulletins related to HSAS valve freezing in certain commercial vehicle builds underline the importance of supply-chain quality and chassis plumbing design choices. That episode — and how easily it could have been mitigated with revision controls and supplier escalation protocols — is used in the report as a case study for program risk management.
Competitive landscape — what the leading firms offer
Our company assessments combine public product disclosures, patent and supplier-intake signals, and recent integration announcements to map supplier capabilities against buyer use-cases. Highlights include:
- Robert Bosch GmbH: Known for integrating “Hill Hold Control” as a value-added function within broader ESP/ESC platforms, Bosch pairs brake-pressure and inertial sensing with rapid-pressure-hold logic to create short-duration hold functions. Their sensor portfolio and ADAS integration depth make them a frequent choice for OEMs seeking bundled safety architectures.
- Continental AG: Offers HSAS as part of a broader electronic braking and ADAS suite, with flexible architectures that can use rear-axle brake intervention or EPB-actuation to prevent rollback. Continental’s strength is in configurable system topologies that suit diverse vehicle platforms.
- ZF Friedrichshafen AG: Supplies integrated electronic braking and control systems that commonly bundle hill-start functionality with ESC and EPB solutions for both passenger and commercial vehicle segments; ZF emphasizes systems-level integration and supplier-to-OEM program management.
- Knorr-Bremse & Bendix: On the commercial-vehicle side, Knorr-Bremse (and its Bendix brand) markets Hill Start Aid capabilities within EBS/EPB portfolios, with recent product integrations addressing heavy-duty Class 8 and medium-duty trucks — a segment where hill-hold and rollaway prevention are mission-critical.
- Aisin, Denso, HELLA and Hyundai Mobis: These players augment braking and drivetrain platforms with HSAS-capable modules and sensor-ECU stacks, often targeting OEMs through direct platform packages or strategic supplier partnerships.
- BWI Group and Murata: Their value-add is component-level expertise — chassis, brake actuation and high-reliability sensor elements — that enable Tier-1 integrators to hit performance and cost targets.
Strategic takeaway: supplier selection is no longer a pure cost play. Certification pedigree, embedded software maturity, and systems-integration experience are the dominant determinants of long-term program success.
Recent industry signals and what they imply
- Vehicle integrations and product launches — for example, a notable full-vehicle rollout of an Intellipark EPB offering for medium and heavy trucks — illustrate continued demand within commercial vehicle segments for EPB-enabled hill-start prevention and rollaway mitigation. Such integrations validate the modular EPB route as a scalable approach for fleets.
- Earlier consumer EV launches that included HSAS highlight the function’s customer-perceived value in urban micro-mobility and small-vehicle segments; this offers OEMs a design opportunity to use smoother hill-start behaviour as a differentiator in crowded urban mobility markets.
- Regulatory bulletins addressing field failures emphasize that design-for-serviceability and environmental robustness must be core design requirements, not afterthoughts.
What’s in the report — practical deliverables for 2026 planning
Built for executives and technical leads, the PW Consulting report includes:
- Macro forecast and scenario suite (2026–2032) with sensitivity testing against commodity-price shocks, policy shifts and EV adoption pathways.
- Supplier capability maps and onboarding scorecards that allow program managers to rapidly qualify Tier‑1 partners by technical scope, safety certification, and integration readiness.
- Commercial templates — supplier negotiation playbooks, sample contract clauses for warranty and field-failure indemnities, and cost-estimation models tied to three HSAS architectures.
- Regulatory compliance checklists and test-sequence templates aligned to ISO 26262 and relevant FMVSS requirements, plus NCAP considerations for program-level safety scoring.
- Case studies on recent field events and product integrations, including root-cause analysis and recommended mitigation measures for future programs.
Note: while this article highlights market trajectory and supplier positioning, detailed segment-level breakdowns (by region, vehicle type or technology variant) and granular vendor share tables are intentionally withheld in this preview. Access to those core datasets and interactive models is available on our report landing page.
Actionable next steps for executives
- Immediate (0–3 months): Incorporate HSAS integration considerations into 2026 platform engineering kickoffs; require supplier evidence of ISO 26262 alignment and environmental robustness during RFQ stage.
- Near-term (3–9 months): Reassess sourcing strategy — evaluate whether to pursue integrated brake/ESC/EPB suppliers or to modularize through component suppliers, using our supplier scorecards as a decision input.
- Strategic (9–18 months): Allocate R&D funds to sensor fusion and software calibration capabilities that will unlock higher-value ADAS features and improved driver experience.
How to obtain the full intelligence
This analysis is a strategic preview designed to orient 2026 planning. The full Worldwide Hill-Start Assist Systems Market report includes the withheld segmentation matrices, interactive forecast models, supplier scorecards and executable templates mentioned above. For procurement teams, product leaders and investors seeking the granular data necessary to finalize 2026 spend and sourcing commitments, please follow the link to the official report page to download the complete dataset and schedule a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Hill-Start Assist Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com