

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Gas & Liquid Argon Market Poised for 5.42% CAGR to 2032 as Asia Pacific Surges

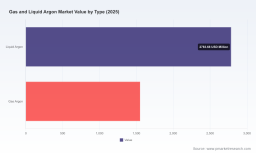
Worldwide Gas and Liquid Argon Market: Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market research — Worldwide Gas and Liquid Argon Market (Base Year: 2025) — provides a focused, decision‑grade vantage point for executives and investors preparing strategy in 2026. The global argon market has grown from roughly USD 3,324.5 Million in 2020 to USD 4,333.45 Million in 2025 and is forecast to expand to approximately USD 6,270.4 Million by 2032, implying a compounded annual growth rate of 5.42% across the 2026–2032 forecast window. Market concentration underscores a moderately consolidated landscape, with the top three suppliers controlling just over half of global supply and the top five approaching seven in ten dollars of revenue — a structural reality that shapes pricing, capacity investment and M&A calculus.
Worldwide Gas and Liquid Argon Market
Why this report matters for 2026
-
Timing: 2026 is the inflection year for many producers and end-users. Near‑term capital deployments (new ASUs, cryogenic logistics upgrades) announced in 2023–2024 arrive online and materially change local availability and pricing dynamics in target markets.
Worldwide Gas and Liquid Argon Market -
Risk management: Energy cost volatility and evolving transport regulations introduce execution risk into both production and distribution models. Understand where margin squeeze is likely, and where contract renegotiation or hedging is critical.
Worldwide Gas and Liquid Argon Market -
Opportunity capture: Semiconductor, advanced manufacturing and certain energy applications continue to be outsized demand drivers. Identifying the right product grade, delivery mode and commercial model in 2026 will determine who captures premium demand through 2032.
Key demand and supply dynamics shaping 2026 strategy
-
Energy intensity and cost structure: Argon is produced via energy‑intensive air separation; electricity represents the dominant portion of production costs (industry estimates range between 70–80% of cash operating cost). Recent electricity price trends — for example U.S. industrial prices averaging around USD 0.072/kWh in Q4 2023 and rising year‑on‑year — materially affect short‑run marginal costs, plant utilization decisions and contract pricing floors.
-
Capacity cycles: The market is entering a period where newly commissioned ASUs and expansions announced in 2023–2024 begin production. These supply additions have localized effects on liquid versus gaseous argon availability and can compress basis differentials between hubs.
-
Logistics and regulation: Cryogenic transport and storage are under tighter regulatory scrutiny. The EU’s F‑Gas measures and maritime IGC Code requirements for semiconductor‑grade cryogens increase compliance costs and influence modal selection for cross‑border movements.
-
Trade barriers and sourcing: Persistent tariffs and trade policy (including continued U.S. Section 301 measures on certain imports) alter sourcing economics and push both buyers and sellers to re‑evaluate regional sourcing, vertical integration and on‑shore capacity options.
Competitive landscape — what incumbents are doing
-
Linde plc (Woking, UK): A global industrial gases leader, Linde’s network of ASUs and recent European startups aim to secure high‑purity liquid argon supply for electronics and metallurgy clients. Their scale and integrated logistics footprint remain a competitive barrier for new entrants.
-
Air Liquide (Paris, France): With broad ASU coverage and recent multi‑hundred million euro investments targeted at rare gases, Air Liquide is doubling down on higher‑margin specialty flows for semiconductors and healthcare while optimizing regional supply chains.
-
Air Products and Chemicals (Allentown, USA): Large capacity expansions in the Americas reinforce their ability to supply ultra‑high purity argon. Recent ASU commissioning improves their flexibility to serve electronics and steel markets simultaneously.
-
Messer SE & Co. KGaA (Sulzbach, Germany): European‑focused with strength in technical gases for fabrication and emerging additive manufacturing, Messer competes on service models and last‑mile cylinder networks.
-
Iwatani Corporation (Osaka, Japan), Yingde Gases (Shanghai), Gulf Cryo (Dubai) and Norco Group (Brisbane): Regional leaders leveraging local logistics, cost structures and customer intimacy to defend industrial and specialty accounts; their presence matters for regional price formation and tactical sourcing.
Recent corporate moves illustrate the dynamic: Air Products commissioned a new ASU in Geismar (Feb 2024), Linde added capacity in Rotterdam (Oct 2023), and Air Liquide announced a significant ASU investment in Denmark (Jul 2023). These projects are not academic — they shift where and how quickly argon surpluses or tightness appear in 2026 and beyond.
What the PW Consulting report delivers (practical, commercial, executable)
-
Proprietary market model: A bottom‑up supply‑demand matrix and a transparent forecasting engine that supports scenario toggles for energy prices, regional ASU start dates and transport constraints. The model is calibrated to the 2020–2025 historical window and produces node‑level output for 2026–2032.
-
Scenario analysis and stress tests: Three policy and price scenarios illustrate outcomes under (a) energy cost shock, (b) accelerated semiconductor investment, and (c) tightened cryogenic transport regulation. Each scenario maps to P&L and utilization sensitivities for producers and buyers.
-
Commercial playbooks: Supplier selection scorecards, contract clause templates for volume/price flexibility, and negotiation checklists for spot versus long‑term liquid supply — designed for procurement teams to deploy immediately.
-
Investment due diligence kit: CAPEX/OPEX benchmarks for greenfield ASUs, payback matrices under alternate electricity pricing, and a regulatory risk heat‑map to support investment committees and private equity diligence.
-
Competitive intelligence and M&A flags: Company profiles, recent capacity moves, and acquisition opportunity filters that highlight where bolt‑on and transformational deals generate synergies.
-
Supply chain & logistics playbook: Cryogenic transport compliance checklist (including IGC Code considerations for semiconductor‑grade shipments), modal cost comparisons and capex options for on‑site storage versus third‑party bulk tanks.
How C‑suite leaders use this intelligence in 2026
-
Producers: Prioritize ASU projects with the highest geographic margin spread and lowest exposure to rising electricity costs; structure customer contracts with indexed clauses that reflect energy pass‑through elements identified in our model.
-
Downstream manufacturers (semiconductor fabs, steel mills, welding OEMs): Design dual‑sourcing strategies and grade rationalization roadmaps that preserve uptime while optimizing cost per effective delivered liter.
-
Investors/PE: Use the report’s scenario outputs and diligence kit to size equity returns under multiple energy and regulatory states; identify accretive consolidation targets where scale delivers distribution or grade premium advantages.
-
Policy and infrastructure planners: Understand where regulatory changes (e.g., cryogenic refrigerant restrictions) create supply bottlenecks or require logistic investments to maintain critical industrial activity.
Risks, blind spots and issues we model explicitly
-
Energy cost shocks: How a sustained rise in industrial electricity prices erodes margins and what hedging or demand‑side management can mitigate.
-
Transport and compliance shocks: The operational impact and cost of adhering to newer cryogenic transport rules and F‑Gas‑style restrictions on certain refrigerants used in cold‑chain equipment.
-
Trade and tariff volatility: Re‑routing of supply chains due to tariffs and the economic breakeven points for moving production onshore are quantified in our scenario outputs.
Accessing the full intelligence
This bulletin purposely highlights strategic takeaways while withholding detailed segment tables and node‑level forecasts to preserve the tactical value of the full dataset. Licensed subscribers receive the complete forecasting model, downloadable datasets (USD Million time series by node), supplier scorecards and the commercial playbooks referenced above — plus ongoing update briefings as 2026 unfolds.
For procurement leads, corporate strategists and investors who must make or approve capex and supply contracts in 2026, the report is structured to be immediately actionable: plug‑and‑play model inputs, red/amber/green decision triggers, and negotiation language that reflects real market mechanics.
Concluding perspective
The argon market is no longer a simple commodity story. It is a capital‑intensive ecosystem where energy prices, regulatory change and strategic capacity placement define who wins and who is exposed to structural margin erosion. For 2026, the imperative is clear: align capacity decisions, procurement strategy and regulatory compliance planning to the evolving supply topology. PW Consulting’s Worldwide Gas and Liquid Argon Market report offers the calibrated market view and operational toolset needed to execute those decisions with confidence.
To review the full report, model access options, and subscription tiers — and to arrange a bespoke briefing with our lead analysts — please visit the official product page referenced in PW Consulting’s release materials.
For detailed analysis of this topic, please visit the official page: Worldwide Gas and Liquid Argon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com