

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti‑Blue Ray Myopia Lenses Market to Expand at 8.15% CAGR — from USD 4,285.5 Million in 2025 to USD 7,416.29 Million by 2032, Led by Asia Pacific (USD 1,820.6M)

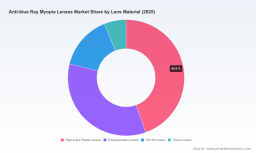
Worldwide Anti-blue Ray Myopia Lenses Market: Strategic Insights for 2026 Decision-Makers
Executive snapshot
As the anti-blue ray myopia lenses market approaches a pivotal inflection, PW Consulting’s latest market study provides a practical, decision-ready map for executives planning 2026 strategies. Our analysis shows the global market reached a significant scale by the 2025 base year and is projected to grow at a compound annual growth rate (CAGR) of 8.15% across the 2026–2032 forecast horizon. This trajectory reflects the combined impact of clinical validation of myopia-slowing spectacle technologies, rising digital device use among children and adolescents, and faster adoption of integrated blue-light mitigation across lens portfolios.
Worldwide Anti-blue Ray Myopia Lenses Market
Why this report matters for 2026 planning
- Timing of regulatory and clinical signals is creating windows of opportunity for premium product launches, channel reconfiguration, and strategic partnerships.
- Market expansion at an >8% CAGR means capacity planning, supply-chain resilience and margin management should move from tactical to strategic planning in 2026.
- Increasing product convergence—myopia management optics combined with anti-blue light functions—requires coordinated R&D, IP strategy and clinical affairs investments to protect differentiation.
What the report delivers (practical, implementable content)
PW Consulting designed this report as an executable playbook for commercial, R&D and corporate development leaders. Key components include:
Worldwide Anti-blue Ray Myopia Lenses Market
- Proven forecasting model calibrated to five years of historical data (2020–2025) and stress-tested under three adoption scenarios for 2026–2032.
- Go-to-market frameworks tailored to different company archetypes (incumbent lens manufacturers, optical retailers, clinic chains, and digital-first e-commerce players).
- Pricing and margin models that translate material, coating and value-add features into SKU-level profitability guidance—with worked examples for trade-offs between premium coatings and high-index substrates.
- Regulatory roadmap templates and clinical evidence strategies to support market authorization and reimbursement conversations in major jurisdictions.
- Supply-chain diagnostics and mitigation playbooks covering resin suppliers, coating lines, and contract manufacturing capacity, with supplier-risk heatmaps and near-term contingency plans.
- A compact M&A and partner-screening matrix identifying target profiles, integration risks and value-creation levers for roll-up or bolt-on acquisitions.
- Executive scorecards and KPIs for 2026 implementation—covering adoption, channel performance, ASP trajectory, customer retention and R&D throughput.
Market dynamics and structural drivers
Several persistent forces are shaping the competitive landscape. First, clinical validation of spectacle-based myopia management has moved from academic debate into commercial reality, creating durable demand for spectacle-based solutions that can credibly claim to slow progression in pediatric populations. Second, the ubiquitous growth in screen time among children and adolescents is increasing demand for lenses that combine optical myopia-management functions with blue-light mitigation to address both progression risk and digital eye strain. Third, technology choices—substrate absorption vs. coating-based blue-light solutions and the selection of high-index resins—are now central to value propositions rather than peripheral manufacturing decisions.
Worldwide Anti-blue Ray Myopia Lenses Market
Competitive landscape: who matters and why
The market is neither a pure commodity nor a highly fragmented cottage industry; it displays clear leader positions alongside nimble regional specialists. Market concentration metrics indicate a meaningful presence of top-tier players, with the top three and top five firms together accounting for material shares of supply—an important consideration for suppliers, buyers and investors planning 2026 moves.
Key players profiled in the report include global incumbents and regional manufacturers with distinct strategic postures:
- EssilorLuxottica (Essilor): With Stellest lenses and the H.A.L.T. platform, Essilor now occupies a leading position in clinically validated spectacle myopia management. Recent regulatory milestones have strengthened its commercial credibility and provide a benchmark for competitors’ evidence strategies.
- HOYA Vision Care: HOYA’s MiYOSMART product family, enhanced by recent coating innovations (STX), highlights how incremental but high-impact product engineering—durable hydrophobic coatings, long-life AR and integrated blue-light filtering—can sustain differentiation in mature product lines.
- ZEISS: With MyoCare and myopia management optics, ZEISS is focused on optical design sophistication and professional channel partnerships, emphasizing optometrist- and ophthalmologist-led adoption paths.
- Regional manufacturers (China-based and other OEMs): A number of vertically integrated regional players supply a wide spectrum of anti-blue and myopia-control lenses, combining product breadth with local regulatory registration and cost-competitive manufacturing; these firms are critical partners for scale and serve as both competitors and suppliers to global chains.
- Optics specialists and tier-2 brands (Nikon, Shamir, and others): These players compete on precision optics, coating chemistry and channel relationships, often pursuing selective premiumization strategies or targeting niche clinical use-cases.
Recent developments that will shape 2026 strategies
- Regulatory validation: The U.S. FDA’s marketing authorization for Essilor Stellest as a spectacle lens indicated to slow pediatric myopia progression represents a watershed moment. This accelerates adoption among practitioners and sets new evidentiary expectations for alternatives.
- Product enhancements: HOYA’s rollout of the Smooth Touch Xtreme (STX) coating on its MiYOSMART line signals the importance of durability and surface performance as commercial differentiators—especially for child- and school-age users.
- Platform evolution: Continued product-line investments by major incumbents (e.g., Essilor’s platform expansions) underscore a move toward integrated platforms combining optics, coatings and service offerings (e.g., clinician training, digital adherence tools).
Technology and materials outlook
Commercial anti-blue ray myopia lenses today leverage two principal technical approaches: intrinsic substrate absorption (e.g., UV420 absorption factors built into lens monomers) and multi-layer coating systems applied to high-index resins. Each approach has trade-offs: substrate absorption provides persistent filtering without changing surface coatings but can complicate tinting and photochromic performance; coatings enable tunable spectral profiles and higher surface performance but raise durability and cost considerations. High-index resin grades and innovations in AR/hydrophobic coatings are the levers that will determine product ASPs and margin pools in 2026.
Channel and consumer behavior implications
Digital-native consumer behaviors, particularly among families with school-age children, are driving hybrid route-to-market strategies. Clinician endorsement remains a critical trust cue for myopia management products, while e-commerce channels accelerate reach and pricing transparency. For manufacturers and retailers alike, the 2026 priority is to design omnichannel strategies that preserve clinical routing for diagnosis and evidence-based fitting while enabling direct-to-consumer education and replenishment models for lens upgrades.
Supply chain, manufacturing, and risk management
Meeting growing demand without margin erosion requires a two-pronged approach: (1) tactical capacity upgrades in high-value production lines—coating cells, high-index polymer molding and precision surfacing—and (2) strategic partnerships with regional contract manufacturers to hedge geopolitical and logistics risk. Inventory strategies will need to balance SKU proliferation (due to combinations of index, coating and myopia designs) against working capital constraints.
M&A, partnership and go-to-market playbook for 2026
Our deal-screening logic in the report helps identify targets that can rapidly expand technical capability (coating, substrate technology), channel access (clinic chains, optical retail partnerships), or geographic footprint. Successful value creation will hinge on integration of clinical data assets and the ability to accelerate commercialization through clinician outreach programs and digital adherence tools.
Scenarios and KPIs
The report includes three plausible market scenarios—conservative adoption, baseline growth and accelerated diffusion—each paired with tailored KPIs (adoption velocity, clinician conversion rates, ASP evolution, channel mix metrics, and R&D time-to-evidence). These scenarios enable executive teams to stress-test capital allocation, production planning and sales incentives for 2026.
How senior executives should use this report in 2026
- CEOs & Boards: Use the scenario-based capital allocation guidance to set 2026 capex priorities (coating lines, clinical trials budget, digital platforms).
- Commercial leaders: Implement the go-to-market playbooks to sequence clinician engagement, retail promotions and digital campaigns that protect ASPs while maximizing penetration.
- R&D & Regulatory: Adopt the regulatory roadmap and evidence-generation templates to compress approval timelines in target jurisdictions and to design post-market surveillance strategies.
- M&A & Strategy teams: Apply the partner-screening matrix and integration playbook to prioritize acquisitions that fill capability gaps within a 9–18 month execution window.
What we intentionally withhold here—and why
This briefing is designed as a “trailer”: it demonstrates our analytical depth and practical orientation while intentionally omitting certain granular segmentation and price-matrix tables to preserve the report’s role as a commercial intelligence product. Detailed regional and application splits, SKU-level price elasticity matrices, and the full set of supplier-level forecasts are reserved for the full report and interactive dashboards available from PW Consulting.
Next steps
For executives who must convert 2026 uncertainty into advantage, our full Worldwide Anti-blue Ray Myopia Lenses Market report delivers the data, models and playbooks required to act confidently. The full deliverable includes downloadable scenario models, executive dashboards, supplier heatmaps and a confidential M&A target list—tools designed for fast, operational decision-making.
Contact PW Consulting to request access to the full report, schedule a tailored strategy workshop, or commission custom scenario modeling for your organization’s portfolio decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-blue Ray Myopia Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com